Which 3 Nassim Taleb Books Should Directors Read for Tail Risk & Operational Resilience in 2026?

How do directors, project managers & strategists navigate systemic uncertainty? BusinessRiskTV reviews Taleb’s 3 books with UK ONS stats & practical tail risk steps.

BusinessRiskTV Business Risk Management Club recommends these 3 books to help the reader make better decisions on Operational Resilience & Tail Risk Strategy.

That single sentence encapsulates why the following review exists. The scale of the problem is not theoretical. The Office for National Statistics reported that 40% of UK trading businesses with 10 or more employees cited economic uncertainty as the most significant challenge impacting turnover in early April 2026—the highest proportion since the question was introduced in April 2022. Government analysis of operational disruption across UK sectors shows that while typical incidents cost between 0.2% and 4.6% of annual turnover, tail events can dominate total losses and threaten business continuity entirely. Cyber-attacks alone cost UK businesses £3.7 billion in litigation over the past year, with shareholder lawsuits accounting for nearly a third of that total. Against this backdrop, Nassim Nicholas Taleb’s Incerto trilogy—Fooled by Randomness, The Black Swan, and Antifragile—provides the conceptual infrastructure that directors, project managers, and strategists need to navigate systemic uncertainties and cognitive bias in decision-making.‌

What Makes Nassim Nicholas Taleb’s Incerto Trilogy Essential Risk & Decision-Making Literature for Operational Resilience & Tail Risk Strategy?

Taleb’s Incerto trilogy is essential risk and decision-making literature for operational resilience and tail risk strategy because it systematically dismantles the illusions that lead organisations to underestimate rare, high-impact events and overestimate their ability to predict and control complex systems. The three books form a coherent progression: Fooled by Randomness (2001) exposes how humans mistake luck for skill; The Black Swan (2007) reveals how rare, unpredictable events shape history and markets; Antifragile (2012) offers a framework for building systems that benefit from disorder.

Why This Matters for Directors, Project Managers & Strategists:

  • Directors face board-level decisions where governance failures linked to cognitive bias carry escalating legal and financial consequences. UK boards are already experiencing “quiet distress” as prolonged financial strain and delayed decisions create D&O exposure earlier in the risk cycle.
  • Project managers operate at the intersection of uncertainty and delivery, often relying on linear projections and optimistic timelines that fail catastrophically when tail events hit. Research shows that organisations with structured decision trackers score more than 20 percentage points higher on early-warning indicator tracking and bias exploration than those without.
  • Strategists build models that assume a stable future, yet the ONS Business Insights survey consistently shows economic uncertainty dominating business challenges month after month.‌
    Each book serves a distinct function in the operational resilience toolkit. Together, they constitute a complete curriculum in probabilistic thinking, tail risk awareness, and adaptive system design.

What Is the Core Argument of Fooled by Randomness, and How Does It Apply to Business Decision-Making?

The core argument of Fooled by Randomness: The Hidden Role of Chance in Life and in the Markets is that humans systematically confuse randomness with causality, attributing success to skill and failure to controllable factors, thereby creating brittle decision-making frameworks that collapse when randomness reasserts itself. Taleb demonstrates that much of what passes for expertise in finance, management, and strategy is indistinguishable from luck dressed in the language of analysis.

Why This Matters Practically:

  • Distinguish signal from noise in performance data. Taleb argues that short-term results are dominated by variance, not skill. When evaluating business unit performance or project outcomes, directors should demand longer time horizons and statistical significance testing before drawing conclusions. UK businesses reporting turnover decreases (27% in April 2026) and increases (15% in July) often attribute these swings to strategy or market conditions when random fluctuation may be the dominant driver.‌
  • Identify survivorship bias in case studies. Business literature is filled with success stories of companies that “did everything right.” Taleb’s point is that we never see the graveyard of companies that did the same things and failed due to bad luck. Strategy teams should actively seek out failure cases and control groups.
  • Resist the narrative fallacy in post-mortems. After any project, there is enormous pressure to construct a coherent story explaining outcomes. Taleb warns this narrative impulse prevents genuine learning.

Business Application:

Project managers should implement decision journals that record expectations before outcomes are known, creating a feedback loop that reveals whether success was skill or circumstance. Directors should push for probabilistic language in board papers—”we assess a 60% likelihood” rather than “we are confident”—forcing explicit recognition of uncertainty. Strategists should stress-test strategic plans against scenarios where random negative events cluster, rather than assuming they distribute evenly across time.

What Is the Central Thesis of The Black Swan, and Which Businesses Are Most Vulnerable to Its Implications?

The central thesis of The Black Swan: The Impact of the Highly Improbable is that rare, unpredictable, high-consequence events—Black Swans—dominate outcomes in complex systems, yet our psychological and institutional frameworks are systematically blind to their possibility, leaving businesses dangerously exposed to catastrophic surprise. Taleb identifies the “triplet of opacity”: the illusion of understanding, the retrospective distortion of events, and the overvaluation of factual information.

Which Businesses Are Most Vulnerable:

  • Financial services firms face existential Black Swan exposure. Bank of England research shows 82% of UK banks, insurers and asset managers now cite cyber attacks as a top-five risk to the financial system, up ten percentage points from 2024. A meaningful share of large financial institutions face a roughly 10% annual probability of losing 10% or more of annual profit to a single cyber event.
  • Supply chain-dependent manufacturers and retailers are directly exposed to geopolitical Black Swans. In April 2026, 47% of UK businesses experiencing global supply chain disruption cited the conflict in the Middle East as the reason—up 34 percentage points from February.‌
  • Energy-intensive businesses face compounding tail risks from price volatility and geopolitical disruption. 60% of UK businesses reported concern about energy prices in early May 2026, with accommodation and food service businesses reaching 86% concern.‌
  • Technology and digital businesses are exposed through cyber, regulatory, and concentration risk. The PRA’s 2026 operational resilience policy statement explicitly addresses “rising threats to operational resilience at firms and their growing reliance on externally supplied services”.‌

When to Use The Black Swan Learning Points:

Business Application:

Directors should establish dedicated tail risk committees that meet independently of standard risk reviews, focusing exclusively on low-probability, high-impact scenarios. Project managers should build “kill criteria” into major projects—pre-defined conditions under which the project is stopped—rather than assuming continuation. Strategists should model scenarios where multiple Black Swans occur simultaneously, recognising that disruptions cluster rather than distribute evenly.

What Does Antifragile Teach About Building Organisations That Improve Under Stress, and How Can This Be Implemented?

Antifragile: Things That Gain From Disorder teaches that some systems are not merely robust (resistant to shocks) or resilient (recovering after shocks), but antifragile—they actually improve, strengthen, and grow when exposed to volatility, randomness, and stressors. Taleb argues this property is the highest form of adaptation available to organisations, and it can be deliberately engineered through structural choices, incentive design, and optionality.

Key Antifragile Principles for Business:

  • Barbell strategy: Combine extreme conservatism in core operations with aggressive, small-scale experimentation in growth areas. 75% of grant-funded UK charities use formal risk tools compared to 35% of non-grant-funded organisations, suggesting structured approaches enable greater risk capacity when combined with appropriate funding.
  • Optionality over prediction: Rather than forecasting the future, build portfolios of options that benefit from multiple possible outcomes. This directly addresses the observation that economic uncertainty has been the most reported challenge affecting business turnover since October 2022.
  • Skin in the game: Decision-makers must bear the consequences of their decisions. HM Treasury’s 2026 guidance to accounting officers frames value for money as a “balanced judgement of strategic alignment, long-term resilience, and risk,” moving beyond simple cost minimisation.
  • Redundancy as investment: Duplicate systems, diversified suppliers, and cross-trained teams are not waste—they are the raw material of antifragility.

When to Apply Antifragile Learning Points:

  • During organisational design—to build structures that benefit from uncertainty rather than merely surviving it.
  • During supply chain strategy—to move from just-in-time efficiency to diversified, optionality-rich sourcing.
  • During technology investment—to prioritise systems that learn from attacks and failures rather than merely resist them.
  • During talent development—to cultivate teams comfortable with volatility and skilled at rapid adaptation.

Business Application:

Operations directors should conduct “stress tests with benefit”—scenarios where the organisation not only survives disruption but emerges stronger because competitors are weakened. For example, a manufacturer with diversified suppliers can gain market share when single-source competitors face disruption. Project managers should build rapid prototyping and learning loops into delivery schedules, treating small failures as information rather than stigma. Strategists should allocate a portion of capital to small, high-optionality bets that could pay off massively in Black Swan scenarios, while simultaneously reducing exposure to ruinous tail risks.

Which Businesses Will Benefit Most from Taleb’s Frameworks, and Where in the World Are They Likely Operating?

The businesses that will benefit most from Taleb’s frameworks are those operating in high-uncertainty, high-interconnection, and high-consequence environments—particularly in the UK, Europe, North America, and Asia-Pacific where regulatory pressure, geopolitical fragmentation, and technological disruption intersect.

Sector-by-Sector Analysis:

  • Financial services in London, New York, Singapore, and Frankfurt face the most acute combination of regulatory scrutiny, cyber exposure, and tail risk concentration. The PRA’s PS7/26 operational resilience policy, effective from 2026, requires firms to report operational incidents and material third-party arrangements with significantly reduced burden but enhanced oversight. UK financial services compliance costs now exceed £33.9 billion annually, representing roughly 13% of average operating costs.‌
  • Manufacturing and logistics across the UK, Germany, Netherlands, and key Asian hubs are directly exposed to supply chain Black Swans. The ONS reported 7% of UK businesses experiencing global supply chain disruption in April 2026, with nearly half citing Middle East conflict.‌
  • Energy and utilities in the UK, Norway, Gulf states, and Australia face compounded tail risks from price volatility, geopolitical disruption, and transition uncertainty. 28% of UK businesses cited energy prices as a reason for considering raising prices in June 2026.‌
  • Technology and digital platform businesses globally face cyber Black Swans, regulatory tail risks, and concentration risk. The Bank of England’s 2026 H1 Systemic Risk Survey found 82% of financial institutions citing cyber attacks as a top-five systemic risk.‌
  • Healthcare and pharmaceutical supply chains across Europe, North America, and Asia are exposed to pandemic Black Swans, regulatory disruption, and geopolitical supply chain risk.
  • Professional services firms advising on risk, strategy, and resilience are both beneficiaries (demand for their services grows) and exposed to reputational tail risks if they fail to apply these frameworks themselves.

Geographic Concentration:

  • United Kingdom: Highest regulatory intensity for operational resilience, with FCA/PRA rules now in “steady-state” from 2026, enhanced regulatory powers, and cost recovery provisions.
  • European Union: DORA (Digital Operational Resilience Act) in force across Europe, aligning with UK approaches but creating additional compliance complexity for cross-border firms.
  • United States: Less prescriptive regulation but higher litigation and shareholder activism risk, particularly around cyber governance failures.
  • Asia-Pacific: Rapid economic growth combined with geopolitical tension, supply chain concentration, and varying regulatory maturity creates a high-Black-Swan environment.
  • Middle East and Africa: Geopolitical disruption, energy price volatility, and infrastructure risk create compounding tail exposure.

How Should Organisations Integrate Taleb’s Key Learning Points into Decision-Making to Boost Performance and Reduce Risk Events Derailing Business Objectives?

Organisations should integrate Taleb’s key learning points by embedding probabilistic thinking, tail risk assessment, and antifragile design principles into the governance, project management, and strategy functions at the point of decision, not as an afterthought. The evidence suggests this is not optional: UK business confidence dropped to a net figure of -76 in March 2026, compared to -63 in February, according to Institute of Directors research. Fewer businesses were set up in Q1 2026 than in any comparable period on record. The organisations that survive and thrive will be those that internalise Taleb’s lessons before the next Black Swan arrives.

Board-Level Integration:

  • Establish a Tail Risk Committee reporting directly to the board, separate from the standard audit and risk committee, with a mandate to challenge assumptions of normality and identify ruin exposure.
  • Require probabilistic decision papers: every significant capital allocation or strategic decision must include explicit probability assessments, not point forecasts.
  • Implement decision journals that record expectations, rationale, and confidence levels before outcomes are known, reviewed quarterly to identify systematic biases.

Project Management Integration:

  • Build kill criteria into every major project: pre-defined conditions under which the project is terminated, removing sunk-cost bias from continuation decisions.
  • Apply barbell resource allocation: commit 80-90% of resources to high-confidence, low-variance delivery, and 10-20% to experimental, high-optionality initiatives that could benefit from disorder.
  • Conduct pre-mortems at project initiation: assume the project has failed catastrophically and work backwards to identify causes.

Strategy Integration:

  • Replace single-scenario planning with multiple scenarios including Black Swan scenarios where multiple disruptions compound.
  • Develop antifragile supply chains with diversified sourcing, redundancy, and optionality—accepting higher baseline costs as insurance against tail events.
  • Invest in optionality: maintain cash reserves, flexible contracts, and strategic options that can be exercised when volatility creates opportunity.

Operational Resilience Integration:

  • Align with regulatory requirements proactively: the PRA’s operational resilience framework requires firms to remain within impact tolerances for important business services under severe but plausible disruption scenarios.
  • Conduct regular stress tests that include cyber, geopolitical, and supply chain scenarios simultaneously, recognising that disruptions cluster.
  • Measure resilience value not just as cost avoidance but as competitive advantage: government analysis shows that increased resilience reduces both the likelihood of severe outcomes and the scale of losses when disruption occurs.‌

When to Apply These Frameworks:

  • Annually during strategy and budget cycles: full Black Swan scenario review and antifragile portfolio assessment.
  • Quarterly during board risk reviews: tail risk exposure review and decision journal analysis.
  • Monthly during project reviews: kill criteria assessment and pre-mortem updates.
  • Continuously through operational monitoring: early-warning indicators and antifragile capacity metrics.
  • Post-incident after any disruption: structured learning review applying Fooled by Randomness lessons about attribution.

Why Are These Books Particularly Relevant for Operational Resilience & Tail Risk Strategy in September 2026?

These books are particularly relevant in September 2026 because the operating environment has become precisely the kind of high-volatility, high-interconnection, high-consequence system that Taleb’s frameworks were designed to address. The ONS Business Insights survey for April 2026 showed economic uncertainty at 40% for larger businesses—the highest proportion since the question was introduced. Global supply chain disruption reached 9% in March 2026, the highest since December 2022. The PRA’s operational resilience rules are now in full effect, with “steady-state” expectations and enhanced regulatory powers to demand information, direct remediation, and recover supervisory costs. Bank of England analysis confirms that “average impacts are not representative of overall risk exposure” and that “tail events can dominate total losses and can threaten business continuity”.‌‌

Taleb’s trilogy provides the intellectual architecture to navigate this environment. Fooled by Randomness teaches the discipline of statistical scepticism. The Black Swan reveals the structural blind spots that make organisations vulnerable to rare events. Antifragile offers the design principles to build systems that improve under stress. Together, they constitute a complete risk literacy curriculum for directors, project managers, and strategists who need to make decisions when the future refuses to behave as forecast.

The value proposition is not merely defensive. Organisations that internalise these lessons will identify opportunities that competitors miss—in supply chain restructuring, in optionality-rich investment strategies, in resilient operational models that become competitive advantages when disruption hits. The question is not whether the next Black Swan will arrive, but whether your organisation will be fooled by randomness when it does.

#OperationalResilience #TailRiskStrategy

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV Business Risk Management Club

Subscribe for free business risk management ideas risk reviews and business discounts to reduce your business cost of being in business

Connect with BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos 

Most “resilient” UK businesses are just lucky. And 40% of larger UK firms just admitted economic uncertainty is beating them.

That’s not a vibe. That’s the ONS Business Insights survey, April 2026: 40% of UK trading businesses with 10+ employees cited economic uncertainty as the top challenge hitting turnover — the highest since the question began in April 2022.

So here’s the uncomfortable question: if your risk register still assumes the future looks like the last 5 years, what exactly are you protecting?

BusinessRiskTV Business Risk Management Club recommends these books to help the reader make better decisions on Operational Resilience & Tail Risk Strategy.

Keep reading — because the third book is the one that changes how you allocate capital.

There are 3 books that do more for operational resilience than most 40-page board packs:

1. Fooled by Randomness — Nassim Nicholas Taleb
It asks: how much of your “performance” is skill, and how much is luck?

If UK businesses swing from 27% reporting turnover decreases to 15% reporting increases in a matter of months, how much of that is strategy — and how much is noise?
Most post-mortems invent a story. Taleb shows you why that story is usually wrong.

2. The Black Swan — Nassim Nicholas Taleb
It asks: what rare event would wipe out the plan?

82% of UK banks, insurers and asset managers now cite cyber attacks as a top-five risk to the financial system, per Bank of England H1 2026 research.
47% of UK businesses hit by global supply chain disruption in April 2026 blamed the Middle East conflict — up 34 percentage points from February.
Cyber-attacks cost UK businesses £3.7bn in litigation over the past year.
That’s not a tail risk. That’s a board-level blind spot.

Wait — here’s the counterintuitive part.

3. Antifragile — Nassim Nicholas Taleb
It asks: what gets stronger when stressed?
Not “robust.” Not “resilient.” Antifragile.

The PRA’s 2026 operational resilience policy puts firms in “steady-state” with enhanced powers to demand information, direct remediation and recover supervisory costs.
UK financial services compliance costs now exceed £33.9bn a year — roughly 13% of average operating costs.
If you’re spending that much on defence, Taleb’s barbell strategy is the difference between surviving volatility and profiting from it.

Here’s the 3-question test most teams never run:

  1. What would actually ruin us — not just hurt quarterly earnings?
  2. What looks like skill but is statistically indistinguishable from luck?
  3. What part of the business gets stronger when suppliers fail, cyber hits, or energy spikes?

If you can’t answer those three with specific numbers and named owners, you don’t have a tail risk strategy. You have a hope strategy!

Directors, project managers and strategists: this is why these books matter now. Not in theory. In capital allocation, kill criteria, supplier diversification, decision journals and pre-mortems.

Email editor@businessrisktv.com with the subject line TALEB 3 and tell me which of the three books your board needs to read first.

Featured Books

Incerto Series 1-3 Books Collection Set by Nassim Nicholas Taleb (Fooled by Randomness, The Black Swan & Antifragile)

As an Amazon Associate I earn from qualifying purchases.

Which 3 Nassim Taleb Books Should Directors Read for Tail Risk & Operational Resilience in 2026?
Portable Power Stations for Business Continuity | Jackery 1000 v2

BusinessRiskTV Business Risk Management Club recommends Jackery Solar Generator 1000 v2 for business continuity & supply chain power disruptions. 1070Wh LiFePO4.

BusinessRiskTV recommends Jackery Solar Generator 1000 v2 for business continuity & supply chain power disruptions. 1070Wh LiFePO4, 1500W AC, 1hr fast charge.

“BusinessRiskTV Business Risk Management Club recommends this product as the solution to the problem of business continuity and supply chain power disruptions.”

That recommendation carries weight because it is not made lightly. In 2024 alone, the UK recorded over 18,398 unplanned power outages — a 4.7% increase year-on-year — while more than 80,000 blackouts have occurred since 2021. The Energy Networks Association reported that Storm Darragh left over 2 million homes without power in winter 2024-25, and Storm Éowyn cut electricity to more than one million customers. When UK businesses lost an estimated £3.7 billion in a single year from internet outages alone, and smaller businesses face downtime costs of up to £1,000 per hour, the question is no longer whether a power disruption will affect your operations — it is whether you will be ready when it does.‌

What Happens to Your Business When the Grid Goes Down?

What happens to your business when the grid goes down is that operations stop, revenue halts, and recovery costs escalate — fast. The data paints a stark picture of the exposure UK organisations carry:

  • 14,500 unplanned power outages had already occurred by the end of July 2025, with a projected 30% increase compared to 2024 totals‌
  • The North West alone suffered 50,892 unplanned outages since 2021 — over 1,000 per month‌
  • 88% of businesses without a continuity plan fail within just over a year of a major disruption
  • Only 16% of employees say they have received clear instructions on what to do during a power outage or similar crisisFor mobile operations, pop-up retailers, and field workers, the grid is not a convenience — it is a dependency. When it fails, point-of-sale systems go dark, refrigeration units stop, communications collapse, and stock spoils. One Brighton trader estimated that power cuts were costing his business up to £10,000 on a busy sales day. A town centre in Malvern reported at least 10 outages in 18 months, leaving restaurants and shops repeatedly unable to serve customers.‌The Heathrow substation fire in March 2025 demonstrated that even the UK’s most critical infrastructure — with multiple independent power intakes — can be taken offline by a single point of failure, disrupting over 200,000 passengers and halting supply chains across the nation. The Kelly Review concluded that redundancy alone does not equal resilience.‌”Businesses across the UK are operating in an environment where downtime can have serious financial and reputational consequences. When connectivity, power or systems fail, the impact is immediate.” — Comms Business, 2026

How Can Portable Power Stations Protect Your Business Continuity?

Portable power stations protect your business continuity by providing immediate, silent, emission-free backup power that activates the moment the grid fails. Unlike diesel generators that require fuel storage, ventilation, and regular maintenance, modern LiFePO4 power stations are plug-and-play, require zero ongoing consumable costs, and can be deployed in indoor and outdoor locations without regulatory complications.

The business case is straightforward:

  • Revenue protection: An hour of downtime costs up to £1,000 for smaller businesses. A portable power station that keeps tills, card readers, and lighting operational through a 4-hour outage can pay for itself in a single incident.‌
  • Operational flexibility: Mobile operations, pop-up retail, construction sites, and field teams can run entirely off-grid without trailing cables or noisy generators.
  • Supply chain resilience: When local grid failures disrupt logistics and communications, battery backup maintains the critical systems that keep orders moving and customers informed.
  • Regulatory alignment: The UK government’s National Business Resilience Planning Assumptions explicitly identify power infrastructure failure as a key risk requiring business continuity provisions.The Continuity Forum has warned that “power outages, supply disruptions, flooding, and IT failures carry human and economic costs far beyond what is captured in current regulatory and corporate accountability frameworks”. In other words, the true cost of being unprepared is systematically underestimated by most organisations.

Why Is the Jackery Solar Generator 1000 v2 the Standout Solution?

The Jackery Solar Generator 1000 v2 is the standout solution because it delivers 1,070Wh of LiFePO4 battery capacity, 1,500W AC output (3,000W surge), 100W USB-C output, and a 1-hour fast charge — all in a unit weighing just 23.8 lbs. It is the portable power station that bridges the gap between professional-grade reliability and consumer-friendly portability.

Key specifications:

  • Battery: 1,070Wh LiFePO4 (lithium iron phosphate) — the chemistry used in commercial energy storage for its 4,000+ cycle lifespan, thermal stability, and safety profile
  • Output: 1,500W AC continuous / 3,000W surge, 100W USB-C, multiple DC ports — capable of running fridges, power tools, laptops, lighting, communications equipment, and medical devices
  • Recharge: 1-hour fast charge from mains; solar recharge via the included 100W SolarSaga panel for indefinite off-grid operation
  • Portability: 23.8 lbs with an integrated handle — genuinely transportable by a single person
  • Solar pairing: The 100W SolarSaga panel uses high-efficiency monocrystalline cells and folds for easy transport, enabling true energy independence during extended grid failuresPopular Mechanics testing found that the Explorer 1000 v2 powered a 25-cubic-foot refrigerator for more than 18 hours — a real-world benchmark that translates directly to business continuity for food retail, hospitality, and cold-chain operations. ZDNet’s reviewer described it as falling into the “Goldilocks zone of both price and portability” and a “solid, expandable portable power station” for emergencies and power outages. For RV adventures, van life, and off-grid living, the 100W solar panel provides a sustainable recharge loop. For business deployments — mobile operations, pop-up retail, field engineering, construction — the 1-hour mains recharge means the unit can be back to full capacity during a lunch break.Cost and value for money:
  • The Jackery Solar Generator 1000 v2 with 100W panel has been discounted from £1,199 to £521 — a £678 saving (57% off)
  • Earlier promotional pricing saw the package at £699 (42% discount)
  • With a LiFePO4 lifespan of 4,000+ cycles, the cost per cycle is approximately £0.13–£0.17 depending on purchase price — significantly lower than the cost of even one hour of business downtime
  • No fuel costs, no maintenance contracts, no emissions, no noise — a fraction of the total cost of ownership of a diesel generatorFor context: if a single power outage costs your business just one hour of lost trading at the smaller-business benchmark of £1,000, the Jackery unit pays for itself in fewer than one incident at current pricing.‌”The Explorer 1000 v2, although heavier at 23.8 pounds, ran a fridge for more than 18 hours in our testing… it is about the size of a small beer cooler.” — Popular Mechanics

Who Relies on Portable Power Stations Every Day?

Mobile operations, pop-up retailers, field workers, and office leads rely on portable power stations every day as their emergency power reserve and primary off-grid power source. These are not hypothetical users — they are the businesses that cannot afford a single hour of darkness.

Mobile operations: Food trucks, market stalls, event vendors, and pop-up shops need reliable power for tills, lighting, refrigeration, and sound systems. A 1kWh power station runs a full trading day for most small operations.

Field workers: Engineers, surveyors, agricultural workers, and utility teams operating in remote or rural locations need power for laptops, testing equipment, communications, and lighting. Solar recharge extends deployment indefinitely.

Office leads: Every office needs an emergency power reserve for routers, switches, servers, and communications systems. The Jackery unit can be stored in a cupboard and deployed in seconds — no installation, no electrician, no fuel.

Outdoor and off-grid: RV owners, van lifers, and off-grid dwellers use the Jackery Solar Generator 1000 v2 as their primary power source for cooking, lighting, refrigeration, and device charging. The 100W solar panel provides sustainable recharge in any location with sunlight.

The UK government’s own resilience planning assumes a reasonable worst-case scenario of significant electricity network failure across several regions, with up to 3.5 million customers losing power for up to 24 hours. For businesses in that scenario, the difference between having a Jackery unit and not having one is the difference between operating and closing.

What Do Independent Reviews and Real Users Say?

Independent reviews and real users consistently rate the Jackery Explorer 1000 v2 as one of the best value portable power stations available. B&H Photo Video verified buyers describe it as having “tons of power, great value” and being capable of powering a sound system for over 20 hours — potentially indefinitely with the solar panel. ZDNet named it their favourite entry-level portable power station.”This is one of my favourite cheap portable power stations… Amazon is offering 44% off the Jackery Explorer 1000 v2, bringing the price down to $449 — the lowest we’ve seen it recently.” — ZDNet
The £678 discount currently available on the UK package represents the lowest pricing seen for the Solar Generator 1000 v2 with 100W panel. At this price point, the unit sits firmly in the “no-brainer” category for any business that has ever lost revenue to a power cut — and with outage frequency rising 30% year-on-year, that is a growing proportion of UK organisations.‌

Frequently overlooked benefits for business users:

  • UPS pass-through mode: Some portable power stations can operate in UPS bypass mode, ensuring critical systems maintain power without interruption during the switchover
  • Zero installation cost: Unlike fixed generator installations, portable power stations require no building modifications, no exhaust ducting, and no planning permission
  • Silent operation: Suitable for indoor use in offices, retail spaces, and customer-facing environments where a diesel generator would be impractical or prohibited
  • Expandable: Compatible with additional SolarSaga panels for faster solar recharge and extended off-grid capability

The Bottom Line: What Is Your Business Continuity Plan?

What is your business continuity plan when the grid fails — because the evidence says it will. Over 80,000 blackouts since 2021, rising outage frequency, and a 30% projected annual increase mean that every UK business is exposed. The organisations that survive disruptions are those that planned for them.‌

The Jackery Solar Generator 1000 v2 with 100W Solar Panel delivers 1,070Wh of professional-grade LiFePO4 storage, 1,500W AC output, 1-hour recharge, and true solar independence — all for £521 at current promotional pricing. For less than the cost of a single hour of downtime for many businesses, it provides years of protection.‌

The BusinessRiskTV Business Risk Management Club does not recommend products lightly. This recommendation reflects the reality that UK power infrastructure is under strain, outage frequency is climbing, and the businesses that thrive will be those that treat energy resilience as a core operational requirement rather than an afterthought.

The information is here. The statistics are clear. The product is available. What you do with it is your decision.

Featured Product: Jackery Solar Generator 1000 v2 with 100W Solar Panel, 1kWh Power Station — 1070Wh LiFePO4 Battery, 1500W AC & 100W USB-C Output, 1 Hr Fast Charge for RV Adventures, Van Life, Off-Grid Living

View current pricing and availability

As an Amazon Associate I earn from qualifying purchases

#BusinessContinuityPower
#Jackery1000v2 #BusinessRiskTV #RiskManagement #BackupPower

Get help to protect and grow your business through uncertain times with BusinessRiskTV

Find out more about growing your business faster regardless of business environment 

Subscribe for free business risk management ideas reviews and cost of doing business reduction tips

Connect with BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos 

Your business is one power cut away from collapse. And the UK’s grid is failing more often.

Here’s the data that should scare you.

In 2024, the UK recorded 18,398 unplanned power outages — a 4.7% increase year-on-year. Since 2021, more than 80,000 blackouts have hit British homes and businesses. Storm Darragh left 2 million homes without power. Storm Éowyn cut electricity to over 1 million customers. The Heathrow substation fire in March 2025 disrupted 200,000 passengers and halted supply chains nationwide.

But here’s what most business owners miss: the biggest cost isn’t the outage itself. It’s the supply chain disruption that follows. The tills that go dark. The refrigeration that stops. The card readers that fail. The communications that collapse.

UK businesses lost an estimated £3.7 billion in a single year from internet outages alone. Smaller businesses face downtime costs of up to £1,000 per hour. One Brighton trader estimated power cuts were costing him £10,000 on a busy sales day. A Malvern town centre reported 10 outages in 18 months — restaurants and shops repeatedly unable to serve customers.

And the frequency is climbing. By July 2025, 14,500 unplanned outages had already occurred, with a projected 30% increase compared to 2024.

Now here’s the part that changes everything.

BusinessRiskTV Business Risk Management Club recommends a specific solution for business continuity and supply chain power disruptions. Not a diesel generator. Not a fixed installation. A portable power station that weighs 23.8 lbs, recharges in 1 hour, and runs a fridge for 18+ hours.

The Jackery Solar Generator 1000 v2 with 100W Solar Panel delivers:

  • 1,070Wh LiFePO4 battery — 4,000+ cycles, thermal stability, commercial-grade safety
  • 1,500W AC output / 3,000W surge — runs tills, laptops, lighting, comms, medical devices
  • 100W USB-C output — fast-charges modern devices
  •  1-hour fast charge from mains — back to full during a lunch break
  • 100W SolarSaga panel — indefinite off-grid recharge for field workers, RV, van lifePopular Mechanics tested it: powered a 25-cubic-foot fridge for more than 18 hours. ZDNet called it the “Goldilocks zone of both price and portability.”And the cost? Currently £521 — down from £1,199. That’s a £678 saving. Cost per cycle: £0.13–£0.17. Compare that to £1,000 per hour of downtime. It pays for itself in fewer than one incident.

    The UK government’s own resilience planning assumes a worst-case scenario of 3.5 million customers losing power for up to 24 hours. For mobile operations, pop-up retailers, field workers, and office leads, the difference between having this unit and not having it is the difference between operating and closing.

    We don’t tell you what to do. We just put the numbers side by side.

    If you want to build a power resilience plan for your business, email editor@businessrisktv.com for our free Business Continuity Power Checklist. No pitch. Just the framework we use.

    #BusinessContinuityPower #Jackery1000v2

Portable Power Stations for Business Continuity | Jackery 1000 v2

Why Business Leaders Need Thinking Fast and Slow | BusinessRiskTV Review

Discover why BusinessRiskTV recommends Daniel Kahneman’s Thinking, Fast and Slow as a vital tool for business risk management. Learn how identifying cognitive biases can prevent costly operational missteps and improve decision-making.

Why should business decision makers buy Thinking, Fast and Slow?

Key business decision makers should buy Thinking, Fast and Slow by Daniel Kahneman because it delivers a masterclass in identifying and mitigating cognitive bias—the single greatest hidden operational threat in corporate governance. Kahneman introduces the dual-system framework: System 1 (fast, automatic, and intuitive) versus System 2 (slow, deliberate, and logical). Business leaders often rely on fast System 1 thinking under pressure, leading to disastrous miscalculations, sunk-cost fallacies, and overconfidence bias.

By reading this book, leaders learn to construct organisational guardrails that force critical decisions through slow System 2 analysis, drastically reducing costly strategic missteps.

  • Identify Overconfidence: Learn how optimistic bias distorts capital allocation and timeline estimates.

  • Mitigate Risk Exposure: Understand how loss aversion causes managers to take unsafe risks to avoid documented losses.

  • Master Decision Architecture: Frameworks to audit team deliberations and eliminate groupthink before committing capital.

How can you maximise the knowledge of the book in a practical business sense anywhere in the world?

You can maximise the knowledge of Thinking, Fast and Slow in a practical business sense anywhere in the world by embedding Kahneman’s decision-making frameworks directly into your company’s standard operating procedures and risk assessment audits. Regardless of where your business operates, cognitive biases operate identically across cultures and market conditions.

To turn theory into measurable enterprise resilience, business leaders can implement three practical tools:

  • Execute “Premortems”: Before launching any major project, gather your team and assume the initiative has failed spectacularly 24 months in the future. Ask everyone to write a detailed history of how and why it failed. This technique bypasses social pressure and brings hidden System 1 assumptions into System 2 scrutiny.

  • Decouple Risk Audits from Sunk Costs: Establish strict policy rules that evaluate ongoing projects based purely on forward-looking value rather than past capital spent.

  • Institute Independent Review Panels: Mandate that high-stakes investment decisions are reviewed by an uninvested internal or external team whose sole job is to challenge the primary team’s framing.

Who will benefit from reading Thinking, Fast and Slow the most?

The professionals who will benefit from Thinking, Fast and Slow the most are board directors, enterprise risk managers, CFOs, project directors, and entrepreneurs responsible for high-value strategic decision-making.

  • Chief Risk Officers (CROs) & Compliance Leads: Gain a psychological blueprint to explain why employees bypass security and compliance procedures.

  • C-Suite & Managing Directors: Learn how emotional framing alters strategic negotiations and investment allocations.

  • Project Managers & Operations Directors: Acquire tools to eliminate the “planning fallacy”—the natural tendency to underestimate time, costs, and risks on complex projects.

  • Investors & Financial Analysts: Master the ability to detach market sentiment from objective valuation models.

Why should you buy Thinking, Fast and Slow right now in September 2026?

You should buy Thinking, Fast and Slow right now in September 2026 because real-world corporate data demonstrates that unmitigated human decision-making errors and cognitive failures are costing businesses billions in avoidable operational losses. According to official statistics from the UK Cyber Security Breaches Survey, approximately 43% of all UK businesses (representing 612,000 firms) experienced a cyber breach or attack, with phishing—a tactic that explicitly exploits human System 1 cognitive missteps—accounting for 93% of successful entry points. Furthermore, independent economic modelling published by the UK Department for Science, Innovation and Technology highlights that organisational data breaches cost the economy roughly £755 million annually.

Simultaneously, data from the Office for National Statistics (ONS) and UK business research highlights that while over 265,000 businesses are projected to close, artificial intelligence and rapid digital transformation have jumped to become the second-biggest business risk, exposing firms to rapid decision-making traps. Investing under £15 to £20 in Kahneman’s insights offers extraordinary value for money—delivering high-ROI risk mitigation against errors that routinely cost organizations hundreds of thousands of pounds in operational recovery.

You can purchase the book directly on Amazon here: Buy Thinking, Fast and Slow on Amazon

As an Amazon Associate I earn from qualifying purchases

#BusinessRisk#CognitiveBias

Get help to protect and grow your business faster with BusinessRiskTV Business Risk Management Club

Find out more about business risk management club

Subscribe for free business risk management ideas reviews and cost of doing business reduction tips

Connect with BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos

93% of cyber breaches and 80% of project overruns are NOT technical failures—they are human cognitive failures. 🚨

If you think your C-suite makes rational strategic decisions, 499 pages of Nobel Prize–winning behavioural economics prove you are dead wrong.

Most CEOs, CFOs, and Risk Officers believe they analyse risk logically. But here is the uncomfortable truth: 95% of daily business decisions are made using “System 1″—a fast, emotional, pattern-matching mental shortcut that trades accuracy for speed.

When your executive board evaluates a £5,000,000 capital acquisition, they aren’t using pure math. They are falling victim to:

  1. Loss Aversion: Pain feels 2.0x to 2.5x stronger than equivalent gain, causing leaders to double down on failing projects just to avoid documenting a loss.

  2. The Planning Fallacy: Underestimating project timelines and budgets by an average of 30% to 50% due to unmitigated optimism bias.

  3. Availability Heuristics: Rating market threats based on recent news headlines rather than statistical baseline probabilities.

(Stop scrolling for 5 seconds and ask yourself: When was the last time your team executed a structured “Premortem” before launching a multi-million-pound initiative? If the answer is “never,” you are operating on raw intuition.) ⬇️

Here are 3 concrete protocols you can implement this week to override System 1 errors in your governance structure:

  • The 24-Month Premortem: Before signing off on any major investment, gather key stakeholders. Assume the project failed catastrophically 2 years from now. Have each director write a 5-minute report explaining why it failed. This destroys groupthink instantly.

  • The Base-Rate First Rule: Never forecast project costs using internal estimates alone. Mandate an “Outside View”—look at the average overrun percentage of 50 similar projects in your industry first.

  • Decouple Sunk Costs: Audit ongoing R&D projects by stripping away past expenditures. Evaluate future funding exclusively on forward-looking cash flows.

Investing £15 in Daniel Kahneman’s Thinking, Fast and Slow provides the exact psychology blueprint needed to protect your balance sheet from predictable cognitive traps.

Ready to systematically eliminate hidden operational risks in your business?

📩 Email editor@businessrisktv.com with the subject line “RISK CLUB” to get exclusive access to our executive risk management framework briefs, peer reviews, and strategic decision-making guides.

Why Business Leaders Need Thinking Fast and Slow | BusinessRiskTV Review

Risk Management Rebels: Better Business | BusinessRiskTV

Join BusinessRiskTV & LinkedIn Risk Management Online. Risk rebel insights for key risk owners. Manage business risks better. Email editor@businessrisktv.com.

For key risk owners and risk management rebels: use better risk questions, lateral thinking, and the Risk Management Online LinkedIn group to manage business risks better, improve business performance, and increase personal reward. Email editor@businessrisktv.com to engage.

BusinessRiskTV Business Risk Management Club recommends joining this club and Linkedin Risk Management Online group as the solution to the problem of managing business risks better to boost business performance in uncertain world.

If you are one of the crazy ones, a misfit, a risk management rebel who refuses to accept that “that’s just how it’s always been done,” then this is your invitation. Research from PwC’s 2024 Pulse Survey reveals that companies embracing advanced risk strategies have cut the financial impact of disruptions by 20% while boosting operational efficiency by 15%, and Deloitte’s 2024 Global Risk Management Survey shows that firms with robust risk governance are 25% more likely to outpace competitors in revenue growth. We are building a network of people who manage business risks better for better business performance and increased personal reward. The Linkedin Risk Management Online group is waiting for you:

https://www.linkedin.com/groups/2324725

Why Is Business Risk Management Information Critical to Better Business Decisions and Performance?

Business risk management information is critical to better business decisions and performance because organisations that invest in risk maturity consistently demonstrate improved financial performance and resilience. Enterprise risk management is not a bureaucratic checkbox exercise; it is the operating system of a business that intends to survive the Fourth Turning. ISO 31000, the international standard for risk management, explicitly states that risk management creates and protects value, contributes to the demonstrable achievement of objectives, and drives decision making that improves business performance. The World Economic Forum’s Global Risks Report 2026 emphasises that interconnected economic, environmental, geopolitical, societal, and technological risks demand a fundamental rethink of how organisations approach resilience and strategic planning, a warning echoed by the UK Government Internal Audit Agency’s guidance on early warning signs in public sector bodies.

The numbers tell a story that most boardrooms are still not hearing clearly enough:

  • Organisations with higher risk maturity levels consistently demonstrate improved financial performance.
  • A study of 11,285 firm-year observations using the COSO ERM framework found that ERM implementation is positively associated with both return on assets (ROA) and Tobin’s Q, with a stronger relationship observed for financial performance.
  • Cross-industry research reveals that supply chain disruptions can cost companies 6–10% of annual revenues, yet organisations with proactive risk management systems can significantly reduce this exposure.
  • The average cost of a single data breach is now $4.88 million, and IBM has found that companies implementing AI security tools can cut their losses by $2.2 million.
  • Organisations that fail to comply with data regulations face costs averaging $14.8 million annually, compared to just $5.4 million for those who maintain compliance.

Why does this matter for the person responsible for managing risks?

Because you are the key risk owner. You are the responsible person. When the board asks why the business is exposed, the answer starts with you. But here is the liberating truth: managing risk well is not about eliminating uncertainty. It is about navigating it with clear eyes, better information, and a network of people who have faced the same storm.

What Is the Fourth Turning Telling Us About the Problems We Face Now and in the Near Future?

The Fourth Turning is telling us that we are living through a Crisis period, a once-in-a-lifetime turning where the institutions and assumptions that stabilised the previous decades are being openly discarded. Neil Howe and William Strauss’s framework, laid out in their 1997 book The Fourth Turning, describes four generational turnings that repeat across roughly 80-to-100-year cycles: the High, the Awakening, the Unraveling, and the Crisis. According to Ben Spievak of SVRN, we are currently in the Crisis window, which he places between 2020 and 2045 — a period where markets reprice, institutions are tested, and the foundation for the next hundred years gets laid.

What does this mean for business risk management?

  • Old assumptions are breaking. The rules of the game are being rewritten. What worked in the Unraveling — efficiency, optimisation, predictable supply chains — may not work in the Crisis.
  • Institutional trust is fragile. As one analysis of The Fourth Turning puts it, “History warns that a Crisis will reshape the basic social and economic environment that you now take for granted”.
  • Volatility is not noise; it is signal. In the Fourth Turning framework, what looks like instability is often the market finding a new price, a recalibration around what value means in a world operating on a different set of assumptions.
  • Crisis is an incubator. A crisis period is not the end of anything — it is the phase where the decisions made today carry outsized weight for the next century.

This is the context in which you, as a risk owner, must make decisions. Not with perfect foresight — that has never existed — but with a framework that helps you distinguish between preventable risks, strategic risks, and external risks. Harvard’s Kaplan and Mikes framework, cited in strategic risk analysis, offers exactly this practical approach: turn preventable risks into advantages, use strategic risks to open new markets, and build resilience against external risks you cannot control.

The danger is not just the things we don’t know. It is the things we think we know for sure.

Why Do Risk Management Rebels, Misfits, and Crazy Ones Need to Step Forward Now?

Risk management rebels, misfits, and crazy ones need to step forward now because the conventional risk management playbook — the one built for a stable, predictable world — is failing in the Crisis. Research on “positive deviants” in organisations shows that rebels with a cause often spark the innovations that established paradigms cannot produce, and that suppressing these individuals backfires because people judge proposed innovations on whether they agree with the established paradigm rather than their ability to create new paradigms. A study of NASA’s mission control renegades found that rebels create novel solutions, revitalise innovation, and future-proof businesses.

Why do we need you specifically?

  • Because the old model of risk management is defensive. It treats risk as an enemy to avoid rather than a force to wield. PwC’s 2023 CEO Survey reveals that 56% of CEOs believe taking risks is essential for growth, yet many frameworks are still designed to mitigate exposure rather than capitalise on opportunities.
  • Because only 26% of executives believe their risk management aligns with business strategy, according to Deloitte’s 2023 Global Risk Management Survey. That gap is not a statistic. It is an opportunity.
  • Because lateral thinking is the only way through. The problems we face — geopolitical fragmentation, technological disruption, climate instability, supply chain fragility — do not have precedents. They require innovative solutions, and innovation requires making some mistakes. That is not a flaw in the process. It is the process of improvement.
  • Because uncertainty is not a problem to be solved. It is the condition of being alive or in business. Alan Watts wrote that “the desire for security and the feeling of insecurity are the same thing. To hold your breath is to lose your breath”. The tighter you grip the need to know exactly how everything will turn out, the more anxious you become. The looser you hold it, the more spacious your business decisions feel.

You do not need to know how the story ends to enjoy the chapter you are in with your business. Let yourself be a beginner. Let yourself not have all the answers. Let yourself be in the process of finding the right answers for your business.

What Can Members of BusinessRiskTV and the Risk Management Online Group Expect from Membership?

Members of BusinessRiskTV and the Risk Management Online group can expect a practitioner-driven community where real risk owners share frameworks, warnings, and wins without the corporate jargon that hides more than it reveals. This is not a passive content feed. It is a working network.

What you can expect:

  • A community of people who think differently. We are not looking for consensus. We are looking for the people who ask the uncomfortable question in the meeting, the ones who see the risk nobody else has noticed yet.
  • Practical risk intelligence. Discussions on emerging risks, regulatory changes, geopolitical shifts, and technological disruptions that affect your business decisions.
  • Peer-to-peer support. When you are the responsible person and the board is asking questions you are not sure how to answer, this is where you find people who have been there.
  • Frameworks that work. From ISO 31000 to COSO ERM to Kaplan and Mikes’s risk categories, we share the tools that actually help you make better decisions, not just fill in a risk register.
  • A space to test your thinking. Before you take a controversial risk decision to your executive team, test it here. The misfits and rebels in this network will tell you what you are not seeing.

What we are not:

  • A sales channel.
  • A compliance checkbox.
  • A place for people who want to be told what to do.

Who Is Most Likely to Benefit from Membership, and When?

The people most likely to benefit from membership are the key risk owners, responsible persons, business owners, risk managers, compliance officers, executives, and consultants who are accountable for outcomes and who feel the weight of uncertainty pressing on their decisions right now. You benefit most when you are at an inflection point — when a major decision is in front of you, when a crisis has just hit, when the board has asked you a question you cannot answer alone, or when you sense that the ground beneath your business is shifting but you cannot yet see the shape of what comes next.

You are likely to benefit the most if you are:

  • A business owner or founder who carries the full weight of risk without a large risk function behind you.
  • A risk manager or compliance officer who knows the frameworks but needs strategic context to make them real.
  • An executive or director who is accountable for decisions in a Fourth Turning environment and needs better information.
  • A consultant or advisor who helps organisations navigate uncertainty and wants to sharpen your own thinking alongside practitioners.
  • Anyone who has ever been called “difficult” or “negative” for pointing out the risk nobody else wanted to see.

When do you benefit?

Immediately. The moment you join, you gain access to a network that is already discussing the problems you are facing. You do not need to wait for a conference, a training programme, or a quarterly report. The benefit begins with the first conversation you read, the first question you ask, the first connection you make.

Why Should Someone Responsible for Managing Business Risks Join This Network to Inform Their Own Business Decision Making as a Key Risk Owner?

Someone responsible for managing business risks should join this network because no single risk owner, however experienced, can see every angle of every threat and opportunity, and the Fourth Turning demands collective intelligence. The Harvard Business Review has repeatedly found that diverse teams make better decisions, and the same principle applies to risk networks: the person who has managed a supply chain crisis in Southeast Asia may hold the key to your procurement problem in Europe.

But here is the reason we most want you to hear:

  1. You are the key risk owner. The decision is yours to make. But you do not have to make it alone.
  2. Deloitte’s survey highlighted that companies with a proactive GRC approach were 50% more likely to maintain their reputation during crises, and PwC found that organisations with effective GRC strategies saw a 50% reduction in the frequency of risk events. Those outcomes are not the product of better software alone. They are the product of better conversations between people who take risk seriously.

What can you expect from the network?

  • Access to a global community of practitioners who bring perspectives from different industries, cultures, and regulatory environments.
  • Real-time discussion of emerging risks as they develop, not after the post-mortem.
  • A place to ask the question you cannot ask in your own organisation without signalling weakness or uncertainty.
  • Frameworks and mental models that help you structure your thinking when the data is incomplete.
  • The reminder that uncertainty is the condition of being in business, and that navigating it with curiosity rather than fear is not just possible — it is the most rewarding way to work.

How Can You Engage with BusinessRiskTV and the Risk Management Online Group for Your Own Benefit?

You can engage with BusinessRiskTV and the Risk Management Online group by joining the LinkedIn community, introducing yourself honestly, and participating in the conversations that matter to your business. You can be anywhere in the world and still benefit from membership because the network is distributed, asynchronous, and built for practitioners who are already busy managing real risks.

How to engage for your own benefit:

  • Join the LinkedIn group: https://www.linkedin.com/groups/2324725
  • Introduce yourself with a real problem. Do not sell. Do not posture. Tell the group what you are facing and what you need.
  • Answer someone else’s question. The fastest way to sharpen your own risk thinking is to help someone else structure theirs.
  • Bring your misfit perspective. If you see something the group has not noticed, say it. That is why you are here.
  • Stay curious. The Fourth Turning is not a doom prophecy. It is a framework for understanding the times we are in, and frameworks are only useful if they are used.
  • Share what you are learning. Your failures are as valuable as your wins. The network grows stronger when we are honest about both.

The invitation is simple:

We are looking for the crazy ones, the misfits, the risk management rebels. The people who understand that certainty is a story we tell ourselves and that real security comes from the capacity to adapt, not the illusion of control. If that sounds like you, join us.

Join BusinessRiskTV Business Risk Management Club. Join the Risk Management Online LinkedIn group. Manage business risks better for better business performance and increased personal reward.

The story is still being written. You do not need to know how it ends to be part of the chapter that matters. Join Business Risk Management Club here or join the LinkedIn group:

https://www.linkedin.com/groups/2324725

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with less uncertainty with BusinessRiskTV 

Subscribe for free business risk management ideas risk reviews and cost of being in business reduction tips

Connect with BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos

Risk Rebels: Manage Business Risks Better | BusinessRiskTV

UK Bankruptcy Crisis 2026: Why Debt Maturity, Private Credit Fears & Tariffs Are Killing Businesses (12 Steps to Survive)

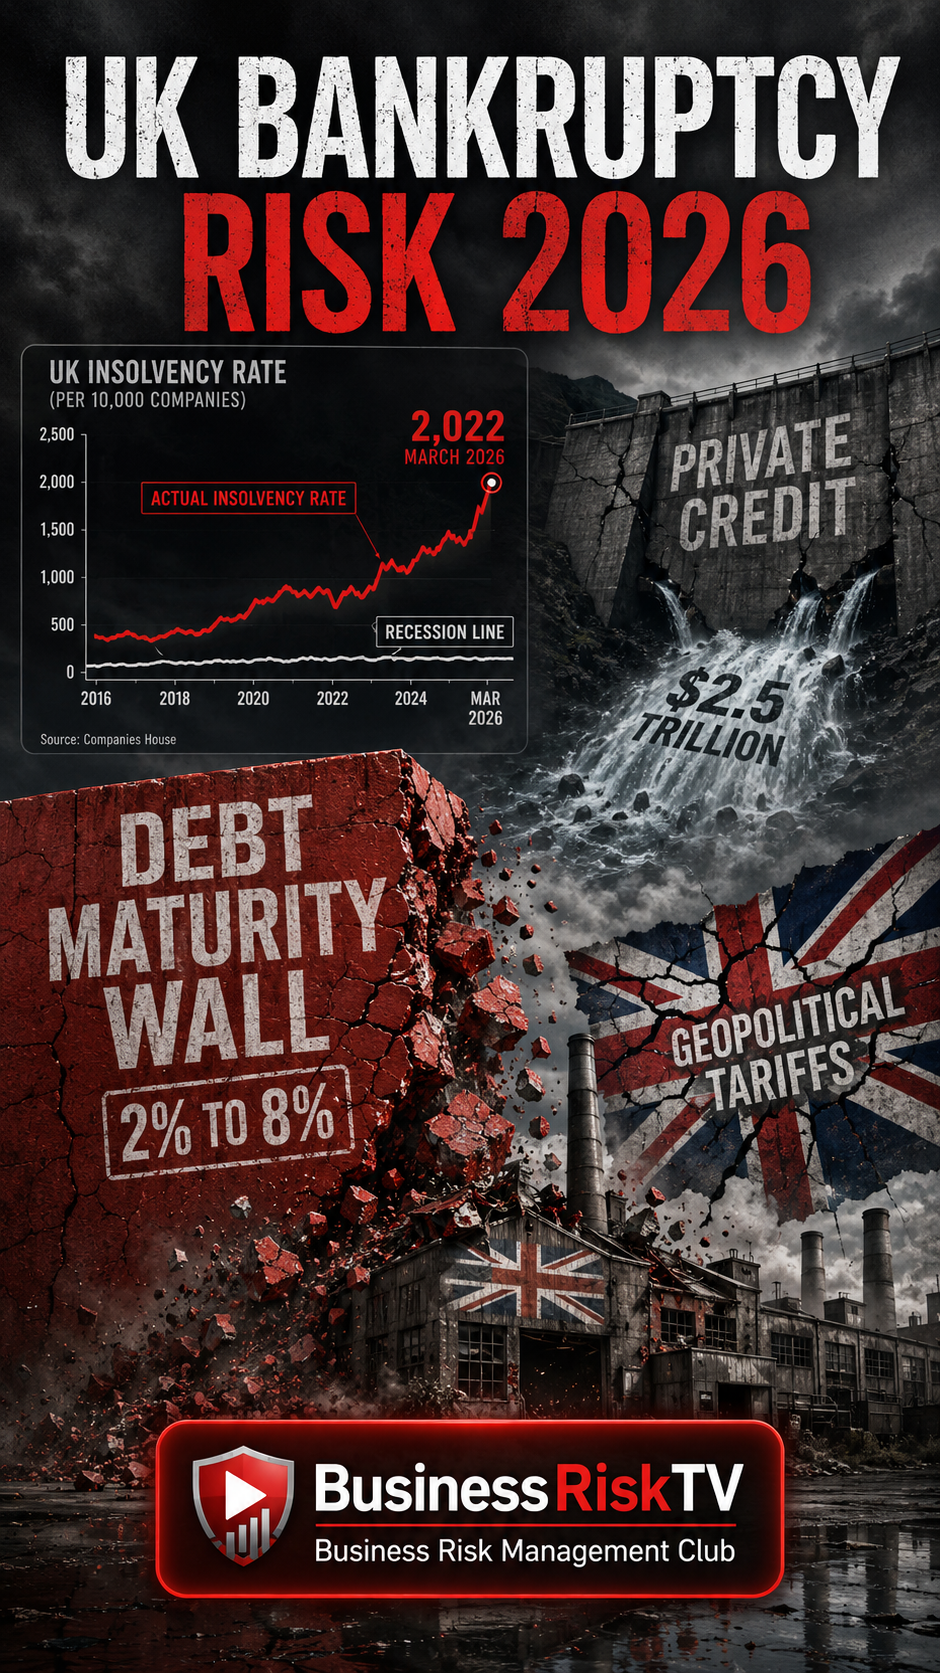
In 2026, UK business insolvencies are near 30-year highs. With 2,022 companies folding in March alone, leaders face a triple threat: maturing debt at 8% rates, a looming private credit crash warned of by the Bank of England, and geopolitical tariff shocks. This guide reveals 12 risk management steps to stop your business going bankrupt, including refinancing strategies, HMRC defence tactics, and supply chain shifts to survive the 2026 liquidity crunch.

Stop guessing about bankruptcy. Join the Business Risk Management Club today.

The average cost of a mid-sized company insolvency is £90,000 in director losses. The cost of our club membership? Less than a cup of coffee a day.

3 Facts to Back Up Our Value:

1. Cost: We charge £49.99 per month for full access (introductory deals available for limited time). An insolvency practitioner charges £350+ per hour.
2. Speed: Members get 24/7 access to alternative risk reviews. Banks and risk analysts take  weeks.
3. Certainty: We provide real-time geopolitical risks; majority of failed businesses didn’t see the shock coming before too late.

—

Why Should UK Business Leaders Be Worried About Bankruptcy in 2026? (The “Triple Lock” Crisis)
Why UK business leaders should be worried about bankruptcy in 2026 because insolvencies are currently near a 30-year high due to a “triple lock” of debt maturity cliffs, geopolitical trade wars and geopolitical risks, and a hidden private credit crash.

We are not in a normal recession; we are in a debt maturity trap. In March 2026 alone, England and Wales recorded 2,022 company insolvencies, matching the peak levels of the 2008 financial crisis . For a 10-year-old: Imagine borrowing a toy for a week, but when you try to return it, the shop says you now owe 10 times the price, and your pocket money just got cut because your friends are fighting far away. That is 2026.

Are Maturing Debt Instruments the #1 Cause of UK Business Bankruptcies Right Now?

Yes, maturing debt instruments taken out at 2% that are maturing at 8% rates are the single biggest driver of cash flow collapse in the UK in 2026 because refinancing has dried up for the mid-market.

UK borrowing costs hit their highest levels since 1998 recently, with 30-year gilt yields hitting 5.78% . For a 10-year-old: You borrowed £1 to buy lemonade supplies, promising to pay back £1.02. Now, the bank says you must pay back £1.15. If you don’t have that extra 13p, your lemonade stand is gone.

How Do Geopolitical Changes and Tariffs in 2026 Hurt My UK Supply Chain?

Geopolitical changes in 2026, specifically the Iran conflict and the UK-US trade deal delays, are forcing costs up by up to 20% for importers, strangling margins just as debts come due.

The UK just signed a $5 billion Gulf trade deal to bypass Iran war fallout, but the US remains rocky . UK Parliament admits the US deal is “not yet delivering growth” as tariffs fragment the global system . For a 10-year-old: Your favourite toy is made across the street. If the street gets blocked by a fight, you have to fly a helicopter to get the toy. That helicopter costs more than the toy.

Is the “Private Credit” Market Really Drying Up for UK Businesses in 2026?
The threat of credit drying up is real because the Bank of England has warned that the $2.5 trillion private credit market has “echoes of the Great Financial Crisis” and has never been tested at this scale.

Deputy Governor Sarah Breeden explicitly stated that a “private credit crunch” is coming where funds are “gated” (locked) . The House of Lords reports that SME finance has been “squeezed” because banks retreated after 2008 and private credit is now freezing . For a 10-year-old: You usually borrow money from a rich friend. But that friend is suddenly broke and hiding under their bed. Now nobody will lend you the money to buy your lunch.

Are These the Most Common Causes of Bankruptcy in the UK Right Now (2026 Stats)?

Yes, these are the most common causes, but rising employment costs and HMRC aggression are the “silent killers” pushing the UK toward the highest bankruptcy rate in 20 years.

In 2025, an estimated 288,018 UK businesses failed (roughly 5% of all firms) . The construction sector accounts for 17% of all insolvencies due to material costs, while retail is collapsing due to wage bills . The UK is seeing the highest rate of bankruptcies since the early 1990s, driven not just by debt, but by the Employment Rights Act 2025 which doubles redundancy costs .

—

🛡️ 12 Business Risk Management Steps UK Business Leaders Should Take Today

To avoid joining the 2,000+ companies failing monthly, execute these steps immediately:

1. Refinance NOW, not later.
· Action: Approach challenger banks (e.g., Shawbrook, OakNorth) before your current loan matures. Lending growth has slowed to 4.5%, get in the queue now .
2. Stress test for 10% Interest Rates.
· Action: Model your cash flow assuming base rates hit 8%. If you break, cut costs today.
3. Audit your “Phantom Stock”.
· Action: Check supplier contracts for geopolitical escalation clauses. If they aren’t there, add them for the Iran/Gulf fallout .
4. Diversify away from US supply chains.
· Action: Shift 30% of sourcing to the new GCC trade deal partners (UAE, Saudi) to bypass US tariffs .
5. Invoice factoring for immediate cash.
· Action: Sell your unpaid invoices. With credit drying up, cash in hand is king.
6. The “Credit Committee” meeting.
· Action: Hold a weekly 15-minute meeting to check if your customers have issued winding-up petitions. Don’t sell to companies about to go bust .
7. Prepare for Employment Rights Act 2025.
· Action: Set aside a specific fund for “protective awards” (now 180 days pay) before making redundancies .
8. HMRC negotiation strategy.
· Action: HMRC is taking aggressive debt action. Do not ignore their letters; agree on a Time to Pay arrangement before they file a winding-up petition.
9. Invest in Internal Controls (Governance).
· Action: Under the new UK Corporate Governance Code (Jan 1 2026), directors are personally liable for “material weaknesses” in financial controls .
10. Explore a CVA before it’s too late.
· Action: Company Voluntary Arrangements (CVAs) are up 29% year-on-year. Use them to bind creditors to a reduced payment plan before you run out of cash .
11. Cancel the “Golden Quarter” overspend.
· Action: Consumer spending is dropping . Do not stockpile inventory unless it is paid for.
12. Join an Early Warning System.
· Action: Use data providers to see if your bank is increasing “expected credit losses” (like HSBC did with $1.3bn) – this means they will stop lending to you .

Get help to protect and grow your business faster regardless of business environment with help from Business Risk Management Club

Find out more about business risk management club

Subscribe for free business risk alerts risk reviews and cost of business in business reduction tips

Connect with BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos

#UKBankruptcy2026 #BusinessRiskManagement #PrivateCreditCrunch #BusinessRiskTV #RiskManagement

Additional Tags: UK Insolvency Statistics 2026, Maturing Debt Risk, Private Credit Market UK, Bank of England Warning 2026, Geopolitical Tariffs UK, Supply Chain Disruption, Business Risk Management Steps, Avoid Bankruptcy UK, UK Interest Rates 2026, Corporate Governance Code 2026.

⚠️ Important Legal Notice:
I am not a licensed insolvency practitioner or financial advisor. The above information is for educational purposes based on current data trends. For specific legal or financial advice regarding your business, you must consult a qualified professional like those found via the BusinessRiskTV.com network.

UK Bankruptcy Crisis 2026: Why Debt Maturity, Private Credit Fears & Tariffs Are Killing Businesses (12 Steps to Survive)

UK North Sea Self-Sufficiency: A Risk Analysis for Winter 2026 Costs

Can the UK drill its way to lower energy costs by 2026? We analyze new data on untapped reserves and the 6 policy steps needed to protect UK businesses from the 2026 energy crisis.
Can North Sea “Self-Sufficiency” Save UK Businesses by Winter 2026?
The debate over UK energy has shifted from “if” we should drill to “how fast” we can unlock existing discoveries. With new data from the Business Risk Management Club and industry analysts, we examine if a policy U-turn can insulate the UK from the global energy crisis by the end of 2026.

At BusinessRiskTV, we advocate for evidence-based risk management. To back up our claim on the value of domestic energy security:


Could “Self-Sufficiency” become a reality by 2026?
Self-sufficiency is mathematically possible if the UK government accelerates the 111 pending projects identified by OEUK, which represent £50 billion in potential investment. While reaching 100% independence by Winter 2026 is an ambitious “stretch goal,” moving the needle from 43% domestic supply to over 60% would significantly decouple the UK from the most volatile global “spot price” spikes.

“Untapped UK domestic gas reserves are double previous government estimates; for as long as the nation requires gas, it is in the national interest to produce it at home to ensure industrial security.” — Offshore Energies UK, February 2026 Report

Will new licenses actually lower business energy costs by Winter 2026?
New licenses and the activation of discovered sites like Rosebank and Jackdaw can lower business costs by providing the government with the fiscal “Energy Dividend” needed to freeze commercial price caps. While the “unit price” of gas is global, the Energy Profits Levy (EPL) and the new 2026 Oil and Gas Price Mechanism allow the Treasury to capture windfall gains and recycle them directly into VAT cuts for business energy.

  • Statistical Reality: In 2025, the UK paid an estimated £22 billion more for energy than it would have if it had maintained 2014 levels of domestic production.

  • The “Price Taker” Myth: While we are price takers, the £50 billion in potential tax revenue from new drilling could theoretically fund a 30% reduction in business energy standing charges if policy shifts today.

Can a policy change today realistically impact the 2026/2027 Winter?
A policy change today can impact Winter 2026/2027 by focusing on “Tie-Backs” and “Transitional Energy Certificates,” which allow production to start in months rather than years. By utilising existing infrastructure, the UK can “hook up” discovered but capped wells. This avoids the 10-year lead time of new exploration and provides an immediate supply cushion for the upcoming 2026 crisis.


Conclusion: 6 Steps the UK Government Needs to Take Today

To make this policy shift work by the end of 2026, the Government must execute these steps immediately:

  1. Activate “Transitional Energy Certificates”: Grant immediate approval for all “near-field” tie-backs where gas is already discovered and infrastructure is in place.

  2. Replace EPL with a Fixed Price Floor: Move from the volatile Windfall Tax to a Permanent Price Mechanismto give operators the 10-year certainty required to dump capital into the North Sea now.

  3. Streamline Environmental Impact Assessments (EIAs): Implement a “Fast-Track” regulatory lane for projects that can be operational by October 2026.

  4. Ring-fence the “Drilling Dividend”: Legally mandate that 100% of new tax receipts from these licenses are used to offset business energy network costs for the 2026/2027 winter.

  5. End the New Licensing Ban: Formally reverse the November 2025 ban to signal to global capital markets that the UK is “open for energy business.”

  6. Direct-to-Industry Contracts: Facilitate “Power Purchase Agreements” (PPAs) between North Sea producers and UK energy-intensive industries to bypass global market markups.

#EnergyIndependence #NorthSeaGas #UKBusiness2026 #BusinessRiskTV #RiskManagement

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster through any business environment with BusinessRiskTV 

Subscribe for free business risk management ideas risk reviews and cost reduction tips

Connect With BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and Risk Business for free videos

They told you the North Sea was “running on empty.” They lied! 🛑🛢️

New 2026 data reveals the UK is sitting on 456 billion cubic metres of untapped gas. That’s 6 YEARS of total self-sufficiency—so why are your business energy bills still sky-high?

We’ve been told for years that new drilling takes “decades” to help. But the risk analysts at BusinessRiskTV just pulled the curtain back.

If the government acts TODAY, “Tie-Back” technology can have new domestic gas flowing into the grid before the snow hits in Winter 2026.

Here is the 2026 Energy Paradox:
🔹 We have the gas.
🔹 We have the infrastructure.
🔹 We have the business need.
…Yet we are importing 4-times more carbon-intensive LNG from overseas at premium prices.

This isn’t just an environmental issue; it’s a Business Risk Management failure. By refusing to unlock our own reserves, we are choosing to export UK wealth to foreign regimes while our own SMEs struggle to keep the lights on.

The “Drilling Dividend” could fund a massive relief package for every UK business—but only if the policy shift happens before the end of the year.

Think the UK is a “price taker” with no control? Wait until you see Step 6 of our survival plan. It reveals how we can bypass global market markups entirely to save UK industry.

Don’t let your business be a victim of policy gridlock. Get the full 2026 Risk Analysis now.

#EnergyIndependence #NorthSeaGas #UKBusiness2026 #BusinessRiskTV #RiskManagement

UK North Sea Self-Sufficiency: A Risk Analysis for Winter 2026 Costs

The 2026 Silver Crisis: COMEX Default Risk, China Export Ban & 9 Strategies for Business Leaders

As the March 2026 COMEX silver交割 approaches, global business leaders face a critical liquidity event. Combined with China’s export ban on silver and surging industrial demand, the risk of a physical silver default threatens to disrupt financial markets and supply chains. Discover 9 risk management measures to protect your business.

Undertaking a Business Risk Analysis of the COMEX Silver Supply Crisis of March 2026

For business leaders around the world, the convergence of three distinct market forces has created a “perfect storm” in the silver market. Unlike previous commodity cycles driven by speculation, the current crisis is structural. It is defined by the shutdown of accessible physical silver from traditional channels, a strategic shift in Chinese trade policy, and an insatiable, non-negotiable industrial demand.

This analysis serves as a business risk management framework to understand the threat, timeline, and strategic responses required to navigate the potential financial contagion stemming from the COMEX market in March 2026.

The Core Problem: The Triad of Risk in 2026

To understand why this is not a typical price fluctuation, business leaders must dissect the three pillars of the current crisis.

1. The COMEX Delivery Crisis and March 2026 Risk Event

The most immediate and systemic threat lies within the New York Commodities Exchange (COMEX). Historically, the COMEX is a “paper” market, where futures contracts are settled financially far more often than with physical metal. However, data from January 2026 reveals a seismic shift. In a traditionally quiet month, over 40 million ounces of silver were requested for delivery, compared to the usual 1-2 million ounces .

Analysts warn that as the critical March delivery month approaches, total delivery requests could reach 70 to 80 million ounces. This would nearly deplete the COMEX registered inventory of just 110 to 120 million ounces . The major risk event is a default by the COMEX on physical delivery. This would shatter the credibility of the paper pricing mechanism, leading to a violent repricing of silver and a flight to quality that could freeze credit markets .

2. China’s Strategic Embargo on Silver Exports

Effective January 1, 2026, China implemented stringent export controls on silver, licensing only 44 companies to export and effectively treating the metal with the same strategic importance as rare earths . China is not just a major producer; it accounts for roughly 70% of the globally traded refined silver market .

This “ban” creates a supply vacuum. While the West views silver as a commodity, China views it as a strategic resource critical for its dominance in solar panels, EVs, and AI infrastructure . This action effectively diverts physical supply away from Western markets and locks it into Chinese industrial expansion. Elon Musk’s public response—”This is not good”—underscores the critical nature of this disruption for US and European supply chains .

3. The Industrial Demand “Trap”

Silver is no longer just a precious metal; it is the “industrial vitamin.” It is indispensable for solar panels, electric vehicles, AI data centres, and 5G infrastructure . The market is heading for its sixth consecutive year of structural deficit .

Unlike investors who can leave the market, industrial consumers cannot stop buying. They must have physical silver to keep production lines running. This creates a demand inelasticity that fuels a scramble for physical metal. Even if high prices eventually cause some “thrifting” (using less silver) in sectors like solar, the immediate demand pipeline is rigid .

The Risk: Shutdown of Access to Physical Silver

The shutdown of access is happening on two fronts simultaneously.

  • Price Discovery Failure: If COMEX defaults in March, the “paper” price (used by banks and funds for valuation) will become detached from the physical price (what manufacturers actually pay). We are already seeing this bifurcation, with physical coins trading at 50-80% premiums in some markets.
  • Liquidity Freeze: Banks and financial institutions that lend against silver or use it as collateral will face a crisis of valuation. If they cannot reliably price or obtain physical metal to cover positions, they will pull credit lines from the very industries that need it most .

Why This is Critical to Business Leaders and Financial Markets

The contagion from a silver default will not stay contained within the commodities desk. It will spread to the wider financial markets. A default at COMEX would trigger margin calls across the complex, forcing liquidations of other assets to raise cash. It would undermine confidence in all paper commodity markets, potentially leading to a credit crunch .

For business leaders, this translates to:

  1. Input Cost Volatility: Unpredictable and rising costs for any product using electronics, batteries, or solder.
  2. Supply Chain Unreliability: Suppliers may simply stop quoting prices or fail to deliver on contracts due to an inability to source metal.
  3. Working Capital Strain: As seen in India’s “Silver City” of Khamgaon, manufacturers face acute shortages, forcing them to lock up disproportionate working capital in buffer inventories or face shutdowns .

When Will the Major Risk Event Happen?

The primary date for concern is March 2026. The COMEX March contract is a major delivery month. As the delivery date approaches in late February and early March, the pressure on holders of short positions (those who sold silver they don’t physically have) will become intense. If they cannot source the metal, the exchange faces a default scenario . Business leaders should be prepared for extreme volatility beginning in the last week of February and peaking in mid-March.

Who is Most Likely to Be Affected by Risk Events?

While the impact is broad, certain sectors are on the front line:

Where in the World Will Have the Biggest Business Risk Impacts?

  • North America and Europe: These economies are heavily dependent on imports of refined silver and are most exposed to the COMEX default risk and the cutoff of Chinese supply.
  • India: As a major importer of silver for both jewellery and industry, India is experiencing severe price sensitivity and liquidity stress in its processing hubs.
  • Asia (ex-China): Economies reliant on Chinese refined silver will face logistical delays and higher costs as they scramble to diversify suppliers .

9 Business Risk Management Measures to Take Today

To protect and grow your business through the coming volatility, leaders must move from passive observation to active defense.

Measure 1: Audit Your Silver Supply Chain Deeply
Map your supply chain beyond Tier 1.

Identify where silver is embedded in components and which of your suppliers are exposed to spot markets. You need to know if your key supplier is one of the 44 licensed Chinese exporters or if they rely on COMEX paper.

Measure 2: Secure Supply-Linked Financing

Move away from spot purchases. Secure long-term supply arrangements directly with producers or through offtake agreements. As seen with Samsung and Silver Storm Mining, tying working capital to contracted silver flows provides price and supply visibility .

Measure 3: Build Strategic Buffer Inventories

In a deficit market, just-in-time inventory is a high-risk strategy. Increase your buffer stocks of silver-intensive components now, even if it strains working capital. The cost of holding inventory is lower than the cost of a production shutdown.

Measure 4: Hedge Physically, Not Just Financially

Traditional paper hedging may fail if the paper price decouples from physical reality. Explore options that give you a claim on physical metal or consider purchasing allocated physical silver to secure future needs.

Measure 5: Diversify Your Supplier Base

With China restricting exports, immediately qualify suppliers in Mexico, Peru, and Australia. Redundancy in your supply chain is now a survival trait, not a cost center .

Measure 6: Implement Price Escalation Clauses

Review all fixed-price contracts for silver-intensive goods. Insert price escalation clauses that allow you to pass through raw material cost increases, protecting your margins from volatility.

Measure 7: Stress-Test Working Capital

Model a scenario where silver prices spike another 30-50% and payment terms from suppliers shorten to cash-on-delivery. Identify where liquidity stress would appear in your business and secure backup credit lines now .

Measure 8: Explore Substitution and “Thrifting”

Work with your R&D and engineering teams to accelerate plans for silver reduction. While substitution (like copper for silver) takes time, even marginal reductions in usage per unit can significantly lower risk exposure .

Measure 9: Monitor Lease Rates and Premia

Ignore the spot price for a moment. Track the LBMA silver lease rates and physical premiums in key markets like Dubai or Shanghai. These are the real indicators of physical tightness. A spike in lease rates, as seen recently, signals that the physical market is screaming for metal .

How Do Business Leaders Continue to Grow Faster Regardless of Such Risk Events?

Volatility creates opportunity. Leaders who navigate this crisis effectively can gain market share against competitors who freeze or fail.

  1. Capitalise on Competitor Weakness: While rivals struggle with supply chain disruptions, your secured supply chain (via Measure 1 & 2) allows you to win contracts and capture market share.
  2. Innovate Through Constraint: Use the high price environment to justify investment in R&D for more efficient silver usage. The companies that solve the “thrifting” equation first will have a long-term cost advantage.
  3. Leverage Financial Innovation: Utilise supply chain finance platforms and offtake agreements to turn a liability (high silver cost) into a competitive advantage (guaranteed supply). By treating finance as part of the supply chain, you build resilience that debt-heavy competitors lack .

Conclusion

The March 2026 COMEX delivery is not just a trader’s problem; it is a critical business risk event. The combination of a potential default, Chinese export controls, and a multi-year structural deficit means the rules have changed. Business leaders must act today—not to speculate, but to insulate. By securing physical supply, strengthening working capital, and diversifying sources, you can protect your enterprise from the coming storm and emerge stronger on the other side.

#SilverCrisis #COMEXDefault #BusinessRiskManagement #BusinessRiskTV #RiskManagement

Get help to protect and grow your business through any business risk events with support from BusinessRiskTV

Find out more about managing business risks with BusinessRiskTV help

Subscribe to BusinessRiskTV for free business risk management ideas risk reviews and cost reduction tips

Connect with us for free business risk management tips

Read more business risk management articles and view videos for free

Connect with us for free alerts to new business risk management articles and videos

The 2026 Silver Crisis: COMEX Default Risk, China Export Ban & 9 Strategies for Business Leaders

Trillion-Dollar USA Stimulus: Tax Refund & Repatriation Tsunami – A Business Risk Analysis for Global Leaders

The US economy is entering a period of significant fiscal stimulus, driven by approximately $220 billion in tax refunds from the “One Big Beautiful Bill Act” and the mass repatriation of trillions in offshore corporate cash. For global business leaders, this is not just an American event; it is a global capital shock. This risk analysis on BusinessRiskTV.com breaks down the composition of this liquidity wave, why it demands immediate strategic attention to protect and grow market share, and the critical timeline for when these benefits will hit the real economy.

The opening months of 2026 have confirmed a pivotal shift in the global economic landscape. The United States is experiencing a confluence of fiscal catalysts that are pumping hundreds of billions of dollars into the economy, with the potential to unlock trillions more in the near future. For business leaders around the world, this “Trillion-Dollar Tsunami” of liquidity presents a dual-edged sword: a massive opportunity for growth and a significant risk for those caught off guard.

This risk analysis on BusinessRiskTV.com examines the composition of this capital wave, explains why it is critical for non-US and US-based leaders to act now, identifies who will benefit most, and provides a strategic timeline for when these effects will materialise.

The Anatomy of the Stimulus: What Does the Money Consist Of?

To manage the risk and reward, we must first dissect the capital flows. The current injection is not a single stimulus check, but a multi-layered financial event rooted in tax policy and corporate finance.

1. The Personal Tax Refund Windfall ($220 Billion)

The primary driver of immediate liquidity is the “One Big Beautiful Bill Act” (OBBBA) , passed in July 2025. This legislation made several tax cuts retroactive to the beginning of 2025 . Because the IRS did not adjust withholding tables until 2026, most taxpayers did not see this money in their paychecks last year. Instead, they are receiving it now as a lump-sum refund .

  • The Numbers: Wells Fargo estimates the total reduction in household income taxes for 2026 from these new provisions will be roughly $220 billion (0.7% of GDP) . Of this, approximately $80 billion to $100 billion will hit bank accounts specifically as tax refunds between February and April 2026 . The average refund is projected to rise by 18% to roughly $3,750, with some estimates suggesting it could go as high as $3,800.
  • The Source: The money comes from new or expanded deductions, including the “no tax on tips,” “no tax on overtime,” an enhanced child tax credit (up to $2,200), and a new $6,000 bonus deduction for seniors .

2. The Corporate Repatriation Trigger (Trillions in Waiting)

While the refunds provide immediate juice, the long-term fuel is corporate repatriation. The permanent extension of the 2017 Tax Cuts and Jobs Act (TCJA) provisions provides “certainty and stability” for corporate tax planning . This certainty is the key that unlocks the estimated $2 trillion to $4 trillion in profits that US multinationals are holding overseas.

With tax rates permanently lower and a territorial tax system solidified, the financial incentive to keep cash abroad diminishes. We are already seeing the mechanics of this in global markets. For example, data from emerging markets shows foreign investors repatriating profits at significantly higher rates (e.g., a 27% YoY increase in outflows from one South Asian market), as global capital flows readjust to the new US tax reality .

Why This Matters Now: Protecting and Growing Your Business Faster

For global business leaders, this US liquidity event creates a volatile landscape of risk and opportunity. Ignoring it means allowing competitors to capture market share using cheaper capital.

The “K-Shape” Risk: Uneven Distribution of Wealth

Bank of America analysts warn that this stimulus will likely exacerbate the “K-shaped” economy, where the wealthy accelerate while the middle class slows .

  • Higher-Income Beneficiaries: Changes to the SALT (State and Local Tax) deduction cap and investment tax breaks disproportionately favour higher earners.
  • Lower-Income Lifeline: For lower-income households, tax refunds represent a massive percentage of their annual disposable income. Historically, these households spend this money immediately.
  • The Action: Businesses must segment their customer base. Luxury goods and financial services may see a surge in investment activity, while consumer staples and retail must prepare for a spike in volume from lower-income brackets who are “splurging” on deferred “nice-to-have” items .

The Consumption vs. Investment Divide

Approximately half of the new stimulus from higher earners is expected to flow into the stock market rather than the retail economy. This presents a risk for B2C companies expecting a broad-based sales boom, but an opportunity for B2B service providers, M&A advisors, and wealth managers.

Global Capital Drain

For businesses operating outside the US, this is a major risk factor. The “pull” of the US market—fueled by these tax cuts and permanent repatriation allowances—sucks liquidity out of other markets . Non-US firms may face tighter credit conditions at home as domestic investors chase higher yields or safer returns in the US.

Strategic Preparations: What Business Leaders Should Do Now

With the filing season opening on January 26 and refunds flowing immediately, leaders are already in the “execution window” . Here is your risk management checklist.

For CEOs and Strategists:

  • Scenario Planning: Model for a “liquidity surge” in H1 2026. Assume that consumer spending will get a 0.3% boost to GDP, which has already been factored into bullish forecasts by major financial institutions.
  • Competitive Intelligence: Monitor which competitors now have access to repatriated cash piles. They will likely use this liquidity for aggressive M&A, R&D investment (leveraging new credits), or price wars .

For CFOs and Finance Teams:

  • Capital Structure Optimisation: If you are a US multinational, review your cash management strategies. The penalty for keeping cash overseas has diminished. Repatriate strategically to fund share buybacks or reduce debt, but beware of the market timing.
  • Supply Chain Financing: The injection of cash into small and medium-sized enterprises (SMEs) via refunds may improve the financial health of key suppliers. Review supplier credit terms to capitalise on their improved liquidity.

For Marketing and Sales Leaders:

  • Adjust Withholding Assumptions: The “no tax on tips and overtime” rules will leave specific sectors (hospitality, personal services) with significantly more take-home pay. Target these sectors with tailored messaging immediately.
  • Wealth Segmentation: Recognise the “K-shape.” High-end retailers should market to the investor class benefiting from capital gains treatment, while value brands should target the disposable income spike from the expanded Earned Income Tax Credit and Child Tax Credit .

Who Will Benefit Most and When?

Understanding the timing of these benefits is crucial for risk mitigation and resource allocation.

The Immediate Winners (Q1-Q2 2026)

  • Tax Preparation & Fintech: Companies like Impress Tax Service and AmeriFile are already seeing a surge as individuals scramble to maximise complex new deductions.
  • Discretionary Retail & Travel: Low-to-middle income households historically increase spending on goods, travel, and leisure by nearly 40% in the weeks following receipt of a refund . This wave is hitting now.
  • Debt Management: Firms offering debt consolidation services will benefit as lower-income households use refunds to pay down liabilities .

The Medium-Term Winners (H2 2026 – 2027)

  • M&A Advisory and Investment Banking: The “certainty” of permanent tax cuts, combined with the repatriation of corporate cash, will fuel deal-making. However, note that new tax rules in some jurisdictions are tightening interest deductions and MAT credits, which will change how deals are structured.
  • The “No-Tax” Sectors: Restaurants, barbershops, nail salons, and construction (overtime workers) will see sustained increases in disposable income, benefiting B2B suppliers to these industries.
  • Commercial Real Estate: As money flows from refunds into savings and investment, and corporate cash is repatriated, we may see increased activity in commercial real estate and capitol equipment purchasing (aided by Section 179 deductions) .

Conclusion

The “Trillion-Dollar” injection into the US economy is a complex, multi-phased event. For the vigilant business leader, it offers a rare opportunity to capture market share and fund growth. However, the risks of misreading the “K-shaped” distribution or the timing of the spend are high. By preparing now, global leaders can ensure they are positioned to ride the wave rather than be swept away by it.

Get help to protect and grow your business faster with BusinessRiskTV business solutions

Find out more about growing your business faster regardless of business environment with BusinessRiskTV

Subscribe for free business risk management ideas risk reviews and cost reduction tips

Connect with us for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos

#USEconomy #TaxRefund2026 #BusinessRiskManagement #BusinessRiskTV #RiskManagement

Trillion-Dollar USA Stimulus: Tax Refund & Repatriation Tsunami – A Business Risk Analysis for Global Leaders

AI Private Equity Debt Risks: Parallels to 2008 Subprime Crisis

As private equity pours billions into AI corporate bonds to fund the “Big Seven” tech expansion, striking parallels to the 2008 subprime mortgage crisis are emerging. Explore the risks of circular funding, opaque credit ratings, and what this “AI Supercycle” debt means for global business stability and the economy in 2026.

Is AI Debt the New Subprime? The Private Equity Risks Facing the Big Seven

The global economy is currently witnessing a massive capital deployment into Artificial Intelligence infrastructure, largely driven by the “Big Seven” tech giants and fuelled by complex private equity debt. However, beneath the surface of this technological gold rush, risk managers are identifying structural echoes of the 2008 financial crisis. From “circular funding” loops to the role of credit rating agencies, the parallels are becoming too significant to ignore.

The Structural Parallels Between Mortgages and Models

In 2008, the “bedrock” was residential real estate; in 2026, it is the data centre. The fundamental belief driving today’s market is that AI demand will grow exponentially forever, mirroring the pre-2008 mantra that “home prices never go down.”

Credit rating agencies are once again under the spotlight. Just as they assigned AAA ratings to subprime mortgage-backed securities based on flawed correlations, they are now assessing AI-related corporate bonds and infrastructure debt with high grades. These ratings often rely on the perceived strength of the “Big Seven” (Microsoft, Alphabet, Amazon, Meta, Apple, Nvidia, and Tesla), yet they may overlook the rapid depreciation of the underlying collateral—GPUs and specialised servers that could become obsolete within years.

The Danger of Circular Funding and Shadow Banking

One of the most concerning parallels is the rise of “Circular Financing.” We are seeing a loop where tech giants invest equity into AI startups, which then use that same capital to lease compute power back from the investor’s cloud platforms. This inflates revenue figures and creates a “phantom” growth narrative.

Private equity firms and private credit lenders—the “shadow banks” of the modern era—are providing the leverage for these deals with less transparency than traditional regulated banks. This opacity mirrors the off-balance-sheet vehicles that hid systemic risk two decades ago. If the cash flows from AI applications do not materialise fast enough to service this debt, the entire “infinite money loop” could collapse, leading to a significant credit crunch.

What This Means for Global Businesses and the Economy

For modern businesses, this debt-heavy environment presents a unique set of risks. Companies relying on AI infrastructure could face sudden service disruptions or skyrocketing costs if their providers suffer a liquidity crisis. Furthermore, as regulators begin to flag these risks, the cost of borrowing for even non-AI businesses may rise as capital markets tighten in anticipation of a “re-rating.”

While some analysts argue that the “Big Seven” have enough cash to withstand a bubble burst, the systemic risk lies in the interconnectivity of the private equity ecosystem. A default in the mid-market AI sector could trigger margin calls and a “flight to quality,” potentially leading to a “tech-led” recession. Unlike 2008, the impact may be concentrated within the technology and private equity sectors, but in a world where tech is the backbone of all industry, the ripple effects will be felt globally.

To protect your business from the systemic risks associated with the AI debt bubble and private equity volatility, business leaders should implement a multi-layered risk management strategy.

Here are six actionable tips to build resilience today:

1. Conduct a “Shadow Infrastructure” Audit

Many businesses are unknowingly exposed to AI debt through their third-party vendors. Identify which of your critical service providers—from CRM systems to cybersecurity—rely on “Big Seven” cloud infrastructure or are heavily funded by private equity.

  • Action: Create a risk map of your technology stack. If a key vendor is part of a “circular funding” loop, they are higher risk for sudden insolvency or price hikes.

2. Diversify Across “Model Families”

Avoid “vendor lock-in” by ensuring your AI integrations are model-agnostic. Relying on a single provider’s API makes you vulnerable to their specific credit rating or debt obligations.

  • Action: Use an orchestration layer that allows you to swap between different Large Language Models (LLMs) or cloud providers (e.g., shifting from Azure to AWS or a private local server) without rewriting your entire codebase.

3. Move from Efficiency to “Compute Sovereignty”

During the 2008 crisis, businesses with “on-balance-sheet” assets fared better than those with complex lease agreements. Similarly, in an AI credit crunch, having your own dedicated compute resources can be a lifeline.

  • Action: For mission-critical AI tasks, consider “Small Language Models” (SLMs) that can run on local, owned hardware rather than relying exclusively on the expensive, debt-funded “Big AI” clouds.

4. Implement “Reverse Stress Testing”

Instead of asking “What if revenue drops?”, ask “What if our AI costs triple or the service goes offline for a month?”

5. Monitor “Counterparty Contagion” in Your Supply Chain

The AI debt risk isn’t just in tech; it’s in any industry where private equity has used “AI transformation” as a reason to over-leverage.

6. Build a “Physical-First” Contingency Plan

In a world increasingly dependent on virtualised, debt-backed intelligence, the ultimate hedge is physical and operational resilience.

#BusinessRisk #AIDebt #FinancialCrisis2026 #BusinessRiskTV #RiskManagement

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster marketing and advertising with BusinessRiskTV 

Subscribe for free business risk management ideas risk reviews and cost reduction tips

Connect with us for free business risk management tips

Read more business risk management articles and videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos 

AI Private Equity Debt Risks: Parallels to 2008 Subprime Crisis

Silver Market Crisis and Business Risks

Global silver markets are facing a systemic crisis in 2026 due to China’s export ban and COMEX inventory depletion. This article outlines 6 critical risk management steps for businesses to secure physical silver and mitigate paper market volatility.

The 2026 Silver Supply Crisis: Is the COMEX Paper Market a Systemic Risk to Your Business?

The global silver market has entered a period of unprecedented structural instability. In early 2026, the long-predicted “decoupling” of paper silver prices from physical reality has finally arrived. For business leaders in the technology, green energy, and automotive sectors, the reliability of the COMEX silver market is no longer a given—it is a critical vulnerability.

The Perfect Storm: China’s Export Ban and the Singapore Shutdown

Enterprise risk management magazine articles and videos on business growth and business protection
GLOBAL SILVER CRUNCH 2026: SYSTEMIC RISK FOR BUSINESSES

The current crisis is driven by two massive geopolitical and logistical shifts that have fundamentally altered the flow of physical metal:

  1. China’s Physical Fortress: As the world’s leading refiner, China’s decision to ban the export of physical silver has “ring-fenced” a massive portion of the global supply for its own domestic AI and solar infrastructure.

  2. The Singapore Liquidity Gap: The sudden shutdown of major physical supply hubs in Singapore has removed a vital “safety valve” for Western manufacturers, leaving the market reliant on depleted COMEX and LBMA vaults.

Why the COMEX “Paper Market” is a Systemic Threat

The COMEX operates on a fractional reserve system. In a stable environment, only a small percentage of contract holders ever stand for physical delivery. However, as physical silver premiums skyrocket in the East, the “paper-to-physical” ratio has become unsustainable.

If industrial users lose confidence in the exchange’s ability to deliver physical metal, the resulting “short squeeze” could lead to a systemic failure, leaving businesses with useless paper hedges and no raw materials to maintain production lines.


6 Strategic Risk Management Measures for Business Leaders

To navigate the 2026 silver disruption, executive teams must pivot from traditional procurement to a strategic resilience model.

1. Secure Direct Mine-to-Manufacturer Off-take Agreements

Eliminate the “middleman” of the exchanges. By establishing direct contracts with primary silver miners in jurisdictions like Mexico, Peru, and Australia, businesses can guarantee a physical flow of metal that is not subject to the liquidity crises of paper markets.

2. Transition to Strategic Physical Stockpiling

The “Just-in-Time” delivery model is a liability in a deficit market. Business leaders should treat silver as a strategic asset, holding 6 to 12 months of physical inventory in secure, private, non-bank vaults to ensure operational continuity during exchange “force majeure” events.

3. Aggressive R&D in Material Substitution (Thrifts)

In sectors like photovoltaics (PV) and EV manufacturing, reducing silver intensity is now a competitive necessity. Invest in R&D to accelerate the adoption of copper-plated contacts or advanced conductive polymers to lower your “silver-per-unit” exposure.

4. Implement Vertical Integration with “Urban Mining”

The silver supply of the future is in the scrap of the past. Partnering with or acquiring e-waste recycling firms allows a company to create a closed-loop supply chain, reclaiming silver from end-of-life electronics to feed new production.

5. Geopolitical Supply Chain Diversification

With China’s export ban in place, businesses must aggressively vet new refining partners in “friendly” nations. Diversifying your refining sources across multiple geographic zones mitigates the risk of further export licenses or geopolitical tariffs.

6. Dynamic Pricing and Force Majeure Contract Audits

Review all downstream customer contracts. Ensure your pricing models allow for “raw material surcharges” to pass on extreme silver volatility. Additionally, audit your procurement contracts to ensure “delivery failure” by an exchange is not used by suppliers as a valid excuse for non-performance.


Conclusion: Adapting to the New Metallic Reality

The era of cheap, abundant, and easily hedged silver is over. The COMEX paper market remains a useful price discovery tool for now, but it can no longer be the sole foundation of an industrial supply chain. Leaders who act now to secure physical flows will thrive; those who rely on paper may find their production lines at a standstill.

#SilverCrisis2026 #SupplyChainRisk #BusinessResilience #BusinessRiskTV #RiskManagement

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV 

Subscribe for free business risk management ideas risk reviews and cost reduction tips

Connect with us for free business risk management tips

Read more business risk management articles and view videos for free

Connect with us for free alerts to new business risk management articles and videos 

Silver Market Crisis and Business Risks

BusinessRiskTV Analysis: The End of Dollar Dominance? A Strategic Risk Guide for Leaders

The global monetary order is undergoing its most significant shift in decades. This analysis cuts through the headlines to reveal the converging threats of U.S. debt dependency, active de-dollarization by the Global South, and disruptive financial technology like Project mBridge. Business leaders must understand these structural changes to navigate imminent risks of higher capital costs, complex currency fragmentation, and a fundamental re-drawing of global financial power away from New York and SWIFT. Reading this full analysis is essential for strategic planning in a new era of economic uncertainty.

The End of Dollar Dominance? A Business Leader’s Risk Management Guide

The Looming $10 Trillion Debt Refinance: A Ticking Time Clock?

The immediate pressure point for the U.S. financial system is staggering. Analysis indicates that approximately $10 trillion of U.S. Treasury debt—about one-third of the marketable total—needs to be refinanced in the near term.

While the act of rolling over maturing bonds is routine, the context has changed dangerously. The Federal Reserve is no longer the backstop buyer it was post-2008, and traditional foreign demand is waning. The U.S. now competes for capital in a world where its creditors are actively seeking alternatives. The real cost is already clear: over $11 billion per week is spent just servicing the existing national debt. For business leaders, this signals a future of persistently higher real interest rates, directly impacting corporate borrowing costs, valuations, and investment plans.

Stealthy De-Dollarization: How the Global South is Quietly Escaping

Nations are not selling U.S. bonds en masse but are engaging in a “managed strategic liquidation.” The strategy is to let bonds mature and not reinvest the proceeds, gradually reducing exposure without crashing the market.

The evidence is in the reserves:

  • The foreign share of U.S. Treasury ownership has plummeted from over 50% post-2008 to around 30%.
  • Central banks, led by China, have become net buyers of gold for 18 consecutive months, directly swapping paper dollar claims for tangible assets they control.
  • The dollar’s share of global foreign exchange reserves has steadily declined from ~72% in 2001 to approximately 57%.

This is a deliberate hedge against geopolitical risk and a loss of trust, accelerated by the freezing of Russian assets. For businesses, this means preparing for a multi-currency invoicing and settlement reality, where the dollar is first among equals, not the sole master.

Beyond the Petrodollar: The Rise of the Petro-Yuan and BRICS Unit

The “death of the petrodollar” is not an event but a process. Major oil producers like Saudi Arabia, the UAE, and Russia within the expanded BRICS+ bloc are openly transacting in non-dollar currencies.

However, creating a true rival reserve currency is fraught with difficulty. The Chinese Renminbi (RMB) faces hurdles as a global store of value due to capital controls. The practical challenge for BRICS is creating deep, liquid financial markets to recycle trade surpluses. The trend, however, is irreversible. Business supply chains and trade finance operations must now build flexibility for bilateral currency settlements (e.g., RMB-Riyal, Rupee-Dirham), moving away from exclusive dollar dependence.

Project mBridge: The Technological Knockout Punch to SWIFT

This is where systemic risk accelerates. Project mBridge is not a theory; it is a live multi-Central Bank Digital Currency (CBDC) platform involving the central banks of China, Saudi Arabia, the UAE, Thailand, and Hong Kong, with observers including India, Brazil, and even the Federal Reserve Bank of New York.

Its threat is existential to the current system:

  • It Bypasses Scrutiny: It enables instant, peer-to-peer cross-border payments that completely avoid the SWIFT network and U.S. oversight.
  • It Erodes Network Effects: It provides a sanctioned, efficient channel for trading energy and goods, directly challenging the dollar’s transactional hegemony.
  • It Redefines Control: New York can no longer control the movement of money that flows through this independent ledger. For compliance officers, this creates a nightmare of sanctions evasion and conflicting legal jurisdictions.

Why the Old Economic Cycle is Breaking—And What Comes Next

Traditional predictors like the inverted yield curve and the Sahm Rule have flashed red, yet a classic recession has not materialized. This signals a cycle under profound stress, not a clean break. The system is being prolonged by unusual labor dynamics and fiscal stimulus, but its foundations—dollar dominance and cohesive global finance—are fracturing.

We are moving from a single-cycle world economy to a fragmented, multi-bloc system. This fragmentation introduces volatile new risks alongside opportunity.

Actionable Implications for Business Leaders & Decision-Makers

  1. Hedge Your Treasury & Finance Operations: Model scenarios of sustained higher interest rates (5-7% range). Diversify cash holdings and explore currency-hedged financing options. Treat dollar dependency as a strategic vulnerability.
  2. Build Multi-Currency Agility: Work with your trade finance and treasury teams to test invoicing and settlement in alternative currencies. Develop relationships with banks that can support RMB, Euro, and direct bilateral settlement corridors.
  3. Conduct a Geopolitical Finance Stress Test: Map your exposure to payments infrastructure. What would happen if SWIFT access were complicated for key partners? How would you pay or be paid? Understand the legal risks of engaging with platforms like a future mBridge.
  4. Re-evaluate “Safe” Assets: The definition of a safe-haven asset is broadening beyond U.S. Treasuries. Consider the role of strategic commodity reserves, holdings in key partner currencies, and even corporate gold hedging in extreme scenarios.

#BusinessRiskManagement #GlobalEconomy #DeDollarization #StrategicRisk #FinancialRisk #GeopoliticalRisk #Leadership #BRICS #ProjectmBridge #CBDC #SWIFT #USDebt #Petrodollar

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV 

Subscribe for free business risk management ideas risk reviews and cost reduction tips

Connect with us for free business risk management tips

Read more business risk management articles and view videos for free

Connect with us for free alerts to new business risk management articles and videos 

Venezuela Gambit: A Strategic Pillar for Dollar Defense

The geopolitical moves in Venezuela are not merely about regional politics or human rights. Viewed through the lens of the global currency war, they represent a high-stakes defensive action for the U.S. dollar system.

Venezuela as a Contradiction and an Opportunity

Venezuela presents a unique paradox in the de-dollarization narrative. While nations like Russia and China are actively building non-dollar systems, Venezuela has undergone a profound, bottom-up de facto dollarization. Due to catastrophic hyperinflation that rendered the Bolívar virtually worthless, over half of all transactions in the country are now conducted in U.S. dollars, with the figure reaching 80-90% in some urban and border areas. This was not a policy choice by the socialist government but a survival mechanism adopted by its citizens and businesses. For the U.S., this creates a critical beachhead.

The Real Reason: Securing the Dollar’s “Network Effect”

The core strength of the U.S. dollar is its unparalleled network effect. Every new country or transaction that uses the dollar makes the entire system more valuable, liquid, and entrenched. Venezuela’s informal adoption of the dollar, despite its government’s anti-American stance, is a powerful testament to this network’s resilience.

Why Americans See Venezuela as Part of the Solution

  • A Case Study in Dollar Inevitability: For U.S. strategists, Venezuela is the ultimate demonstration that when a local currency utterly fails, economic actors will choose the dollar. It proves the greenback’s role as the only viable global safe haven, a powerful narrative against de-dollarization efforts.
  • From Informal to Formal Dollarization: There is a significant push, including from high-profile economists, for Venezuela to move from de facto to official dollarization—adopting the U.S. dollar as its legal tender. This would permanently lock a major Latin American economy and a founding OPEC member into the dollar orbit, stripping a potential rival like China or Russia of a strategic foothold in America’s backyard.
  • Countering Petro-Yuan Ambitions: Venezuela possesses the world’s largest proven oil reserves. A dollarized, U.S.-aligned Venezuela would ensure these reserves are traded in dollars, acting as a bulwark against the expansion of petro-yuan contracts. It neutralizes a key energy resource from being weaponized in the currency war.

The Strategic Calculus for Washington
Therefore, U.S. actions in Venezuela—from sanctions to diplomatic pressure—can be interpreted as an effort to steer this dollarization process toward a permanent, formal outcome under a friendly government. The goal is to flip a liability (an adversarial, unstable state) into a strategic asset (a formally dollarized economy that reinforces the currency’s dominance). Successfully anchoring Venezuela in the dollar bloc would deliver a dual victory: weakening the momentum for regional alternatives like a BRICS unit and providing a compelling counter-narrative to the de-dollarization trend by showing the dollar’s irresistible pull even in hostile environments.

Crypto Magazine

BusinessRiskTV Analysis: The End of Dollar Dominance? A Strategic Risk Guide for Leaders

The Fed’s Pivot: Navigating a New Era of Financial Stability-Driven Policy

Discover why the Federal Reserve’s 2025 policy shift prioritises financial stability and managing US debt costs over traditional inflation targets. This analysis reveals the critical threats and opportunities for business leaders, with a focus on survival strategies for regional banks. Learn 6 essential risk management steps to protect your business, secure lower-cost debt, and gain competitive advantage in this new economic era. Essential reading for CEOs and strategists navigating increased volatility and regulatory change.

Decoding the Federal Reserve’s New Priority for Business Leaders

In December 2025, the Federal Reserve cut interest rates, citing a shift in the “balance of risks.” While inflation and employment remain stated goals, a deeper analysis reveals a critical new priority is guiding policy: managing systemic financial stability and the cost of government borrowing. For business leaders, particularly those in vulnerable sectors like regional banking, this is not a minor adjustment—it’s a fundamental shift in the economic rulebook. The Fed is effectively navigating a tri-lemma: balancing price stability, employment, and the prevention of financial system stress, with the latter gaining urgent prominence. This article provides a strategic roadmap for leaders to turn this systemic challenge into a competitive advantage.

The New Reality: Financial Stability as the Fed’s Unspoken Mandate

Recent Federal Reserve communications and regulatory actions strongly indicate a reorientation of priorities, confirming a more complex operating environment.

  • The Stated Mandate vs. The Emerging Focus: The FOMC’s statements continue to reaffirm the dual mandate. However, the November 2025 Financial Stability Report provides the key insight. It details an intense monitoring framework for systemic vulnerabilities—valuation pressures, excessive borrowing, and leverage—and explicitly states that “financial stability supports the objectives assigned to the Federal Reserve.” This positions financial stability not as a separate goal, but as a critical precondition for achieving the others.
  • A Regulatory Shift Confirms the Priority: This shift is most concretely seen in bank supervision. The Fed’s new supervisory principles instruct examiners to focus squarely on “material financial risks threatening the safety and soundness of banks” and to de-emphasise procedural issues. This “reorientation” is a direct response to systemic threats, aiming to make the banking system more resilient.
  • The Regional Bank Pressure Point: The plight of USA regional banks is central to this pivot. Many are grappling with the lingering impact of earlier rate hikes, unrealised losses on securities, and intense funding pressures. A systemic crisis in this sector is a clear and present danger. The Fed’s policy stance is now attuned to providing a lower-cost environment to help stabilise these critical institutions and prevent a broader credit crunch.

Strategic Implications: Threats and Opportunities for the Alert Leader

This new paradigm creates a distinct landscape of risks and rewards.

🔴 Primary Threats to Business Strategy

  • Prolonged Policy Uncertainty: With three competing priorities, the path of interest rates will become less predictable and more reactive to financial market stress, complicating long-term planning.
  • Asymmetric Regulatory Scrutiny: The focus on “material financial risk” means that risks capable of causing systemic harm or threatening a bank’s soundness will draw severe action, while other compliance issues may be downgraded.
  • Volatility from Financial Channels: Economic cycles may be increasingly driven by financial system vulnerabilities (e.g., debt defaults, bank stress) rather than traditional inflation, making forecasting more difficult.

🟢 Key Opportunities for the Proactive Leader

  • Strategic Capital in a Lower-Rate Window: A sustained lower-rate environment, even with elevated inflation, provides a critical window for strategic M&A, refinancing high-cost debt, or funding long-term capital projects.
  • Operational Efficiency Through Smart Compliance: The regulatory shift allows companies to streamline compliance, focusing resources only on mitigating material financial risks, thereby reducing costs and complexity.
  • Competitive Advantage for Strong Balance Sheets: Companies with robust liquidity and low leverage will be highly attractive to banks operating under the new supervisory principles, gaining better and more reliable access to credit.

6 Essential Risk Management Steps in the New Financial Stability Era

Business leaders must act now to future-proof their organisations.

1. Integrate Financial Shock Scenarios into Core Planning

Move beyond traditional recession models. Stress test your business against sharp asset price corrections, sudden credit crunches, and counterparty failures. Model how a regional banking crisis would impact your liquidity and supply chain.

2. Recalibrate Risk Management to the “Materiality” Standard

Audit your internal controls. Align your risk framework with the Fed’s new lens by ruthlessly prioritising risks that could cause material financial harm to your enterprise. De-prioritise non-material procedural issues to free up resources.

3. Fortify Liquidity with a “Bank-Stress” Assumption

Do not assume bank credit lines are infallible. Diversify your funding sources—explore direct capital markets access, asset-based lending, or strategic cash reserves. Treat your liquidity buffer as a strategic asset.

4. Proactively Engage with Your Banking Partners

Initiate discussions with your regional and national banks. Understand how the new supervisory principles are shaping their risk appetite and lending criteria. Position your company as a low-risk, “flight-to-quality” partner to secure essential credit.

5. Decode Fed Signals for Strategic Foresight

Closely monitor the Fed’s Financial Stability Reports and speeches by supervision-focused officials. These documents are no longer academic; they are early-warning systems for sectors the Fed views as vulnerable.

6. Identify Strategic Investments in a Dislocated Market

Proactively identify potential acquisition targets or assets that may become undervalued due to financial stress in their sector or reliance on troubled banks. Prepare to act when the Fed’s stability focus creates market dislocations.

Conclusion: Leading in the Age of the Tri-Lemma

The Federal Reserve’s elevated focus on financial stability and sovereign debt costs has irrevocably changed the strategic environment. For business leaders, success will no longer come from simply forecasting inflation or jobs data. It will come from understanding financial system vulnerabilities, building resilient balance sheets, and moving with agility when the Fed’s actions create new openings.

The businesses that thrive will be those that see this not merely as a threat to be managed, but as a landscape ripe with opportunity—where strong fundamentals are rewarded, strategic capital is deployed wisely, and risk management is a core competitive discipline. The era of the Fed’s tri-lemma has begun. It is time to lead accordingly.

#FedPivot #FinancialStability #BusinessStrategy #BusinessRiskTV #RiskManagement

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV 

Subscribe for free business risk management ideas risk reviews and cost reduction tips

Connect with us for free business risk management tips

Read more business risk management articles and view videos for free

Connect with us for free alerts to new business risk management articles and videos 

The Fed’s Pivot: Navigating a New Era of Financial Stability-Driven Policy

Critical Thinking Versus Collective Stupidity: Rise Above Groupthink in Business

Discover why critical thinking beats collective stupidity in business. Learn how to avoid groupthink pitfalls and make better decisions with BusinessRiskTV.com’s risk management resources.

Critical Thinking vs Collective Stupidity: Rise Above Groupthink in Business Decision-Making

The Thinking Crisis in Modern Business

In today’s complex business environment, we face a critical crossroads: apply disciplined critical thinking or succumb to the comfortable confines of collective groupthink. The pain of uncertainty often pushes business leaders toward the seeming safety of consensus opinions and mainstream solutions. However, this avoidance of independent thinking comes at a steep price—surrendering your competitive edge, innovation, and ultimately, your business success to the “collective stupidity” that occurs when groups prioritise harmony over accurate analysis.

When critical thinking is no longer deployed, it is replaced by this collective stupidity. Most people are more comfortable agreeing with the crowd instead of questioning the common narrative. Yet as the saying goes, “when everyone is thinking the same thing, no one is thinking properly.” This article explores how business leaders can cultivate genuine critical thinking, avoid the pitfalls of groupthink, and how BusinessRiskTV.com provides tools and communities to support this vital leadership capability.

What is Critical Thinking in Business? Beyond Judgement and Assumption

Defining Critical Thinking

Critical thinking is far more than just being critical; it is a disciplined process of actively analysing, synthesising, and evaluating information to guide decision-making. In its exemplary form, it is based on universal intellectual values including clarity, accuracy, precision, consistency, relevance, sound evidence, good reasons, depth, breadth, and fairness.

The Foundation for Critical Thinking defines it as “that mode of thinking—about any subject, content, or problem—in which the thinker improves the quality of his or her thinking by skillfully taking charge of the structures inherent in thinking and imposing intellectual standards upon them.” For business leaders, this means consistently questioning assumptions, analysing data from multiple sources, and considering decisions from various perspectives before reaching conclusions.

The Critical Thinking Framework in Practice

Understanding the components of critical thinking helps business leaders implement this approach systematically. Critical thinking combines both skills and mindset across several dimensions:

Analytical Thinking involves breaking down complex business problems into manageable components, examining ideas, identifying arguments, and understanding root causes. In practice, this means systematically evaluating market research, financial reports, and operational data rather than accepting surface-level explanations.

Evaluative Thinking requires assessing the credibility of claims and strength of arguments. Business leaders must judge vendor proposals, investment opportunities, or strategic initiatives based on evidence and logical reasoning rather than popularity or tradition.

Synthetic Thinking connects information from multiple sources to form new insights and conclusions. This enables developing innovative business strategies by combining customer feedback, competitive intelligence, and operational capabilities in novel ways.

Self-Disciplined Thinking means consistently applying intellectual standards to one’s own thinking processes. Successful leaders create decision-making frameworks that force examination of personal biases and assumptions before reaching conclusions.

Fair-Minded Thinking involves considering opposing viewpoints and challenging one’s own preconceptions. Organizations that excel at critical thinking actively seek out dissenting opinions in leadership meetings and establish “devil’s advocate” roles to ensure all perspectives are considered.

The Cost of Collective Stupidity: Groupthink in Business

Understanding Groupthink Dynamics

Groupthink is a term developed by social psychologist Irving Janis in 1972 to describe suboptimal decisions made by a group due to social pressures that lead to flawed outcomes. It occurs when the drive for consensus within a group becomes so powerful that it overrides realistic appraisal of alternatives and critical thinking.

This “collective stupidity” represents a form of structural rigidity where organisations continue failing approaches simply because “that’s how we’ve always done it.” As one business innovator noted, “We’d rather be stupid than different”—highlighting the perplexing preference for known failure over the perceived risk of change.

Symptoms and Impact of Groupthink

Irving Janis identified eight symptoms of groupthink that remain relevant to modern businesses:

The Illusion of Invulnerability creates excessive optimism and encourages unnecessary risk-taking while Collective Rationalisation causes members to discount warnings and not reconsider assumptions. The Belief in Inherent Morality leads groups to ignore ethical consequences of decisions while Stereotyped Views of Out-groups fosters negative or dismissive views of competitors or critics.

Direct Pressure on Dissenters emerges when members are pressured not to express arguments against group consensus, reinforced by Self-Censorship where doubts and deviations from perceived group consensus are not expressed. The Illusion of Unanimity falsely assumes the majority view is unanimous while Self-Appointed “Mindguards” protect the group from information that might problematize the consensus.

The impact on businesses can be devastating, resulting in poor decisions due to lack of opposition or critical evaluation, stifled creativity and innovation, overconfidence in flawed strategies, overlooking optimal solutions to business challenges, and building failure into budgets and operations rather than seeking better approaches.

Real-World Examples of Groupthink in Business

Multiple case studies demonstrate how groupthink prevails over evidence-based success:

Boston Scientific experienced a 53% increase in closed sales after piloting an innovative sales method, yet rejected adoption because the model was deemed “too controversial for easy adoption.”

Kaiser Permanente saw sales efficiency jump from 110 visits/18 closed sales to 27 visits/25 closed sales using a new approach, but maintained their existing compensation structure based on visit volume rather than success.

Proctor & Gamble rejected a dramatically more effective sales method because it would require adapting manufacturing and support systems—essentially refusing success due to anticipated implementation challenges.

These cases illustrate the powerful hold of “the way we’ve always done it” even when evidence clearly demonstrates superior alternatives.

How BusinessRiskTV.com Fosters Critical Thinking and Mitigates Business Risks

Breaking Free from Collective Hypnosis

BusinessRiskTV.com positions itself as an antidote to conventional business thinking, urging leaders to “break free from the collective hypnosis often presented as certain risk information.” Their approach emphasises that “playing it safe is the biggest risk of all” in today’s rapidly changing business environment.

Rather than offering standardised solutions, BusinessRiskTV.com provides diverse perspectives and critical analysis tools to help business leaders develop their independent thinking capacity. Their platform acknowledges that “if you do not think for yourself, someone else will think and act for you, but they may not have your best interests at heart”—highlighting the vital importance of independent critical thinking in business protection and growth.

Services and Resources for Critical Thinkers

BusinessRiskTV.com offers multiple resources designed specifically to combat groupthink and foster critical thinking:

The Risk Management Think Tank provides access to diverse perspectives beyond mainstream business thinking while the Enterprise Risk Management Magazine delivers practical insights for applying critical thinking to risk management. Business Risk Watch offers ongoing monitoring of emerging threats and opportunities complemented by Live Online Workshops featuring interactive sessions for developing critical thinking skills.

Networking Opportunities facilitate connections with leaders globally across multiple industries while Expert Briefings deliver unfiltered intelligence on global business risks. Their approach is built on the premise that “without innovation, without the risk of disruption in the name of success, continued failure is the only option”—directly challenging the groupthink mentality that maintains failing approaches.

What To Do Now: Join BusinessRiskTV.com Business Risk Management Club

Membership Options Explained

BusinessRiskTV.com offers three membership tiers to suit different organisational and individual needs:

The Basic Risk Manager plan is free and includes alerts to business risk management news, access to some Member Only business intelligence, and entry to selected deals and Flash Sales.

The Pro Risk Manager plan requires an annual fee but provides full service features including discounted products, ability to submit articles and advertorials, listing in sponsors directory, and access to comprehensive risk management tools.

The Corporate Member plan is free and includes alerts to business risk management content, access to corporate business intelligence, and entry to selected deals and Flash Sales.

Developing Your Critical Thinking Capacity

Beyond membership, BusinessRiskTV.com encourages developing personal critical thinking skills through these approaches:

Question Your Sources by regularly evaluating the credibility, accuracy, and potential biases of your information sources. Analyse Arguments Systematically by breaking down problems, identifying underlying assumptions, and examining evidence from multiple angles.

Encourage Dissenting Views by actively seeking out and rewarding alternative perspectives in your organisation. Apply Structured Evaluation Frameworks using established critical thinking frameworks for important business decisions. Embrace Intellectual Humility by recognizing that “no one is a critical thinker through-and-through” and remaining open to revising your thinking.

Choose Thinking Over Conformity

The discomfort of uncertainty is not a reason to accept someone else’s certainty. Just because the pain of your uncertainty is uncomfortable does not mean you should accept someone else’s certainty just to feel better. In business leadership, the easy path of following consensus and mainstream thinking often leads to mediocre results at best, and catastrophic failures at worst.

Critical thinking is difficult—which is precisely why most people judge rather than analyse, follow rather than lead. But this difficulty represents a competitive opportunity for those willing to develop this crucial skill. As the search results emphasize, “when everyone is thinking the same thing, no one is thinking properly.”

Business success in our complex, rapidly changing environment requires breaking free from collective stupidity and developing the courage to think independently. Are you ready to “step away from the crowd exhibiting collective stupidity and instead critically think about what is best for your business”? The first step is recognising that true leadership requires not just thinking, but thinking critically.

#CriticalThinking #Groupthink #BusinessRiskManagement #DecisionMaking #BusinessRiskTV

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV 

BusinessRiskTV Business Risk Management Club Membership

Subscribe for free business risk management ideas risk reviews and cost reduction services

Connect with us for free business risk management tips

Contact Us To Subscribe BusinessRiskTV – Reach Global Decision Makers

Read more business risk management articles and view videos for free

Connect with us for free alerts to new business risk management articles and videos 

Critical Thinking Versus Collective Stupidity Groupthink in Business

The West’s Ukraine Strategy: A Catastrophic Policy Failure & The Business Cost

The Ukraine conflict represents a catastrophic failure of Western policy, not just Russian aggression. Leaders in the UK, Germany, and France are accountable for a series of critical errors—from pre-war NATO provocation and the Minsk Agreement debacle to slow-walking military aid and sabotaging peace talks. These decisions have prolonged a devastating war, resulting in needless loss of life and squandering billions in public funds. This analysis details the 9 reasons why these policies constitute a profound strategic failure and why citizens must now demand a resolution focused on diplomacy and economic stability over prolonged conflict.

Key Critiques of UK, German, and French Policy on Ukraine

A critical analysis of how leaders in the UK, Germany, and France bear responsibility for prolonging the Ukraine conflict. Explore the 9 key policy failures—from failed diplomacy and economic mismanagement to escalation risks—that have cost hundreds of thousands of lives and billions in taxpayer funds. Learn why citizens must demand accountability and a new path toward peace.

Critics, who come from both the political left and right, often point to a series of pre-war and ongoing policy failures.

1. Pre-War Provocation and Failed Diplomacy (The “Sleepwalking” Critique)

  • Critique: For years, despite warnings from Russia, the US and key European powers like the UK, France, and Germany expanded NATO eastward. While sovereign nations have the right to choose their alliances, critics argue this was strategically reckless, needlessly threatening Russia’s core security interests and creating a predictable confrontation. This is seen as a failure of statesmanship that boxed all parties into a corner.
  • Accountability: Leaders are accused of prioritising a hawkish, ideological expansion of Western influence over a pragmatic, security-based diplomacy that could have averted war.

2. The Minsk Agreement Debacle

  • Critique: The Minsk Agreements (2014-2015), brokered by France and Germany, were meant to bring peace to Donbas. However, recent admissions from figures like former German Chancellor Angela Merkel suggested the agreements were primarily a tool to “give Ukraine time” to build its military. Critics argue this reveals profound bad faith, proving to Russia that diplomatic agreements with the West are not trustworthy, thereby destroying a potential path to peace and making the 2022 invasion seem inevitable from Moscow’s perspective.

3. Slow-Walking Military Aid & “Waging a Slow War”

  • Critique: Especially in the early stages (and periodically since), Germany, France, and the UK have been accused of “drip-feeding” military aid. They provided just enough to keep Ukraine from collapsing, but not enough to achieve a decisive victory. This is criticized as a strategy that prolongs the war, maximizing Ukrainian casualties and destruction while minimizing direct risk to NATO, effectively “fighting to the last Ukrainian.”
  • Example: The long, drawn-out debates over delivering tanks, long-range missiles, and aircraft are cited as key examples where hesitation cost lives and strategic advantage.

4. Undermining and Delaying Peace Talks

  • Critique: In the spring of 2022, peace talks between Ukraine and Russia showed promise. Critics allege that Western powers, particularly the UK under then-PM Boris Johnson, advised Ukraine to break off negotiations, promising full-scale Western support to win back all territory. By taking a maximalist “no negotiation” stance, they are seen as having sabotaged a potential, if imperfect, peace deal that could have saved hundreds of thousands of lives.

5. Economic Mismanagement and the Cost to Citizens

  • Critique: The billions in aid sent to Ukraine are framed not as noble support, but as a massive transfer of wealth from Western citizens during a cost-of-living crisis. Critics argue this spending fuels inflation, diverts funds from domestic healthcare, education, and infrastructure, and primarily benefits the military-industrial complex, all while the financial burden is borne by the taxpayers of the UK, Germany, and France.

6. Lack of a Clear Strategic Endgame

  • Critique: Two years into the conflict, there is no publicly defined strategic goal for the war. Is the aim to return to 1991 borders? 2014 borders? Merely weaken Russia? This lack of a clear, achievable political objective is a massive strategic failure. It commits these nations to an open-ended conflict with no exit strategy, guaranteeing further waste of lives and money without a defined concept of “victory.”

7. Escalation Risks and Brinksmanship

  • Critique: By continuously pushing the boundaries of military aid—from artillery to tanks to long-range missiles—these leaders are playing a dangerous game of brinksmanship. Critics argue they are ignoring the real and existential risk of a direct NATO-Russia war, which could escalate to nuclear conflict. The responsibility for managing this risk lies with the major Western powers, and their current policies are seen as recklessly increasing it.

8. The “Double Standard” on International Law

  • Critique: This argument, often from the left, states that the UK, France, and Germany apply international law selectively. They rightly condemn Russia’s invasion but have historically ignored or participated in violations (e.g., Iraq, Libya, Yemen). This hypocrisy, critics argue, undermines the moral high ground and the very rules-based order they claim to be defending, making their stance seem more about geopolitical power than principle.

9. Neglecting Diplomacy as a Tool

  • Critique: The current policy is almost entirely militaristic. Critics argue that leaders in Berlin, Paris, and London have a responsibility to pair military support with aggressive, creative diplomacy. By refusing to seriously explore diplomatic channels, ceasefires, or potential compromises, they are choosing a path of endless attrition over statecraft, ensuring the continued loss of life and economic damage.

Why Citizens of These Countries Should Act

Based on these critiques, the argument for citizen action is clear:

  • Sovereignty and Consent: The governments of the UK, Germany, and France are acting in the name of their citizens. Therefore, citizens have a democratic right and responsibility to scrutinize these policies and their costs.
  • Direct Impact: The citizens of these nations are directly paying the price through higher taxes, inflated living costs, and diverted public funds. Their security is also being put at risk through escalation.
  • Correcting a Failed Policy: If the current path is seen as a “policy mistake” that is wasting lives and treasure without a realistic chance of a satisfactory outcome, then public pressure is the primary democratic mechanism to force a change in course towards a strategy that prioritises peace and diplomacy.

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV 

Subscribe for free business risk management news reviews and cost cutting deals

Connect for free business risk management tips

Read more free business risk management articles and view videos

Connect for free alerts to business risk management articles 

Wests Ukraine Strategy Failure Business Cost

Anti-Fragility Mentality: The UK Business Guide to Thriving on Volatility

Don’t just survive—thrive. In today’s volatile UK market, being resilient isn’t enough. Discover the anti-fragility mentality, a powerful concept that helps businesses grow stronger from shocks and uncertainty. Our guide reveals the dangers of feeling too scared to grow, explains why positively fighting back against business fears works better, and provides 9 practical risk management strategies to build a more robust, adaptable, and profitable business. Learn how to transform every crisis into a competitive advantage.

Discover how an anti-fragility mentality can help your UK business thrive on stress and volatility. Learn why fear of growth is dangerous and get 9 practical risk management strategies to build a more robust, adaptable, and profitable company.

Anti-Fragility Mentality: The UK Business Guide to Thriving on Volatility 🇬🇧

In the complex and unpredictable world of business, it’s not enough to be resilient or robust; you must be anti-fragile. This is a concept, popularised by author Nassim Nicholas Taleb, that suggests some systems, like a business, don’t just withstand shocks—they actually get stronger because of them. While a resilient company recovers from a crisis, an anti-fragile one learns, adapts, and improves. Instead of just surviving, an anti-fragile business uses volatility, uncertainty, and stress as fuel for growth. This is especially relevant for UK businesses navigating a post-Brexit, globalised, and tech-driven market.


The Dangers of Business Fear and Over-Cautiousness

When leaders are too scared to grow, their business becomes fragile. Fear of failure or even fear of success can lead to a state of paralysis. Instead of embracing opportunities, a business with a risk-averse culture will hesitate, self-sabotage, and miss out on potential gains. This mindset can:

  • Stifle innovation: You avoid new technologies, markets, or product lines, leaving you vulnerable to competitors who are bolder.
  • Prevent scalability: Your business systems, processes, and team structures become too rigid to handle growth, leading to spiralling costs and poor service if demand increases.
  • Create dependency: Over-reliance on a single client, supplier, or revenue stream makes the business incredibly fragile.
  • Damage morale: A culture of fear can demotivate employees and discourage them from taking initiative.
  • Expose you to a slow decline: While you might avoid a sudden crisis, a cautious approach often leads to a gradual loss of market share and relevance.

Why Positively Fighting Back Against Crisis Works Better

An anti-fragile business doesn’t just react to a crisis; it uses the crisis to its advantage. Instead of a defensive mindset, it adopts an offensive one, turning problems into opportunities. This approach works better because:

  • It forces innovation: A crisis can be a powerful catalyst for change, forcing you to find creative solutions you wouldn’t have considered otherwise.
  • It builds stronger systems: A crisis reveals weaknesses. By addressing these weak points, you build more robust, efficient, and reliable systems for the future.
  • It strengthens relationships: Transparent communication and proactive problem-solving during a crisis builds trust with employees, customers, and partners.
  • It creates a competitive advantage: While your competitors are busy recovering, you’re using the disruption to pull ahead, secure new markets, or attract talent.

Who Can Help You Take More Calculated Risks

Taking calculated risks is a team sport. While the final decision rests with the leadership, a smart leader leverages the entire business to inform their choices. Key roles that can help you become more anti-fragile include:

  • Senior Leadership: A strong, forward-thinking leadership team that fosters a culture of smart risk-taking and learning from failure.
  • The Finance Team: Your finance department is crucial. They provide the data and analysis needed to understand the potential financial impact of a risk.
  • IT & Cybersecurity: They assess the risks associated with new technologies and ensure your digital infrastructure can handle growth and shocks.
  • Department Heads: They have a direct view of operational risks and can identify opportunities for improvement.
  • Employees at all levels: Front-line staff often have the best insights into day-to-day problems and can suggest innovative solutions.

Where You Can Protect Yourself from an Over-Cautious Mentality

To counter a culture of over-cautiousness, you need to create an environment where smart risk-taking is encouraged. Focus on these areas:

  • Your company culture: Foster a “growth mindset” that views mistakes as learning opportunities rather than failures.
  • Your team structure: Empower teams to make decisions without excessive layers of approval.
  • Your communication channels: Create open and transparent communication where bad news and new ideas can be shared without fear.
  • Your strategic planning: Incorporate scenario planning and “what-if” exercises to prepare for a range of potential outcomes, both good and bad.

When to Feel More Robust

You can feel more robust and confident in your business’s ability to handle stress when you have:

  • Consistent cash flow: A healthy financial position provides the buffer needed to withstand shocks and invest in new opportunities.
  • A diversified portfolio: You’re not reliant on a single customer, product, or market.
  • Strong systems and processes: Your business operations are streamlined, efficient, and can handle increased demand without breaking.
  • An engaged and skilled team: Your employees are aligned with your goals and are ready to adapt to changing circumstances.

9 Practical Anti-Fragility Risk Management Strategies

  1. Embrace Optionality: Have multiple, low-risk options available. For example, explore several new markets with a small investment rather than committing to one with a large one.
  2. Redundancy is a Virtue: Don’t rely on a single supplier or a single server. Create backups and redundancies to prevent single points of failure.
  3. Conduct “Pre-Mortems”: Instead of a post-mortem after failure, imagine a project has failed and work backwards to identify the reasons. This helps anticipate risks before they occur.
  4. Adopt a “Fail Fast, Learn Faster” Mindset: Launch small, experimental projects (Minimum Viable Products) to test ideas without significant risk.
  5. Decentralise Authority: Empower smaller teams to make decisions. This allows for faster responses to local challenges and opportunities.
  6. Maintain a Cash Buffer: Keep enough cash on hand to cover a significant period of low revenue. This financial buffer is the bedrock of anti-fragility.
  7. Gamify Risk Management: Use internal games or simulations to train your team on how to respond to unexpected events, building both muscle memory and a proactive mindset.
  8. Diversify Your Team’s Skillset: Hire for versatility and adaptability. A team with diverse skills is more likely to find creative solutions during a crisis.
  9. Build Strong Stakeholder Relationships: Foster trust with your customers, suppliers, and investors. Strong relationships provide a support network that is invaluable in a downturn.

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about business protection and business growth with BusinessRiskTV 

Subscribe for free business risk management ideas reviews and cost reduction deals

Connect with us for free business risk management tips

Read more free business risk management articles and view videos

Connect with us for free alerts to new business risk management articles and videos 

Anti-Fragility Mentality Business UK Risk Management Strategies

The 2025 Insurance Crisis: Is the Sky Falling?

Insurer of Last Resort Failure: Implications for Businesses

California. 2025. Wildfires raged. Homes vanished. Insurance companies, battered by years of escalating losses, simply stopped writing new policies. Homeowners were left stranded, unable to secure coverage, their dreams of homeownership reduced to ash. This wasn’t a dystopian novel; it was a chilling glimpse into a potential future where the insurance landscape is dramatically shifting, leaving businesses and individuals alike facing unprecedented uncertainty.

2025 Insurance Crisis: Navigating the New Normal for Businesses

The insurance industry is in the midst of a perfect storm. Climate change is fuelling more frequent and intense natural disasters. Cyberattacks are growing in sophistication and scale. And inflation is squeezing insurers’ margins, making it harder to price risk accurately. As a result, insurers are becoming increasingly selective, cancelling policies for high-risk properties, withdrawing entirely from certain markets, and even refusing to cover specific perils. This leaves businesses and individuals facing a daunting question: who will insure the uninsurable?

Enter the “insurer of last resort.” This concept, while seemingly reassuring, is fraught with challenges. These entities, often government-backed programmes, are designed to step in when the private market fails. However, they are not immune to the same financial pressures that are crippling the private insurance sector. What happens when the insurer of last resort runs out of money? The consequences could be catastrophic, potentially leading to systemic failures within the insurance industry and a cascade of economic and social disruptions.

The global rise in bond yields on sovereign debt is further exacerbating the situation. As interest rates climb, the cost of capital for insurers increases, making it more expensive to invest reserves and potentially impacting their ability to offer competitive premiums. This could lead to a vicious cycle: higher premiums, reduced affordability, and ultimately, a decline in insurance coverage.

This crisis demands a multi-pronged approach. Governments must play a crucial role in mitigating climate change, improving disaster preparedness, and strengthening the regulatory framework for the insurance industry. Businesses, too, must adapt. Proactive risk management strategies, including robust cybersecurity measures and investments in climate resilience, are essential for navigating this uncertain landscape.

The good news is that there are concrete steps businesses can take to protect themselves. By diversifying their risk portfolios, exploring alternative risk transfer mechanisms, and building strong relationships with their insurers, businesses can enhance their resilience and navigate the evolving insurance landscape.

The insurance crisis is a stark reminder that the world is changing rapidly. The risks we face are evolving, and the traditional models of insurance may not be sufficient to address these challenges. By understanding the forces at play and taking proactive steps to mitigate risk, businesses can ensure their continued success in this era of unprecedented uncertainty.

The 2025 Insurance Crisis: A Deep Dive

The insurance industry is facing a confluence of challenges that threaten its very foundation. Climate change is no longer a distant threat; it is a harsh reality. Extreme weather events, from devastating wildfires to catastrophic floods, are becoming more frequent and intense, wreaking havoc on communities and straining the financial resources of insurers.

Cyberattacks are also escalating in frequency and severity. Sophisticated ransomware attacks can cripple businesses, disrupt critical infrastructure, and cause significant financial losses. The sheer scale and complexity of these attacks are pushing the limits of traditional insurance models.

Furthermore, inflation is squeezing insurers’ margins. The rising cost of claims, coupled with the increasing cost of capital, is making it difficult for insurers to price risk accurately and maintain profitability. This is particularly challenging in the face of emerging risks like pandemics and geopolitical instability.

As a result of these pressures, insurers are becoming increasingly selective in the risks they are willing to underwrite. They are canceling policies for properties deemed to be high-risk, such as those located in wildfire-prone areas or coastal zones. They are withdrawing from certain markets altogether, leaving homeowners and businesses without access to affordable coverage. And they are even refusing to cover specific perils, such as flood damage or cyberattacks, leaving policyholders exposed to significant financial losses.

This shift in the insurance landscape has profound implications for businesses and individuals. Homeowners are facing the terrifying prospect of being uninsurable, leaving them financially devastated in the event of a disaster. Businesses, meanwhile, are struggling to obtain adequate coverage for their operations, which can jeopardize their ability to compete and thrive.

The Insurer of Last Resort: A Flawed Solution?

The concept of an “insurer of last resort” is intended to provide a safety net when the private insurance market fails. These entities, often government-backed programmes, are designed to step in and provide coverage for those who cannot obtain it in the private market.

However, the insurer of last resort model faces significant challenges. These programmes are often underfunded and ill-equipped to handle the scale of potential losses in the face of catastrophic events. For example, in the aftermath of Hurricane Katrina, the National Flood Insurance Program (NFIP) faced a massive shortfall, leaving taxpayers on the hook for billions of dollars in losses.

Furthermore, relying solely on the insurer of last resort can create a moral hazard. If individuals and businesses know that they will be covered by a government-backed programme, they may be less incentivised to mitigate their own risks. This can lead to increased reliance on government assistance and potentially exacerbate the very problems that the insurer of last resort is intended to address.

The Impact of Rising Bond Yields

The global rise in bond yields on sovereign debt is adding further pressure to the insurance industry. As interest rates climb, the cost of capital for insurers increases. This makes it more expensive for them to invest their reserves and potentially impacts their ability to offer competitive premiums.

Higher interest rates can also lead to increased borrowing costs for businesses and homeowners. This can reduce their ability to afford insurance coverage, further exacerbating the problem of underinsurance.

Navigating the Crisis: A Call to Action

This crisis demands a multi-pronged approach. Governments must play a crucial role in mitigating climate change, improving disaster preparedness, and strengthening the regulatory framework for the insurance industry. This includes investing in renewable energy sources, implementing stricter building codes, and modernising disaster warning systems.

The insurance industry itself must also adapt. Insurers need to develop innovative products and pricing models that better reflect the evolving risk landscape. This could include using data analytics and artificial intelligence to more accurately assess risk and develop more personalised pricing models.

Businesses, too, must play an active role in mitigating risk. Proactive risk management strategies are essential for navigating this uncertain landscape. This includes:

  1. Conducting thorough risk assessments: Identify and assess the potential risks facing your business, including natural disasters, cyberattacks, and supply chain disruptions.
  2. Implementing robust risk mitigation measures: Develop and implement strategies to mitigate these risks, such as investing in cybersecurity measures, strengthening supply chains, and improving disaster preparedness.
  3. Diversifying your risk portfolio: Explore alternative risk transfer mechanisms, such as captive insurance companies and catastrophe bonds, to diversify your risk exposure.
  4. Building strong relationships with your insurers: Maintain open and transparent communication with your insurers to ensure that your coverage needs are adequately addressed.
  5. Investing in climate resilience: Take steps to improve the resilience of your operations to climate change, such as relocating critical infrastructure to safer locations and investing in energy-efficient technologies.
  6. Advocating for sound public policy: Engage with policymakers to advocate for policies that support a strong and resilient insurance market.
  7. Embracing innovation: Explore innovative insurance products and technologies, such as parametric insurance and blockchain-based solutions, to address emerging risks.
  8. Investing in employee training: Educate your employees on the importance of risk management and empower them to identify and report potential threats.
  9. Developing a robust business continuity plan: Ensure that your business can continue to operate in the event of a disruption, such as a natural disaster or cyberattack.

The insurance crisis is a stark reminder that the world is changing rapidly. The risks we face are evolving, and the traditional models of insurance may not be sufficient to address these challenges. By understanding the forces at play and taking proactive steps to mitigate risk, businesses can enhance their resilience and navigate the evolving insurance landscape.

This is not a time for complacency. The insurance crisis is a wake-up call for businesses and individuals alike. By working together, we can build a more resilient and sustainable future where everyone has access to the insurance coverage they need.

Disclaimer: This article is for informational purposes only and should not be construed as financial or legal advice.

Get help to protect and grow your business faster

Find out more about Business Risk Management Club Corporate Membership 

Subscribe for free business risk management tips reviews and cost reduction ideas

Connect with us for free

Read more business risk management articles and watch videos for free

Connect with us for free

Enterprise Risk Management Magazine
Insurance Crisis

Read more on 2025 Insurance Crisis:

  1. Impact of Rising Bond Yields on Insurance Premiums 2025
  2. Insurer of Last Resort Failure: Implications for Businesses
  3. Climate Change & Insurance Crisis: Risk Management Strategies
  4. Cancelling Insurance Policies: What Businesses Should Do
  5. 2025 Insurance Crisis: Navigating the New Normal for Businesses

Relevant hashtags :

  1. #InsuranceCrisis2025
  2. #BusinessRiskManagement
  3. #ClimateChangeImpact
  4. #InsurerOfLastResort
  5. #RiskMitigationStrategies
  6. #BusinessRiskTV
  7. #ProRiskManager
  8. #Csuite
  9. #Fintech
  10. #Sustainability

x

The 2025 Insurance Crisis: Is the Sky Falling?

Business Risks And Opportunities

What are risks and opportunities in business

Managing opportunities and risks better with BusinessRiskTV. Business opportunities come with business risks. External and internal risk drivers will impact on business objectives negatively and positively. Controlling business risks and opportunities can secure greater business success and build stronger business resilience. Identify assess and control business risks better with articles and videos on BusinessRiskTV. Monitor business risks to your business objectives to protect and grow your business faster.

What are the risk and opportunities in business

Managing business risks is a critical business issue all business leaders face. However not all business leaders face the same business risks. Similar businesses can have the same business risks but may have different resources deployed in business risk management. Opportunities for business leaders to grow their business fast are always available to you if you look and take the best course of action. Understand the top business risks facing your business with help tips and support from BusinessRiskTV

Alerts are free

BusinessRiskTV Live and Ondemand

Managing Business Risks Better With BusinessRiskTV

Business Risks And Opportunities

This Will Fundamentally Change The Way You Look At Risk

Stop looking to reduce risk and instead make your business plans under a risk-based approach to business decision making with BusinessRiskTV

How can business leaders change business performance with a more risk based approach to business management?

Are you interested in boosting your business performance? Do you use online resources to improve your knowledge of business risks impacting on your business objectives? Do you want to make your business more profitable?

Do you want us to help your business grow faster

Look at risk as a positive for your business. Manage the threats better. Seize new business development opportunities quicker and enhance the benefits arising from risk taking.

Around BusinessRiskTV

  • Risk Profile v Risk Appetite – Risk tolerance vs risk appetite is important to understand. If you do not know what your risk profile is you cannot manage your business risks better. Could you increase your appetite for risk to achieve more business success? What is your risk tolerance?
  • How To Grow Business Faster Business Tips – Grow business faster with BusinessRiskTV. Use practical business growth tips. Thing how do I grow my business fast? Need how to grow business tips. Use latest business tips and marketing tools. Our business growth experts work with our Online Selling Partners providing tips for business growth. Learn how to grow your business fast with BusinessRiskTV. Pick up tips on how to grow business faster. Connect with our business growth experts and partners. Save money and time to become more profitable and other latest business tips from BusinessRiskTV.
  • iso 31010 Risk Management and Risk Assessment Techniques Guidance – Do you know where to focus our resources to protect and grow your business? iso 31010 risk assessment tools and techniques can help you identify assess and control critical risks to your business. Understand your business risks better with iso 31010 risk assessment awareness. Mitigating Threats Maximising Returns From Business Opportunities
  • Understanding and Managing Risk Better – A better way to manage business enterprise risk. Risk management courses distance learning. Develop better business risk management plan. Discover best enterprise risk management online training courses for your needs. Risk management courses UK and overseas. Join like minded senior managers executives and risk management practitioners. Learn how to manage business enterprise risk management risks better. Save money and time with BusinessRiskTV. Search for tips on developing your improved business risk management plan.

Get In Touch

Are you interested in growing your business faster? Do you use the internet to attract new customers. Do you want to sell more online? Do you want us to help your business grow faster online?

Submit a question. Share your views and experiences. Please include a contact number if you are willing to speak to us. You can get in touch in the following ways:

  • Whats App Click Here
  • Tweet @HolisticRiskMgt and @ERMuk
  • Email editor@businessrisktv.com
  • Instagram BusinessRiskTV
  • Pinterest BusinessRiskTV
  • YouTube BusinessRiskTV

Related Business Risk Management Topics

Guidance On Enterprise Risk Management On BusinessRiskTV

Pro risk manager
Do you want your business to be bigger or more profitable?

ERM Framework Implementation

Enterprise Risk Management (ERM) is the process of identifying, assessing, prioritising, and managing risks that could affect an organisation’s ability to achieve its objectives. In today’s fast-paced business environment, organizations face numerous risks, such as financial, operational, strategic, regulatory, reputational, and cybersecurity. The failure to manage these risks could lead to severe consequences, such as financial loss, legal liability, damage to reputation, and even business failure.

Therefore, it’s critical for organizations to implement a robust ERM framework to identify and mitigate risks that could potentially harm the organization. In this article, we will provide guidance on how organisations can implement an effective ERM framework to manage risks.

Establishing an ERM framework
The first step in implementing ERM is to establish a framework that outlines the organisation’s risk management policies, procedures, and practices. The framework should define the roles and responsibilities of the risk management team, establish risk assessment methodologies, and identify the key risk indicators (KRIs) that will be used to monitor risks.

The ERM framework should also identify the organisation’s risk appetite, which refers to the level of risk that the organisation is willing to accept in pursuit of its objectives. The risk appetite should be clearly defined and communicated to all stakeholders, including employees, investors, customers, and regulators.

The ERM framework should be aligned with the organisation’s strategic objectives, and the risk management team should work closely with the senior management team to ensure that risk management is integrated into the organisation’s decision-making process.

Conducting a risk assessment
The next step in implementing ERM is to conduct a risk assessment, which involves identifying, analysing, and evaluating risks that could potentially harm the organisation. The risk assessment should be based on a systematic and comprehensive approach that considers all the potential risks that the organisation faces.

The risk assessment should consider both internal and external factors that could affect the organisation’s ability to achieve its objectives. Internal factors include the organisation’s culture, structure, processes, and people, while external factors include economic, political, technological, and regulatory factors.

The risk assessment should also consider the likelihood and impact of each risk and prioritise them based on their significance. The risk assessment should be updated periodically to ensure that new risks are identified and managed.

Developing a risk management plan
Once the risks have been identified and prioritised, the next step is to develop a risk management plan that outlines the actions that will be taken to manage each risk. The risk management plan should consider the risk appetite of the organisation and the resources that are available to manage the risks.

The risk management plan should include specific measures to mitigate each risk, such as risk avoidance, risk reduction, risk transfer, and risk acceptance. Risk avoidance involves eliminating the risk altogether, while risk reduction involves implementing measures to reduce the likelihood or impact of the risk. Risk transfer involves transferring the risk to another party, such as an insurance company, while risk acceptance involves accepting the risk and managing it within the organisation’s risk appetite.

The risk management plan should also identify the stakeholders who will be responsible for managing each risk and the KRIs that will be used to monitor the risks. The risk management plan should be reviewed periodically to ensure that it remains effective and relevant.

Implementing risk management controls
The next step in implementing ERM is to implement risk management controls to manage the risks. Risk management controls are the policies, procedures, and practices that are implemented to manage the risks identified in the risk assessment.

Risk management controls should be designed to ensure that the organisation operates within its risk appetite and that the risks are managed effectively. Risk management controls should be integrated into the organisation’s processes and systems to ensure that they are followed consistently.

Monitoring and reporting on risks
The final step in implementing ERM is to monitor and report on risks. Monitoring involves tracking the effectiveness of the risk management controls and the KRIs that were identified in the risk management plan. The monitoring process should be designed to detect any changes in the risk environment and to ensure that the risk management controls remain effective.

Reporting involves communicating the results of the risk management process to stakeholders, such as the board of directors, senior management, investors, customers, and regulators. The reporting should provide an accurate and comprehensive view of the organisation’s risk exposure and the effectiveness of the risk management controls.

Reporting should also include any significant changes in the risk environment and any emerging risks that could potentially impact the organisation. Reporting should be timely, accurate, and relevant to ensure that stakeholders have the information they need to make informed decisions.

ERM is a critical process that organisations must implement to manage the risks they face. ERM involves identifying, assessing, prioritising, and managing risks that could potentially harm the organisation.

To implement an effective ERM framework, organizations must establish a framework that outlines the risk management policies, procedures, and practices. They must conduct a comprehensive risk assessment that considers all the potential risks that the organisation faces and prioritise them based on their significance.

They must develop a risk management plan that outlines the actions that will be taken to manage each risk and implement risk management controls to manage the risks. Finally, they must monitor and report on risks to ensure that the risk management process remains effective and relevant.

By implementing an effective ERM framework, organisations can mitigate the risks they face and achieve their objectives in a safe and sustainable manner. The ERM framework should be reviewed and updated periodically to ensure that it remains effective and relevant to the changing risk environment.

Biggest threat to business

What Will Threaten Your Business This Year

MarketplacesExhibitions
MagazinesRisk Magazine

This Will Fundamentally Change The Way You Look At Risk

How To Manage Uncertainty In Business With BusinessRiskTV

How do businesses manage risk or uncertainty with BusinessRiskTV.com

Develop your risk management tools and techniques. Pick up how to expand your business tips. Network with top business leaders and risk management experts locally and globally.

See The Road Ahead More Clearly With BusinessRiskTV

See The Road Ahead More Clearly With BusinessRiskTV

Enterprise wide risk consulting and enterprise risk management solutions training

Discover new ways to handle uncertainty in business.

  • What if the worst was to happen to your business? What maybe the worst for your business might be manna from heaven for other businesses. Your enterprise risk management plan must be bespoke to your business.
  • Engage the best assets your people more fully. Inspiring more from your workforce will build business resilience and faster growth.
  • Focus your business resources for optimal business performance.

Reap the rewards from business risk to benefit your business. Understand and manage key risk factors better to boost performance. Protect your business. Grow it faster.

Enterprise Risk Management Training Workshops Online
Enter code #ERMtraining

Creative marketing campaign ideas and tools to grow your business more profitably

Discover fresh marketing ideas. Adopt marketing strategies to fuel your business growth sustainably. Set up a profitable campaign to sell more products and services online. More easily enter a fast growing marketplace.

Cost effective ways to market your business online with BusinessRiskTV

Cost effective ways to market your business online with BusinessRiskTV

Are you looking for ideas to market and grow your business faster online?

Target your best audience to grow your business and make your marketing strategy more profitable. Learn how to run a successful marketing campaign with BusinessRiskTV. Boost sales and improve your bottom line.

Work with us to identify the most effective way to reach your new customers inexpensively. Achieve young marketing promotion and business development goals from brand awareness to engagement to driving new business. Generate leads and drive website traffic.

Enter code #ManageUncertainty

Read risk management articles and watch videostream trending on BusinessRiskTV

Risk experts help you through the toughest of times. CLICK HERE or email editor@businessrisktv.com and enter code #TheRiskExpert for free risk management alerts bulletins and reviews.

Promote and market your business on BusinessRiskTV for 12 months

Put your products and services in front of new customers already interested in your type of business offering before your competitors do.

Cheap ways to promote your business

Find out how to promote your business locally and globally. CLICK HERE for more information.

Link into your existing sales process direct from BusinessRiskTV or use our eCommerce solutions to increase your sales cash flow and profit

Increase the sources of your revenue streams more sustainably. Grow your business faster with BusinessRiskTV.

ConfidenceRisks
CommunicationBranding

Discover better ways to protect and grow your business with BusinessRiskTV

Overcoming Fear Of Uncertainty In Business

#BusinessRiskTV #TheRiskExpert #ManagingUncertainty #ManageBusinessRisks #RiskManagement #EnterpriseRiskManagement #Uncertainty #RiskAnalysis #RiskAdvisery #OperationalRisk #RiskManagment #OperationalResilience #RiskAssessment #RiskExperts #RiskAdvisory #Governance #RiskMitigation #RiskControl #StrategicRisk #ProcessImprovement #ProjectRisk #RiskTips #OperationalExcellence #GRC#ERM #ManageUncertainty

How To Manage Uncertainty In Business With BusinessRiskTV

Risk events analysis is useful but not always productive

Risk identification and assessment with BusinessRiskTV.com

You cannot change what happened but you can learn from it. However dwelling on past mistakes is not productive.

  • Mitigate negative impact of risk event and secure any benefits from risk event. Good can often come out of bad.
  • Learn lessons from risk events and move on quickly
  • Do not dwell on risk event impact as constantly punishing people from mistakes of past can be very demoralising and negatively impact on future business performance.

After the risk event make sure your risk management plan for future seeks to ensure it does not happen again but do not over do the risk controls. Reflecting on the lessons from the risk event facts is important but do not let emotions and pain of risk event change the risk perception of future likelihood of recurrence especially after some additional risk controls adopted maintained and reviewed.

Subscribe to BusinessRiskTV for free alerts and bulletins on enterprise risk management principles and practices

Promote and market your business on BusinessRiskTV for 12 months

Cheap ways to promote your business
Find out how to promote your business locally and globally

Read risk management articles and watch videostream trending on BusinessRiskTV

Top Business News Today
MarketplacesExhibitions
Save MoneyRisk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #RiskEventAnalysis #RiskAnalysis #RiskReview #CorporateRiskAnalysis #BusinessRiskAnalysis #EntepriseRiskAnalysis

BusinessRiskTV Risk events analysis is useful but not always productive

Taking more calculated risks

Why calculated risk taking is important with BusinessRiskTV.com

How can a business take more risks to perform better?

Taking more calculated risks in the next decade. Do not fear taking more calculated risks. Business leaders are often afraid to take risks.

What Is key to busness growth
Unlock faster business growth with BusinessRiskTV.com

Taking more risks to achieve more success comes down to risk knowledge and business intelligence. A lack of risk knowledge leads to increased fear. This can result in missed opportunities to grow faster.

  • What are the potential costs of taking more risks?
  • What are the potential benefits of taking more risks?
  • How will taking more risks benefit your business?
  • What are the alternatives?
  • How much better would your business perform if the best case scenario came true?
  • What are the worst outcomes that could happen if you took extra risks and how could you reduce the risk?
  • How bad would it be if the worst case scenario risk event materialised?
  • What would your business look like in 5 years if your risk decisions were taken?

Assessing the risks incorporating both upside and downside risks will enable you to make more balanced business decisions to improve performance.

Guide To Business Enterprise Risk Management ERM
Risk Appetite and Risk Tolerance

Negativity bias means in part we focus more on stopping bad things from happening than creating the environment for great good things to happen. For example, we focus on stopping climate damage instead of investing money in better natural environment. We spend more money to risk control instead of seizing new business opportunities which create risk but also create more rewards for risk takers.

Welcome the threats in the 2020s as they bring opportunities

Embrace the opportunities in the new decade but be risk aware about the threats that come with the opportunities to grow. Work together with our network of business leaders and risk management experts to finish the 2020s better than you started.

Supporting More Informed Decision-Making
Taking Risks To Achieve More In Business With BusinessRiskTV

Subscribe to BusinessRiskTV for freezing alerts and bulletins to your email inbox on how to grow your business faster with less uncertainty

Promote and market your business on BusinessRiskTV for 12 month

How to find new customers and increase sales
Targeted Marketing Investment To Hit The Potential Buyers You Need To Grow Your Business Faster

Read articles on risk taking for increased successful and watch videostream trending on BusinessRiskTV

MarketplacesExhibitions
Save MoneyRisk Magazine

#BusinessRiskTV #TakeMoreRisks #CalculatedRisks #RiskKnowledge #BusinessIntelligence #DecisionMaking #RiskWatch #BusinessSuccess #BusinessOpportunities #WorkingTogether #BusinessCollaboration #RiskManagement #RiskAssessment #EnterpriseRiskManagement #EnterpriseRisks

BusinessRiskTV Taking more calculated risks

Emerging trends in business management

Global and local business management trends with BusinessRiskTV.com

Emerging trends in business management debated risk analysed and risk controls reviewed. What emerging trends in business management must you know about today? Consumers and business decision makers have easy access to business intelligence so business leaders need to use business intelligence more in risk management strategy setting to grow faster. Due to the rapidly changing business environment and increased nationalism it may be better to have shorter supply chains. Alternatively restructure your supply chains to embrace new cost saving opportunities in supply.

Spot emerging trends before your competitors to protect your business better and grow business faster

BusinessRiskTV

Fully adopt new technology to react faster and lower business costs. Evolve more business from existing customers by engaging customers more in your business. Redfine they way you do business to do more business.

Emerging Trends in Business Management

Exploring The Future Of Work Trends and Analysing The Risks To Your Business Your Career and Society
Future Of Work Trends

Identify and understand emerging risks better to inform your decision making quicker. Keep up to date with global and local trends in your industry and country. Tap into our risk management experts networks to solve business problems faster and cheaper.

Subscribe to BusinessRiskTV for free alerts bulletins and reviews on emerging trends in business management

Enter code #EmergingTrendsInBusinessManagement

Beat Your Competitors To New Business Growth with BusinessRiskTV

Grow Your Business With Us
Strategy to compete with competitors
Discover How To Beat The Competition In Sales

Promote and market your business on BusinessRiskTV for 12 months

Cheap ways to promote your business

Find out how to promote your business locally and globally. CLICK HERE or email editor@businessrisktv.com entering code #EmergingTrendsInBusinessManagementMarketing

Put your products or services in front of new people already interested in your type of business offering before your competitors do.

Link into your existing online sales process direct from BusinessRiskTV or use our eCommerce solutions to increase your sales cash flow and profit.

Increase the sources of your revenue streams more sustainably. Grow your business faster with BusinessRiskTV.

Emerging Trends In Business Management Directory

  • Want to list your business on our Emerging Trends In Business Management Directory?
  • Are you running any deals discounts or special offers on emerging trends in business management you want more people to know about to grow your business faster?
  • Could you write an advertorial on emerging trends in business management to promote your business products or services whilst informing our readers?

Reach more new customers with BusinessRiskTV.

Northern Powerhouse Risk Management Online Seminars

Click on Register Now or email editor@businessrisktv.com entering code #EmergingTrendsInBusinessManagementDirectory

MarketplacesExhibitions
Save MoneyRisk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

BusinessRiskTV #EmergingTrendsInBusinessManagement #EmergingTrends #EmergingTrendsInManagement #RiskMag #RiskMagazine #RiskManagementMagazine #EmergingRisks #HorizonScanning #RiskTrends #RiskWatch #BusinessIntelligence #BI #SupplyChains #BusinessManagement #EmergingTrendsInBusinessManagementMarketing #EmergingTrendsInBusinessManagementDirectory

BusinessRiskTV Emerging trends in business management

The word on the street on business risk management

How to do a risk assessment of the key threats and opportunities for your business with BusinessRiskTV.com

Understand your business exposure to risks better. Get help to manage business risks better. Network with your peers and risk management experts locally and around the world to help solve your business problems faster. Good business risk management is good business!

  • Improve your business risk management process.
  • Develop a better risk management strategy.
  • Set the right risk management culture for your business.

Identify evaluate and control the risks impacting on your business objectives. Develop practical steps to protect your business and grow business faster with less uncertainty. Understand the risk assessment process better.Tap into free risk management guidance online. Enterprise risk management is a fundamental element of business success and business resilience.

Manage Risk Better

Improve your risk knowledge to solve business problems today and in future

Subscribe to BusinessRiskTV for free alerts bulletins and reviews to your inbox on business risk management

Promote and market your business on BusinessRiskTV for 12 months

Cheap ways to promote your business

Find out how to promote your business locally and globally

MarketplacesExhibitions
Save MoneyRisk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #RiskManagement #RiskAssessment #EnterpriseRiskManagement #RiskManagementTips #RiskManagementTraining

BusinessRiskTV The word on the street on business risk management

Key factors that lead to successful businesses

Why will your business be successful?

Subscribe to BusinessRiskTV for free alerts and bulletins on the latest business threats and opportunities for growth to your inbox

Understand business risks. Explore the key factors that lead to successful business. Apply the relevant risk management measures. Take the risk first before the competition clicks on.

  • Click on Like Button to follow us on your favourite social media App; or subscribe for free enterprise risk management newsletter by emailing editor@businessrisktv.com
Guide To Business Enterprise Risk Management ERM

Risk Appetite and Risk Tolerance enter code #RiskAppetite

There are a number of key factors that led to successful business. Successful business leaders understand that being in business is about managing the risks from change. Unsuccessful business leaders tend to blame their failures on economic climate changes and their successes on their brilliant business management skills!

The UK retail sector is suffering major painful changes. Tens of thousands of jobs have been lost as major retailers collapsed or contracted. Yet the UK retail marketplace has some examples of major retailers bucking this trend blamed on the UK economy by unsuccessful retail business managers.

By applying their risk management knowledge successful businesses can act quicker and with more confidence it will work out

BusinessRiskTV

Not taking risks is not an option for most business leaders. However many risk factors coming together can appear daunting. Enterprise risk management looks at the big picture and helps you identify the steps to a better business in future.

Find out how to improve your chances of business success with BusinessRiskTV. Take calculated risks to help your business grow faster with less uncertainty. Embrace change and the risks to your business.

Enter code #RiskTolerance

What a business risk assessment should include

Business risk assessment elements should fit your business culture. Some people do not like numbers. Some do. Your business risk assessment template should reflect the culture of your organisation.

A business risk assessment is a systematic process that helps organisations identify, evaluate, and prioritise risks that may impact their operations, financial performance, and reputation. It is an essential tool for managing risk and ensuring the long-term viability of a business.

There are several key elements that a business risk assessment should include:

  1. Identifying the risks: The first step in the risk assessment process is to identify the potential risks that the business may face. This can include internal risks, such as operational inefficiencies or employee misconduct, as well as external risks, such as market changes or natural disasters.
  2. Evaluating the risks: Once the risks have been identified, the next step is to evaluate their potential impact on the business. This includes considering the likelihood of each risk occurring, as well as the potential consequences if it does.
  3. Prioritising the risks: After evaluating the risks, the next step is to prioritise them based on their potential impact on the business. This will help the organisation focus its resources on the most significant risks and develop strategies to mitigate them.
  4. Developing risk management strategies: Once the risks have been prioritised, the next step is to develop strategies to mitigate them. This can include implementing control measures to prevent or reduce the likelihood of risks occurring, or transferring the risk to another party through insurance or other means.
  5. Monitoring and reviewing the risks: The risk assessment process is ongoing and should be regularly reviewed and updated to ensure that it remains relevant and effective. This includes monitoring the risks and identifying any new or emerging risks that may have arisen since the last assessment.

In summary, a business risk assessment should include the following key elements:

  • Identifying the risks
  • Evaluating the risks
  • Prioritizing the risks
  • Developing risk management strategies
  • Monitoring and reviewing the risks

Every business faces risks that could be a threat to its success

The business leaders who are better prepared for these risks and have a cost effective risk management plan and business strategy are more likely to be more successful.

Business Risk Assessment

Enterprise Wide Risk Assessment For Faster Business Growth With Best Use Of Business Assets

Develop a suitable risk assessment process to assist with your risk management plan preparation. Review your existing risk management process to ensure it is fit for purpose in a rapidly changing marketplace. Successful entrepreneurs have a good strategic operational and project risk management attitude and business culture that is flexible enough to cope with any economic environment.

MarketplacesExhibitions
DealsRisk Magazine

Factors for successful business

There are numerous factors that can contribute to the success of a business. Here are some key factors that are often considered critical for building and maintaining a successful business:

Clear Vision and Strategy: A successful business requires a clear vision and a well-defined strategy. This includes setting goals, defining the direction of the business, and developing a roadmap to achieve those goals.

Market Research and Understanding Customer Needs: Understanding the market and identifying customer needs are essential for success. Conducting thorough market research, identifying target customers, and tailoring products or services to meet their needs is critical in building a successful business.

Strong Leadership: Effective leadership is crucial for the success of any business. It involves providing direction, making decisions, motivating employees, and fostering a positive work culture. Strong leadership skills help in guiding the business through challenges and achieving the desired outcomes.

Financial Management: Proper financial management, including budgeting, cash flow management, and financial planning, is vital for the long-term success of a business. Sound financial management practices help in ensuring that the business remains financially stable and can weather economic uncertainties.

Quality Products or Services: Delivering high-quality products or services is essential for building a loyal customer base. Providing value to customers and consistently meeting or exceeding their expectations builds trust and helps in retaining customers, which is critical for the success of any business.

Effective Marketing and Branding: Successful businesses understand the importance of effective marketing and branding. Creating a strong brand presence, developing marketing strategies to reach the target audience, and promoting products or services effectively can lead to increased visibility, customer acquisition, and revenue growth.

Innovation and Adaptability: In today’s dynamic business environment, innovation and adaptability are crucial for success. Successful businesses continuously innovate, adapt to changing market trends, and find new ways to stay relevant and competitive in the market.

Efficient Operations and Processes: Streamlining operations and processes can improve efficiency, reduce costs, and enhance customer satisfaction. Implementing effective systems and processes, optimising the supply chain, and leveraging technology can lead to improved productivity and operational excellence.

Talented and Engaged Workforce: A skilled and motivated workforce is vital for the success of any business. Hiring and retaining top talent, providing opportunities for growth and development, fostering a positive work culture, and promoting employee engagement can lead to higher productivity and overall business success.

Customer Relationship Management: Building strong customer relationships is crucial for long-term success. Providing excellent customer service, maintaining open lines of communication, addressing customer feedback, and building customer loyalty are key factors that contribute to the success of a business.
These are some of the key factors that can contribute to the success of a business. However, it’s important to note that success is multifaceted and can vary depending on the industry, market, and individual circumstances. It’s essential to carefully plan, execute, and continuously adapt to changing circumstances to achieve long-term business success.

Strategic Partnerships and Networking: Collaborating with strategic partners and building a strong network can provide valuable opportunities for business growth. Strategic partnerships can help access new markets, share resources, and leverage complementary strengths, while networking can lead to new business leads, partnerships, and valuable industry insights.

Risk Management: Successful businesses recognize the importance of managing risks. This includes identifying and mitigating potential risks, having contingency plans in place, and being prepared to handle unexpected challenges. Effective risk management can help protect the business from potential setbacks and ensure its resilience.

Flexibility and Adaptability: Business environments can change rapidly, and successful businesses are agile and adaptable. Being open to change, willing to pivot when necessary, and embracing innovation can help a business stay ahead of the competition and navigate through uncertainties.

Continuous Learning and Improvement: Successful businesses are always learning and improving. Keeping up with industry trends, staying updated with technology, and seeking feedback from customers and employees can provide valuable insights for making informed decisions and driving continuous improvement.

Strong Customer Focus: Putting the customer at the center of the business is crucial for success. Understanding customer preferences, delivering excellent customer experiences, and building customer loyalty can lead to repeat business, positive word-of-mouth, and a strong brand reputation.

Ethical and Responsible Business Practices: Operating with integrity, practicing ethical business standards, and being socially responsible can build trust and credibility with customers, employees, and other stakeholders. Demonstrating responsible business practices can contribute to long-term success and sustainability.

Resilience and Persistence: Building a successful business is not always easy, and setbacks and failures are inevitable. Successful businesses demonstrate resilience, learn from failures, and persist in the face of challenges. Perseverance, determination, and the ability to bounce back from setbacks are key traits of successful entrepreneurs.

Long-term Planning and Goal-setting: Having a long-term vision and setting realistic goals is important for business success. Long-term planning allows for strategic decision-making, resource allocation, and monitoring progress towards achieving business objectives.

Adapting to Digital Transformation: In today’s digital age, successful businesses embrace digital transformation. This includes leveraging technology for automation, digital marketing, data analysis, and online presence to stay competitive and meet changing customer preferences.

Monitoring and Measuring Key Performance Indicators (KPIs): Successful businesses monitor and measure key performance indicators (KPIs) to track progress, identify areas for improvement, and make data-driven decisions. Regularly analysing KPIs provides insights into the health and performance of the business and helps in making informed decisions.

In conclusion, building and maintaining a successful business requires a combination of various factors. It’s important to have a clear vision, understand the market and customer needs, demonstrate effective leadership, manage finances wisely, deliver quality products or services, market and brand effectively, innovate, and adapt to changing environments. Additionally, building a strong team, managing risks, focusing on customer satisfaction, practicing responsible business ethics, and being resilient and persistent are key factors that contribute to long-term business success.

Discover new ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #Success #DecisionMaking #RiskFactors #SuccessfulBusinesses #BusinessSuccess #RiskTakers #RiskTaking #BusinessLeaders #LeadershipSkills #EnterpriseRiskManagement

BusinessRiskTV Key factors that lead to successful businesses

Ebola Virus Disease Pandemic Risk Review

Reviewing the pandemic risks with BusinessRiskTV.com

Discover more about ebola virus. Identify ways to prevent ebola contraction and spread. Review current ebola virus pandemic risk.

The World Health Organisation WHO declared the Democratic Republic of Congos ebola outbreak as an international health emergency

BusinessRiskTV

Those most at risk from ebola outbreaks tend to be health care workers caring for ebola victims.

Subscribe to BusinessRiskTV Ebola Virus Risk Alerts and Bulletins

[ninja_forms id=1]

Enter code #EbolaVirusDisease

19th July 2019 Ebola Outbreak Crisis Worsens

The risk of global pandemic is very low but locally the number of deaths continues to climb. 1600 people have been killed by ebola virus in the DR Congo.

11000 people died in last ebola epidemic in West Africa from 2014 to 2016

BusinessRiskTV

The current large ebola outbreak has not yet resulted in restrictions on travel or trade but the rate of deaths is accelerating.

A further factor in the spread of ebola in the region is the attacks on healthcare workers. This makes it even more likely that neighbouring countries could be seriously affected by the outbreak in the DR Congo.

Recommended global risk management and pandemic risk articles and videos

AcademyMarketplaces
Risk MagazineExhibitions

#BusinessRiskTV #PandemicRisks #EbolaVirus

BusinessRiskTV Ebola Virus Disease News Headlines

Business Risk Strategy Design and Implementation

Develop the best business risk management strategy for your business with BusinessRiskTV

Develop the best business risk strategy. Understand how to improve business performance. Get business risk management strategy tips and support.

Enter code #RiskStrategy

Subscribe to BusinessRiskTV for free alerts and bulletins on business risk management strategy development

Enter code #RiskStrategy

AcademyMarketplaces
ExhibitionsRisk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

BusinessRiskTV Business Risk Strategy Tips Advice and Training

UK Online What You Need To Know About Business Risks In UK

What are the top risks for UK businesses with BusinessRiskTV

Get the latest business and economy news for free

Connect and collaborate in business. Grow your business with less uncertainty. Find the answer to your business questions quicker.

Enter code #UKonline

Subscribe to UK Online for free for UK business and economy news views and reviews bulletins

Keep up to date with business risk management. Free news alerts and bulletins to your email inbox.

Promote and market your business on BusinessRiskTV for 12 months

Cheap ways to promote your business
Find out how to promote your business locally and globally

Recommended UK business and economy articles and videos

What are business and economy bloggers saying today? What do you need to know today? Get help to manage your business better. Improve business performance.

Breaking Business News and Business Risk Management Features
BusinessRiskTV Top Business News

Pick up tips advice and support to make better business decisions. Network with business leaders to overcome barriers to business quicker and cheaper. Do not reinvent the wheel!

Marketplaces Exhibitions
Deals Risk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

#UKonline #UKbusiness #UKeconomy #UKmarketplace

UK Online What You Need To Know About Business Risks In UK

Business Risk News BusinessRiskTV Risk Management Articles and Videos

Risk and insurance news on BusinessRiskTV

Subscribe to BusinessRiskTV business risk management news bulletin to inform your decision-making.

BusinessRiskTV.com Free Subscription Online
Subscribe to BusinessRiskTV.com for free

Why is risk management in the news today? Latest business risk management news headlines opinions and business reviews. Top business videos live and on demand. Pick up tips advice and support to inform your business decision making process. Network with key business risk management thought leaders around the world.

Subscribe to BusinessRiskTV Business Risk News for free to receive alerts and bulletins

Breaking News on BusinessRiskTV.com Online Live News Alerts
BusinessRiskTV News Opinions Reviews

Enter code #BusinessRiskNews

Promote and market your business on BusinessRiskTV for 12 months

Cheap ways to promote your business

Put your products or services in front of new people already interested in your type of business offering before your competitors do.

Find out how to promote your business locally and globally. CLICK HERE or email editor@businessrisktv.com entering code #Marketing

Link into your existing online sales process direct from BusinessRiskTV or use our eCommerce solutions to increase your sales cash flow and profit.

Increase the sources of your revenue streams more sustainably. Grow your business faster with BusinessRiskTV.

Business Risk News : if your objective is freedom and success you will need objectivity, clarity and independence of thought from your news source to discover freedom and success in business. The wider news media is useless to you as it has its own agenda. If your recognise that this is the real truth and understand why that impacts on your ability to make your business a success then you will want to come back to BusinessRiskTV Risk News more often for help to inform your better decision making process to achieve success in business with less uncertainty. Don’t let yourself be brainwashed by the agenda of others not aligned to your business objectives.

Academy Marketplaces
Exhibitions Risk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #RiskNews #RiskManagementNews #RiskManagementReviews #RiskManagementOpinion #TopBusinessVideos #BusinessRiskNews #Marketing

Business Risk News BusinessRiskTV Risk Management Articles and Videos

Take Back Control Of Your Future Business Success

Learn how to regain control of your business risks with BusinessRiskTV

Whether you accept avoid transfer mitigate risks or exploit risk opportunities is not straight forward. Find new ways to improve the culture of risk management to boost business performance. Increase your business success.

  • How do you manage risks?
  • How can your management of risks be improved?
  • What risks should you take and which should you not tolerate?

Understand the risk management process better. Discover the best risk management practices. Improve your risk management with better risk management solutions.

Manage Risks Better

Sometimes we have to accept the risks our businesses face to achieve our goals. Taking no action to control the risks does not mean you have not managed the risk. It means you have identified and assessed it and proactively choose to accept it as the risk is within your risk tolerance and appetite for risk.

The other extreme is that you avoid the risk identified. The risk is beyond your risk tolerance and appetite for risk to pursuance of your business objectives.

Developing a balanced risk management action plan is not easy but it should be simple to work well.

BusinessRiskTV

Taking the right steps to manage risks will boost your business performance with less uncertainty.

  • Build your business resilience
  • Create more value
  • Advance your risk management capability

There is always room for improvement. Better risk management will mean your business is better prepared for the future. Improve performance regardless of business environment.

Whether you are trying to do something new or just want to find new ways to manage existing risks join our 360 Business Club.

Advice for improving risk management with BusinessRiskTV
Join our 360 Business Club to protect your business better and grow faster with less uncertainty impacting on your business objectives. CLICK HERE or email editor@businessrisktv.com entering code #360BusinessClub

Take your business to the next level with our 360 Business Club.

Subscribe to BusinessRiskTV 360 Business Club

Complete and submit the form below and quote code #360CLUB

AcademyMarketplaces
ExhibitionsRisk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

BusinessRiskTV Take Back Control Of Your Future Business Success

Financial services risk management approach that creates business and economic opportunities BusinessRiskTV Strategic Risk In Financial Services

Improving strategic risk management withing financial services industry in UK with BusinessRiskTV

Subscribe to BusinessRiskTV for free today

Strategic risk decision making in financial services industry is not complicated but it is complex. Reduce the complexity to what matters to your business in the financial services sector.

  • Become more efficient and productive
  • Build greater business resilience
  • Improve business performance

Failing to be innovative and creative in the financial services sector may place your business at a competitive disadvantage. However innovation and creativity brings added risk. Is that added risk with it? Enterprise risk management ERM approach will help you decide.

In addition ERM risk based decision making will help you protect your financial services business better. Align your business strategy with best practice risk management tools and techniques to reduce strategic operational and project risks.

Regulatory compliance increased investor engagement and expectations and increasingly volatile geopolitical risks makes investing for the future and management of investment risks harder

BusinessRiskTV

The future of financial services industry risk management is also changing with artificial intelligence divergent regulatory controls and splintering risk culture ambitions driving changes in practice.

Keep up to date with best risk management tools and techniques to improve your business decision making. The financial financial crisis is beginning. We just do not know where it started and what we are doing wrong. However being prepared for the next financial crisis should be part of a holistic enterprise risk management approach.

Chances are that fintech will play a role in the next financial crisis. Technology risks are a key risk factor for business growth and disaster for financial services companies in particular.

Lack of need to control risks will also play a role in the next financial crisis. The financial services industry has found it near impossible to manage its own risks without regulatory control. Dissipation in regulatory control will precipitate the financial services industry lunging over the cliff.

The fact that the financial services sector has still not recovered from the last financial crisis is another reason that another financial crisis will occur. Italian Chinese and Indian banks are in particular bursting at the seems with near unmanageable debt levels. Add to that boiling frothing pot of junk political instability in Europe Asia and Americas then you have a perfect storm waiting to be unleashed.

Should we withdraw from business or investing? Of course not. It has always been thus. It has always been about the survival of the fittest. However what has changed is that there is increased realisation that the fittest are those businesses and investors who invest in socially responsible investing. Environmental social and governance risk factors are at play. The strongest are the ones who embrace this philosophy.

A holistic enterprise risk management approach to business management and investing is the future. If you are waiting to look back and acknowledge that with hindsight you will be one who suffers most from the next financial crisis. You may not survive the long term. If you are not looking to the long term then good luck to you. You might get lucky. If you are looking for long term sustainability get on the holistic enterprise risk management boat today. Create long term value through enterprise risk management today not tomorrow.

Helping to connect key business leaders online

Finding the latest best business practices can be time consuming or unfruitful. We make life and business easier and better.

Searching for what you need to inform your business decision making is free. Come back often to find the best of business quickly. Pick up the latest lifestyle and business risk management news headlines opinions debate and business reviews.

Are you a business owner or manager in the financial services industry?

Business leaders do not always have the marketing budget to promote their business. We provide a range of online marketing options for businesses to fit most budgets so you can promote your business products or services for longer.

Sponsor Strategic Risk In Financial Services for 12 months

Alternatively CLICK HERE to find other ways of promoting your business more cost effectively.

Globally Empty Office Buildings and Commercial Property Creating Debt Collapse, Systemic Threat to Banking System Worldwide

The COVID-19 pandemic and central banks response – overprinting of money out of thin air – has had a devastating impact on the global economy, and nowhere has this been more evident than in the commercial real estate sector. As businesses have been forced to close or operate remotely, millions of square feet of office space have been vacated, leaving office buildings empty around the world.

This has led to a sharp decline in property values, and many commercial real estate owners are now facing significant financial losses. In some cases, these losses have become so severe that they have forced property owners to default on their loans, which could have a ripple effect throughout the global banking system.

Who Has the Most Exposure to Commercial Real Estate?

The financial institutions that have the most exposure to commercial real estate are those that specialise in lending to businesses and developers. These institutions include commercial banks, investment banks, regional banks in USA and insurance companies.

According to a recent report by the International Monetary Fund, commercial banks worldwide have about $20 trillion in outstanding loans to commercial real estate borrowers. This represents about 10% of all bank lending globally.

Investment banks and insurance companies also have significant exposure to commercial real estate. Investment banks, for example, often underwrite and market commercial real estate bonds, which are a type of debt security that is backed by the income generated from rental properties. Insurance companies, on the other hand, often invest in commercial real estate through real estate investment trusts (REITs), which are companies that own and operate income-producing properties.

Are Banks in Danger?

The sharp decline in commercial real estate values has raised concerns that banks could be in danger of suffering significant losses on their loans to commercial real estate borrowers. In some cases, these losses could be so severe that they could force banks to default on their own debts, which could lead to a systemic financial crisis.

However, it is important to note that banks have a variety of tools at their disposal to manage their exposure to commercial real estate risk. For example, banks can sell off their commercial real estate loans to other investors, or they can take steps to restructure the terms of these loans. At the same time if the sea level is going down for all banks in real estate debt crisis will there be enough saviours?

In addition, the government can also play a role in helping to stabilise the commercial real estate market. For example, the government can provide financial assistance to banks that are struggling with commercial real estate losses, or it can provide tax breaks to businesses that are considering moving back into office space. At the same time this is inflationary and may result in even higher interest rates – problem delayed but worsened thereby extending and increasing length of recession creating depression.

How Many Office Buildings Are Empty in the US?

According to a recent survey by the commercial real estate firm CBRE, about 15% of office space in the United States is currently vacant. This represents about 250 million square feet of empty office space.

The vacancy rate is highest in major cities such as New York, San Francisco, and Los Angeles. In these cities, the vacancy rate is often above 20%.

The vacancy rate is also high in some smaller cities and towns. For example, the vacancy rate in the city of Detroit is currently over 30%.

These, official, vacancy rates seem lower than real levels other agencies produce and anecdotally.

Why Are the Banks in Trouble?

The banks are in trouble because they have lent too much money to commercial real estate borrowers. When these borrowers default on their loans, the banks are left holding the bag.

The banks are also in trouble because the value of their commercial real estate assets has declined. This decline in value has made it more difficult for the banks to sell these assets, and it has also reduced the amount of collateral that they have available to secure their loans.

The banks are also facing increased competition from non-bank lenders, such as private equity firms and hedge funds. These non-bank lenders are often willing to lend money to commercial real estate borrowers at lower interest rates than the banks.

Conclusion

The global pandemic has had a devastating impact on the commercial real estate sector, and this has led to significant financial losses for banks and other financial institutions. The situation is likely to get worse before it gets better, as more and more businesses continue to operate remotely. If it gets worse it will be a very long time – decades – before it gets better!

The government will need to play a role in helping to stabilise the commercial real estate market, and banks will need to take steps to manage their exposure to commercial real estate risk. If these steps are not taken, the global banking system could be in danger of a systemic crisis.

Recommended articles and videos

https://businessrisktv.com/forums/financial-services-industry-risk-forum/
https://businessrisktv.com/risk-insight-business-intelligence/3-lines-of-defence-risk-management-model/
https://businessrisktv.com/business-tips/asset-management-regulatory-requirements-uk-businessrisktv-wealth-management-key-risks/
https://businessrisktv.com/business-tips/individual-accountability-regime-conduct-rules/
https://businessrisktv.com/implementation-and-operation-of-risk-management-and-conduct-risk-frameworks-businessrisktv/
https://businessrisktv.com/suggestions-to-improve-risk-culture-in-banking-businessrisktv-fca-risk-culture-review/
https://businessrisktv.com/business-tips/esg-risk-analysis-responsible-investing/
Academy Marketplaces
Exhibitions Risk Magazine

BusinessRiskTV Financial Services Industry Magazine

Managing Risk in Financial Services

Managing Risk in the Ever-Evolving Financial Services Industry

The financial services industry is a complex and dynamic sector that plays a vital role in the global economy. It encompasses a wide range of activities, including banking, insurance, investment management, and more. However, with the constant changes and uncertainties in the business landscape, managing risk has become a critical aspect of the financial services industry. In this article, we will explore the challenges and best practices of managing risk in the ever-evolving financial services industry.

The Changing Landscape of the Financial Services Industry

The financial services industry has gone through significant changes over the years, driven by various factors such as technological advancements, regulatory reforms, economic fluctuations, and changing customer preferences. These changes have brought new opportunities and challenges for businesses operating in this industry.

One of the significant changes in the financial services industry is the increasing reliance on technology. The digital revolution has transformed the way financial services are delivered and consumed. Fintech companies have emerged, leveraging technology to disrupt traditional financial services providers. This has resulted in increased competition and the need for traditional financial institutions to adapt and innovate to stay relevant.

Another change in the financial services industry is the evolving regulatory landscape. Governments and regulatory bodies around the world have implemented stringent regulations to safeguard consumers and ensure financial stability. These regulations, such as the Dodd-Frank Act in the United States and the MiFID II directive in the European Union, have increased compliance requirements for financial services firms. Non-compliance can result in severe penalties and reputational damage, making effective risk management essential.

Economic fluctuations also impact the financial services industry. Economic downturns can lead to increased credit risk, market volatility, and liquidity challenges, while economic upturns can present growth opportunities. As the global economy becomes increasingly interconnected, events in one part of the world can have ripple effects on financial markets globally, making risk management more complex and critical.

Lastly, changing customer preferences and behaviors have also impacted the financial services industry. Customers now demand personalized and convenient financial services, with a focus on transparency and trust. This has led to a shift in business models, with a greater emphasis on customer-centricity and digital engagement. Firms need to understand customer preferences and manage reputational risk to maintain customer trust and loyalty.

Challenges in Risk Management in the Financial Services Industry

The evolving landscape of the financial services industry has brought about several challenges in managing risk effectively. Some of the significant challenges include:

Increasing Complexity: The financial services industry is highly complex, with numerous products, services, and processes. Risk managers need to understand the intricacies of various financial instruments, business models, and regulatory requirements to identify and manage risks effectively.

Changing Regulations: The regulatory landscape is constantly evolving, with new regulations being introduced and existing ones amended. Financial services firms need to stay abreast of these changes and ensure compliance, which requires significant resources and expertise.

Cybersecurity Risks: The increasing reliance on technology has also exposed the financial services industry to cybersecurity risks. Cyber threats, such as data breaches and ransomware attacks, can result in financial losses, reputational damage, and regulatory penalties.

Geopolitical Risks: Geopolitical events, such as trade disputes, political instability, and sanctions, can have significant impacts on the financial services industry. These events can affect global markets, currencies, and investment portfolios, leading to increased volatility and risk exposure.

Reputation Risk: Reputation is crucial in the financial services industry, and any damage to reputation can have severe consequences. Negative public perception, loss of customer trust, and regulatory scrutiny can all result in significant financial and operational impacts.

Operational Risks: The complex and interconnected nature of the financial services industry also presents operational risks. Operational failures, such as system outages, processing errors, and human errors, can disrupt business operations, cause financial losses, and harm reputation.

Risk of Financial Crime: Financial services firms are also exposed to risks related to financial crime, including money laundering, fraud, and corruption. These risks can arise from internal or external sources and can result in regulatory penalties, legal liabilities, and reputational damage.

Risk from Emerging Technologies: The rapid pace of technological advancements, such as artificial intelligence, blockchain, and cryptocurrency, presents both opportunities and risks for the financial services industry. Firms need to understand the risks associated with emerging technologies and implement effective risk management strategies to mitigate them.

Best Practices for Managing Risk in the Financial Services Industry

Given the challenges and complexities of managing risk in the financial services industry, it is essential for firms to adopt best practices to effectively mitigate risks. Here are some key best practices for managing risk in the financial services industry:

Develop a Robust Risk Management Framework: Financial services firms should establish a comprehensive risk management framework that includes risk identification, assessment, mitigation, monitoring, and reporting. This framework should be integrated into the firm’s overall strategy, operations, and decision-making processes.

Embrace a Risk Culture: Establishing a strong risk culture is critical for effective risk management. It involves fostering a culture where risk awareness and accountability are embedded in the organisation’s values, behaviours, and practices. This includes promoting open communication, risk transparency, and learning from mistakes.

Stay Abreast of Regulatory Changes: The financial services industry is heavily regulated, and firms need to stay updated with the latest regulatory changes that impact their operations. This includes understanding the implications of regulatory changes, ensuring compliance, and engaging with regulators proactively.

Enhance Cybersecurity Measures: Given the increasing cybersecurity risks, financial services firms should implement robust cybersecurity measures to protect their systems, data, and customer information. This includes regular cybersecurity assessments, employee training, and incident response plans.

Diversify Risk Management Strategies: Financial services firms should adopt a diversified approach to risk management. This includes diversifying investments, customers, and markets to reduce concentration risk. It also involves using risk transfer mechanisms such as insurance and derivatives to mitigate risks.

Conduct Comprehensive Due Diligence: Financial services firms should conduct comprehensive due diligence before entering into any business relationships, such as partnerships, acquisitions, or investments. This includes assessing the financial stability, reputation, and compliance of potential business partners to mitigate counterparty risk.

Implement Robust Compliance Programs: Compliance is a critical aspect of risk management in the financial services industry. Firms should establish robust compliance programs that include policies, procedures, and controls to ensure compliance with applicable laws, regulations, and internal policies.

Invest in Technology and Data Analytics: Technology and data analytics can play a significant role in enhancing risk management in the financial services industry. Firms should invest in advanced technologies, such as risk management software, data analytics tools, and machine learning algorithms, to identify, assess, and monitor risks effectively.

Continuously Monitor and Update Risk Management Strategies: Risk management is an ongoing process, and firms should continuously monitor and update their risk management strategies to adapt to changing business and market conditions. This includes conducting regular risk assessments, evaluating the effectiveness of risk mitigation measures, and making necessary adjustments as needed.

As the financial services industry continues to evolve, managing risk has become more critical than ever. Firms operating in this industry face various challenges, including increasing complexity, changing regulations, cybersecurity risks, geopolitical risks, reputation risk, operational risks, risk from emerging technologies, and risk from financial crime. However, by adopting best practices such as developing a robust risk management framework, embracing a risk culture, staying abreast of regulatory changes, enhancing cybersecurity measures, diversifying risk management strategies, conducting comprehensive due diligence, implementing robust compliance programs, investing in technology and data analytics, and continuously monitoring and updating risk management strategies, financial services firms can effectively mitigate risks and safeguard their operations, reputation, and financial stability.

It is crucial for financial services firms to recognize that risk management is not a one-time activity but an ongoing process that requires constant attention and adaptation. By proactively identifying, assessing, and mitigating risks, firms can reduce the likelihood and impact of potential risk events and ensure their long-term sustainability.

In addition, fostering a strong risk culture within the organisation is essential for effective risk management. This involves creating an environment where risk awareness and accountability are valued, and employees at all levels are encouraged to report risks and concerns without fear of reprisal. A robust risk culture promotes open communication, transparency, and a commitment to continuous learning and improvement.

Furthermore, leveraging technology and data analytics can greatly enhance risk management efforts in the financial services industry. Advanced technologies, such as risk management software, data analytics tools, and machine learning algorithms, can enable firms to identify patterns, trends, and anomalies in vast amounts of data, allowing for more informed risk assessments and timely risk mitigation actions.

Lastly, financial services firms should stay updated with the latest regulatory changes and engage with regulators proactively. Regulatory requirements are constantly evolving, and firms need to ensure compliance with applicable laws and regulations to avoid penalties, legal liabilities, and reputational damage. Regular communication and collaboration with regulators can help firms understand the implications of regulatory changes and proactively address any potential compliance gaps.

In conclusion, managing risk is a critical aspect of operating in the financial services industry. With the increasing complexity and evolving landscape of this industry, firms need to adopt a proactive and comprehensive approach to risk management. By developing a robust risk management framework, fostering a strong risk culture, staying updated with regulatory changes, enhancing cybersecurity measures, diversifying risk management strategies, conducting comprehensive due diligence, implementing robust compliance programs, investing in technology and data analytics, and continuously monitoring and updating risk management strategies, financial services firms can effectively mitigate risks and ensure their long-term success. It is imperative for financial services firms to prioritise risk management and make it an integral part of their strategic planning and decision-making processes. By doing so, they can safeguard their operations, protect their reputation, and maintain the trust of their customers and stakeholders in the ever-changing landscape of the financial services industry.


BusinessRiskTV Strategic Risk In Financial Services

Understanding risk tolerance and delivering risk appetite BusinessRiskTV Risk Appetite and Risk Tolerance

Learn how to calculate risk tolerance and risk appetite with BusinessRiskTV

Managing your risk appetite and risk tolerance better

What level and nature of risk are you able and prepared to take to achieve your business objectives. Define the appetite for each type of risk to deliver your strategic objectives.

Determine achievable strategic business objectives deliver them operationally and complete better project outcomes

Set the priorities right for your business risk management culture. Develop and deliver your risk appetite.

Guide To Business Enterprise Risk Management ERM
Risk Appetite and Risk Tolerance. CLICK HERE or email editor@businessrisktv.com for more information

Connecting business leaders

Finding the latest best business practices can be time consuming or unfruitful. We make life and business easier and better.

Searching for what you need to inform your business decision making is free. Come back often to find the best of business. Pick up the latest business risk management news headlines opinions debate and business reviews.

Subscribe to BusinessRiskTV for free

Manage risks within your business risk tolerance and risk appetite. Deliver increased enterprise value.

CLICK HERE to receive free alerts to latest risk management news headlines opinions and reviews

Do you own or manage a business?

CLICK HERE to discover innovative ways to promote and market your business

Business leaders do not always have the marketing budget to promote their business. We provide a range of online marketing options for businesses to fit most budgets so you can promote your business products or services for longer.

Become Risk Appetite and Risk Tolerance Post sole sponsor for 12 months

Sponsor Risk Appetite and Risk Tolerance Post for 12 months
Alternatively CLICK HERE to find other ways of promoting your business more cost effectively.


Recommended articles and videos

Academy Deals
Marketplaces Leaders

#BusinessRiskTV #RiskTolerance #RiskAppetite #RiskCulture

BusinessRiskTV Risk Appetite and Risk Tolerance

Embrace the unexpected and make the best of it with BusinessRiskTV

Embracing business risks to achieve more in business with BusinessRiskTV.com

Being in business can be tough

Strong businesses develop a positive risk management thinking strategy. Find the best in any business environment.

Stop looking for things and people to blame for your poor business performance. Research the risks impacting upon your business objectives. Lessen uncertainty. Create positive change in your business.

Learn how to allow and plan for the unexpected. Embrace all risks in business

Proactive Risk Based Approach To Business Management

Proactively develop your own risk awareness impacting on your business objectives. Embrace the changing business environment and internal risk factors. Get really good at manage enterprise risks to set clearer path to success.

  • Take control of your future.
  • Change what you do to achieve more with less uncertainty.
  • Embrace all your responsibilities and behave responsibly.
  • Make things happen for your business.
  • Focus on what really matters for your business.
  • Set a clear path and arrive at where you want to get to more confidently

Strong businesses adopt a proactive risk management approach with clear risk management strategy for success. Develop a more stable business with better relationships with all business stakeholders. Be prepared to take on best business opportunities.

What do you want your business to achieve and what are you doing to make sure you are successful?

What risks are you controlling? What enterprise risks should you not control? Manage the risks you can realistically influence the likelihood of and impact on business objectives should the risk materialise.

Strong businesses assess the risks then implement a well thought out risk management plan. Take some time to analyse different options and identifiable consequences on your business objectives but do not procrastinate. Take risk based business intelligent decisions quicker with more confidence.

Dream Bigger And Implement A New Reality For Your Business

Do not bury your head in the sand or fail to take calculated risks to improve your business performance. Be better prepared to aim higher with stronger business resilience to overcome obstacles. Focus your limited resources on more achievable business goals. Take risks with more confidence. We are not advocating recklessness. Be responsible and consciously embrace the unexpected.

Set your course to greater success with help from us and our collaborative business partners

Just because your industry or business sector or country is under the cosh does not mean your business needs to suffer too.

  1. Grow faster despite the adversity you face in business.
  2. Rise to the challenge.
  3. Overcome obstacles in the way of your business.
  4. Turn business threats into opportunities or mitigate the threats to your business.
  5. Seize new business development options.

Create a more proactive flexible reactive strategy to adjust your business to navigate all possibilities. Think and plan bigger!

Subscribe to BusinessRiskTV to make the best of risks

Reduce the impact of the business environment on your business objectives. Take control of the things you can control. Focus your business assets on positive risk management. Invest in business improvement. Learn from other business leaders mistakes. Stop trying to reinvent the wheel and apply best business practices to your business developed by others.

CLICK HERE to receive alerts to latest business risk management news headlines opinions and reviews

Do you own or manage a business?

Review your past but more importantly plan for a better future for your business. Even if your past business performance has been great could you do better?

Collaborate to achieve more together

Whilst we work in a highly competitive marketplace we do not need to fight with everybody for new business! Strengthen your relationship with like minded business leaders around the world to grow your business faster.

Have the courage to reach out to others who could help you whilst you help them

Become more confident in your future. Focus your resources on what really matters for your business success.

  • Accept that others need to make a profit too.
  • Celebrate and promote each others business offerings
  • Help others to detect analysis and manage enterprise risks better

Do not just live in our own business bubble. Find the people who complement your business or even fill holes in your business structure. Build healthy business relationships with help from BusinessRiskTV. Care for your new business partners and seek help in return to become more successful. Find time for others you can help to receive help.

CLICK HERE to discover how to promote and market your business

Recommended articles and videos

Academy Deals
Marketplaces Exhibitions

BusinessRiskTV Embrace The Unexpected

How To Manage Risk In Business BusinessRiskTV Manage Business Risks Better

Business risk management with BusinessRiskTV.com

Identify evaluate and manage business risks better. Discover management of risks tools and techniques. Analyse evaluate and control internal and external risk factors. Tips and advice on the best ways for a business to manage risk impacting on business objectives.

Why is business risk management important? Protect and grow your business faster with less uncertainty impacting on business objectives

Learn how to manage enterprise risks better. Inform your risk management process. Improve your risk management system. Read our guides to business risk management.

Enterprise Risk Management Training Workshops Online

Enterprise Risk Management Training: Looking to boost your business growth? Want to protect your business for significant losses? Think your business could do better with existing resources?

Connecting Business Leaders Locally and Globally

Online Networking Business
Get connected on BusinessRiskTV.com

More Connected With BusinessRiskTV: Want to learn from others business mistakes or successes? Looking to use tried and tested business plans for business growth and business protection? Need an easily accessible forum to learn how to improve your business performance?

Finding the latest best risk management products and services can be time consuming or unfruitful. We make easier.

Searching for what you need to inform your business decision making process is free. Come back often to find the best risk management products and services. Pick up the business risk management news headlines opinions debate and business reviews.

Subscribe to BusinessRiskTV for free to inform your business decision making

Business Riskwatch
BusinessRiskTV Business Risk Watch

Be better prepared and more cost effectively manage business risks. Treat risks to your business to achieve more with less uncertainty.

Risk Management Services and Products
Enterprise Risk Management Services On BusinessRiskTV

Help others to manage common business risks better.

Become Manage Business Risks Better sole sponsor for 12 months

Business leaders do not always have the marketing budget to promote their business. We provide a range of online marketing options for businesses to fit most budgets so you can promote your business products or services for longer.

Sponsor Manage Business Risks Better for 12 months

CLICK HERE to find other ways of promoting your business more cost effectively.

Risk Management Magazine
Academy Risk Magazine
Marketplaces Exhibitions
Manage Business Risks More Confidently with BusinessRiskTV

BusinessRiskTV Manage Business Risks Better

Improve Identification Opportunities and Threats BusinessRiskTV

Enterprise risk management analysis with BusinessRiskTV

How to identify and analyse enterprise opportunities and threats

Improve your identification and analysis of business opportunities and threats. Subject your business processes to better risk identification and analysis to boost your business performance.

Unlock the secrets of successful business risk management: Sign up for our ongoing risk management workshops today!

  • Click on button to find ways to contact us online via your preferred social media App; or email editor@businessrisktv.com


Risk Magazine
Business Risk Management Magazine Free Subscription

Use your business strengths to mitigate the threats your business faces. Reduce your weaknesses to control the threats to your business objectives. Seize new business opportunities to build your business resilience.

How to protect your business
Find out how to protect your business better and build business resilience with BusinessRiskTV

Subscribe for free to BusinessRiskTV to follow updates and highlights of articles and workshops on risk identification and analysis

Use enterprise risk identification and analysis to help you grow your business with less uncertainty.

  • Enhance what you are doing well for greater returns on your investment of time and money.
  • Identify new opportunities for your business that you are currently missing or failing to capitalise upon.
  • Control the risks holding your business development back.

Recognise that you do have opportunities to improve your business and what you need to do to make them work well regardless of the business or economic environment.

SWOT Analysis How To Identify Opportunities Threats To Business
Subscribe for free to BusinessRiskTV to follow updates and highlights of articles and workshops on risk identification and analysis
Marketplaces Exhibitions
Cost Reduction Risk Magazine

Create a business risk management plan after identifying key threats and opportunities for your business: PESTLE example

A business risk management plan for a business leader in the UK could include the following:

  1. Political risks:
  • Monitor changes in government policies and regulations that may affect the business
  • Assess the potential impact of political instability on the company’s operations and supply chain
  • Develop contingency plans for disruptions caused by political events
  1. Economic risks:
  • Monitor economic indicators such as GDP growth, inflation, and interest rates
  • Assess the potential impact of economic downturns on the company’s revenue and profitability
  • Develop strategies to mitigate the effects of economic fluctuations on the business
  1. Social risks:
  • Monitor changes in consumer behavior and preferences
  • Assess the potential impact of social trends on the company’s products and services
  • Develop strategies to adapt to changes in consumer demand
  1. Technological risks:
  • Monitor advances in technology that may disrupt the company’s business model
  • Assess the potential impact of technological innovations on the company’s competitiveness
  • Invest in research and development to stay ahead of technological changes
  1. Legal risks:
  • Monitor changes in laws and regulations that may affect the business
  • Assess the potential impact of legal changes on the company’s operations and compliance costs
  • Develop strategies to mitigate legal risks, such as insurance or implementing compliance programs
  1. Environmental risks:
  • Monitor changes in environmental regulations and standards
  • Assess the potential impact of environmental factors on the company’s operations and supply chain
  • Develop strategies to mitigate environmental risks, such as implementing sustainable practices or investing in renewable energy.

Note: PESTLE Analysis is a framework for assessing the external factors that may affect a business. It is a useful tool for identifying potential risks and opportunities for a business.

PESTLE BUSINESS RISK PLAN

Risk Type Key Considerations Potential Impact Mitigation Strategies
Political risks Changes in government policies and regulations Disruptions to operations and supply chain Monitor political developments, develop contingency plans
Economic risks Economic indicators such as GDP growth, inflation, and interest rates Reduced revenue and profitability Monitor economic indicators, develop strategies to mitigate effects of economic fluctuations
Social risks Changes in consumer behavior and preferences Reduced demand for products and services Monitor social trends, develop strategies to adapt to changes in consumer demand
Technological risks Advances in technology that may disrupt business model Loss of competitiveness Monitor technological developments, invest in R&D to stay ahead of changes
Legal risks Changes in laws and regulations Increased compliance costs and legal liabilities Monitor legal developments, implement compliance programs and insurance
Environmental risks Changes in environmental regulations and standards Negative impact on operations and supply chain Monitor environmental developments, implement sustainable practices and invest in renewable energy.
PESTLE BUSINESS RISK PLAN

#BusinessRiskTV #RiskAnalysis #PESTLE

Discover new ways to protect and grow your business with BusinessRiskTV

BusinessRiskTV Improve Identification of Opportunities and Threats

Failure Of Governance

Poor corporate governance endangers the existence and success of businesses

Learn how to improve the way you do things in business

Looking at the costs of failure of governance. Good governance can be expensive but not compare to the cost of governance failure.


The risk of enterprise failure increases with inadequate governance risk and compliance processes

There are many examples of the biggest firms in the world collapsing due to bad risk management practices. Good corporate governance risk and compliance systems build business resilience and can improve business performance.

Corporate Governance Failure
Subscribe to BusinessRiskTV for latest news headlines opinions risk analysis and reviews of success and failure in business

Subscribe to BusinessRiskTV for latest news headlines opinions risk analysis and reviews of success and failure in business


Managing Business Rules

There are several techniques that can be useful for managing business rules in an organisation. Here are some recommendations:

Documenting business rules: One of the most important techniques for managing business rules is to document them in a clear and concise manner. This can include using a variety of formats such as decision tables, flowcharts, and natural language descriptions.

Centralising business rules: To avoid inconsistencies and duplication of effort, it is advisable to centralise the management of business rules. This can be done using a dedicated software tool or a repository that stores the rules and makes them accessible to relevant stakeholders.

Version control: It is crucial to keep track of changes to business rules over time, especially when multiple stakeholders are involved. Version control techniques such as branching and merging can help in managing changes to business rules.

Testing and validation: Business rules should be tested and validated thoroughly to ensure their accuracy and effectiveness. This can be done using a variety of techniques such as unit testing, integration testing, and user acceptance testing.

Auditing and monitoring: Regular auditing and monitoring of business rules can help to identify any potential issues or areas for improvement. This can be done using automated tools or through manual reviews.

Governance and ownership: Establishing clear governance and ownership of business rules is essential to ensure that they are being managed effectively. This can include assigning ownership to specific individuals or teams and establishing processes for reviewing and approving changes to business rules.

By following these techniques, organisations can effectively manage their business rules and ensure that they are aligned with their business objectives and regulatory requirements.

#BusinessRiskTV #FailureOfGovernance

BusinessRiskTV Failure Of Governance

News Headlines Breaking Stories Latest Updates Opinions Analysis

Up to date business news coverage broadcast online. Live news updates headlines pictures video analysis and comment from BusinessRiskTV.

Visit BusinessRiskTV News for latest news breaking news videos and feature stories

Subscribe to BusinessRiskTV News for free for latest news breaking news videos and feature stories

Find the best local and global news stories opinions pictures and videos on business risk events.

BusinessRiskTV.com Free Subscription Online
Subscribe to BusinessRiskTV News for free for latest news breaking news videos and feature stories

News Opinions and Reviews Live Or OnDemand

Jeffery Epstein

BusinessRiskTV News Headlines Breaking Stories Latest Updates Opinions Analysis

What You Need To Know About Business and Economy Today

Discover the best and worst of business and the economy. Get the latest business and economy news headlines opinions and reviews with BusinessRiskTV risk experts. Save money and time.

Subscribe to BusinessRiskTV for free alerts and bulletins

[ninja_forms id=1]

Enter code #WhatYouNeedToKnowToday

The best of BusinessRiskTV delivered daily

Things to know about business. There are some things you need to know about business or the global economy today. Read or watch business news opinions debate reviews and training workshops to understand business risks better

  • Groundbreaking business leaders share their opinions
  • Tectonic changes in the business environment you need to know more about
  • Tumultuous corporate risk events that may shake your country or industry

Instead of quivering about the risks your business face or worse burying your head in the sand about the risk exposure you really have tune into BusinessRiskTV.

Want to receive alerts bulletins and videos in your inbox? Subscribe below.

Subscribe to BusinessRiskTV Business and Economy Newsletter

Get our free news bulletin and videostream alerts.

Important Things To Know About Business and Global Economy
Subscribe to BusinessRiskTV Business and Economy Newsletter
Recommended articles and videos

BusinessRiskTV Business Keynote Webcasts and Special Events News

Top Business News Today Latest Financial Market Economic News

Innovation and Entrepreneurship News

Live business market and global financial news updates

Corporate News Articles Video Streaming Online Opinions Reviews

Video News BusinessRiskTV Latest Business Economy News Opinions Review

Business News Headlines Analysis Discussion

Marketing News Articles Stories Features and Ideas

How To Grow Your Business Online Presence Grow Online Sales

How To Sell On The Risk Management Marketplace Buy Risk Products

Business Development Consulting Services Growing Business Faster

Ideas for effective risk management enterprise risk leadership

Risk Management Leadership Conference Risk Management Training

What Are The Biggest Countries Doing and What Is Impact On Your Business

Managing Uncertainty Better

Online Sellers

Risk Analysis In Business

Fourth Industrial Revolution

BusinessRiskTV What You Need To Know About Business and Economy Today

Top Business News Today Latest Financial Market Economic News

What do you need to know today too protect and grow your business with less uncertainty with BusinessRiskTV

Subscribe to Top Business News Today for free alerts and bulletins

What business and economic news do you need to know? Understand new financial market and economic developments better. Inform your business decision making to reduce uncertainty impacting on your business objectives.

Enter code #TopBusinessNews

Promote and market your business on Top Business News for 12 months

Benefits of proactive risk management

Celebrate Your Online Business Growth With Pro Risk Manager

BusinessRiskTV Top Business News Commentary and Review

Latest business financial market and economic news commentary corporate risk analysis. Read the top business news stories and watch video reports online. Follow live news updates and highlights.

The place for free country risk and industry risk executives business leaders and risk professionals.

  • Share business risk insights and experiences
  • Ask for risk management guidance
  • Build valuable business connections

You can find country or industry groups to join by using the search feature on this website. You could also create your own networking group business club or web page to market promote and advertise your business.

Once you subscribe for free you are able to join like minded members in online conversations live discussions workshops and training. Find answers to your business questions.

Contribute to BusinessRiskTV.

Subscribe for free business financial market and economic news alerts bulletins and video news reviews

Get latest breaking news business news financial and investing news and more Konline for free.

Top Business News Today

Subscribe for free business financial market and economic news alerts bulletins and video news reviews

Recommended

Risk AcademyBreaking News
News HeadlinesLive Streaming News

#BusinessRiskTV #TopBusinessNews #TopEconomicNews #TopFinancialNews #News #NewsHeadlines #NewsOnline #NewsReports #NewsReview #NewsMagazine

BusinessRiskTV Top Business News Today Latest Financial Market Economic News

Best countries for business

What to do in the most business friendly and least business friendly businesses in the world with BusinessRiskTV.com

Subscribe to BusinessRiskTV for free to receive alerts and bulletins

Discover the best and worst of business on BusinessRiskTV. Get the latest business and economy news headlines opinions and reviews. Save money and time.

How are G2O countries and large economic areas impacting on your business risks

Our enterprise risk magazines keep you up to date with the latest news opinions risk analysis and business reviews.

Find out how risks in the biggest countries or trade areas in the world creates threats and opportunities for your business wherever you are in the world and wherever you want to export to.

It would help if the G20 countries could create business opportunities more than they create threats for the benefit of the whole world including emerging economies. However you may also need to take actions to mitigate the impact of these countries on your business.

Speak to business leaders and entrepreneurs around the world

Connect with creative innovative ambitious leaders around the world online from your phone pc or mobile device to protect your business better and grow faster.

G20 and other 1st world countries
Enter code G20 ALERTS when you register online for free

Recommended

https://businessrisktv.com/exhibitions-expos-trade-fairs/middle-east/
AcademyMarketplaces
ExhibitionsRisk Magazine

BusinessRiskTV What Are The Biggest Countries In The World Doing and How Does It Impact On Your Business

Managing Uncertainty Better

Understand your business risks to manage your key business risks better with BusinessRiskTV

How do leaders manage uncertainty in business better

Managing uncertainty is a daily business dilemma. Business leaders have internal and external risk factors driving uncertainty in business. Often this uncertainty can lead to poorer business performance or even catastrophic business failure.

We are developing a business risk management hub to help inform your leadership team. Reduce the impact of uncertainty on your business success.

  1. Various risk management identification tools and techniques will bring emerging risks to your attention
  2. Our Partners analysis country and industry risks
  3. Inform your attitude to risk and take a more balanced risk based approach to business management

Our free enterprise risk management resources provide a free risk insight to the risks that matter to your business prosperity and even survival. Develop your risk knowledge for free.

Join in our online risk management discussions workshops and training sessions to hone your risk management skills and ability.

Leaders can manage uncertainty in various ways. Some bury their head in sand. Others adopt a belts and braces approach to risk control incurring imbalanced costs to benefits.

We can not guarantee you greater business success. We can help inform your business decision making process. You will be more likely to make better business decisions.

When facing doubts or uncertainty many business leaders turn to their gut instinct. Rolling the dice may turn up the result you are aiming for. This may work for you. However better risk management information may enable you to choose a different path. Or it may over procrastination to drive forward growth with more confidence. Not making a decision can be as bad as instinctively shooting off blindly.

Dealing with uncertainty better can help you navigate around pitfalls your competitors fall into. Help guide your business to greater success with less uncertainty. Manage uncertainty more cost effectively.

  • Leaders can use risk management principles and practices to take the next step towards success with more confidence.
  • Leaders can prepare themselves and their business to face the uncertain business environment to control threats and seize new business opportunities.
  • Leaders must learn to manage uncertainty better but they need not do this alone

Free subscription to BusinessRiskTV can support your business improvement plans.

Subscribe to BusinessRiskTV for free for tips advice and help to manage uncertainty better

Meet the challenges to your business with more confidence. The world is facing growing uncertainty. Adjust your business strategy to account for the significant risks impacting on your business objectives.

Join more than 27000 people interested in better enterprise risk management.

  • Read business risk management articles relevant to your enterprise.
  • Watch videos to inform your business decisions making.
  • Pick up ideas from top business thought leaders to grow your business faster with less uncertainty.

Subscribe for free to receive alerts to latest risk management news opinions and reviews.

BusinessRiskTV.com Free Subscription Online

Subscribe to BusinessRiskTV.com for free

Recommended

BusinessRiskTV Managing Uncertainty Better

Business Risk Analysis BusinessRiskTV Risk Analysis In Business

How to manage risk in business with BusinessRiskTV.com

Strategic Operational and Project Business Risk Analysis Tips Reviews Workshops

BusinessRiskTV business risk analysis helps business leaders to manage business risks better. Industry risk analysis and country risk analysis to help you make business decisions. Risk analysis of a company for business leaders in UK and overseas. Do you know what to do to protect your business and grow it faster? Understand the importance of business risk analysis in improving your business performance. Inform your business management decisions.

Making strategic operational and project decisions easier and quicker. Have more confidence in your business survival and prosperity with better business risk analysis.

BusinessRiskTV

Connect with top risk management experts and business leaders. Improve your risk management knowledge and business intelligence. Develop risk management skills.

Enter code #BusinessRiskAnalysis

Top Business News Today

Risk analysis of a company in decision making is key to reduce uncertainty impacting on your business objectives. Risk analysis of a company risk profile can better utilise business assets. Reviewing corporate and economic risks to help inform business decision making process. Identifying and understanding enterprise risks associated with managing a business or enterprise better. Analysing the potential issues and uncertainty impacting on business objectives.

Risk Magazine

Subscribe to BusinessRiskTV Business Risk Analysis

Get help to define the risk factors affecting your business decision making process. Identify new risk management measures to reduce business threats and increase business opportunities.

Risk Analysis Techniques
Subscribe to BusinessRiskTV Business Risk Analysis and enter code #BusinessRiskAnalysis

Promote and market your business risk analysis related business on BusinessRiskTV for 12 months

Put your products or services for risk analysis of a company in front of new people already interested in your type of business offering before your competitors do.

Cheap ways to promote your business
Find out how to promote your business locally and globally. CLICK HERE or email editor@businessrisktv.com entering code #BusinessRiskAnalysisMarketing

Increase the sources of your revenue streams more sustainably. Grow your business faster with BusinessRiskTV.

MarketplacesExhibitions
Save MoneyRisk Magazine
Discover better ways to protect and grow your business with BusinessRiskTV

Business Risk Management Articles Videos and Deals

#BusinessRiskTV #BusinessRiskAnalysis #RiskAnalysis #ProtectYourBusiness #BusinessProcessManagement #RiskManagement #EnterpriseRiskManagement #ERM #BusinessRiskAnalysisMarketing #RiskAnalysisOfACompany

Business Risk Analysis BusinessRiskTV Risk Analysis In Business

Business Risk Manager Service

Find out how to protect and grow your business better with BusinessRiskTV.com

Business risk manager service with BusinessRiskTV. Want help to protect and grow your business faster? Find out more about our free business risk management online service. Network with top business thought leaders locally and globally.

Enter code #RiskManagerService

See The Road Ahead More Clearly With BusinessRiskTV

Holistic enterprise risk management tips advice and support online

Free online enterprise risk management help to protect and grow your business faster with less uncertainty.

Enter code #BusinessRiskManagerService

Subscribe to free online BusinessRiskTV Risk Management Online

How do you manage emerging enterprise risks? Could you improve your business performance if you manage enterprise risks better?

Business Risk Manager Services
Subscribe to free online BusinessRiskTV Risk Management Online enter code #BusinessRiskManagerService

Promote and market your business on BusinessRiskTV for 12 months

Present your products or services to buyers at the the time that they are ready to buy before your competitors do.

Cheap ways to promote your business
Find out how to promote your business locally and globally. CLICK HERE or email editor@businessrisktv.com entering code #BusinessRiskManagerMarketing

Link into your existing sales process direct from BusinessRiskTV. Increase your revenue streams more profitably. Grow your business faster.

Read articles and watch videostream to protect and grow your business faster trending on BusinessRiskTV

Grow Your Business With Us
MarketplacesExhibitions
Save MoneyRisk Magazine
Discover new ways to protect and grow your business faster with BusinessRiskTV

#BusinessRiskTV #BusinesRiskManagementService #BusinessRiskManager #RiskManager #RiskManagement #EnterpriseRiskManagement #BusinessRisk #Governance #Risk #Compliance #BusinessRiskManagerMarketing

BusinessRiskTV Business Risk Manager Service

Business Risk Management Club

Help to protect and grow your business

Discover the simple and affordable way to manage your business risks better

Manage business risks better by country by industry and by specific types of business risks. Join our business risk management club for free.

Introducing the BusinessRiskTV Business Risk Club

BusinessRiskTV business risk management active members club enables members to contribute to BusinessRiskTV for free. Active members around the world contribute articles and videos to help grow their business faster with less uncertainty to help inform readers business risk management decision making.

  • Boost your sales more profitably
  • Increase your network of business contacts
  • Protect your business uncertainty negatively impacting on your business

If you want an innovative flexible way to grow your business faster and build business resilience join and contribute to BusinessRiskTV Club today.

Members of the BusinessRiskTV business risk management club collaborate to reduce corporate threats and increase business growth opportunities through

  1. business networking with key business decision makers locally and globally
  2. improved risk assessment via better business intelligence
  3. reduced cost of risk control via deals discounts and special offers

Build a more successful and sustainable business more easily with BusinessRiskTV.

Join Buisness Risk Management Club Free

Join BusinessRiskTV Business Risk Management Club Today For Free enter code #RiskClub

Join the BusinessRiskTV Business Risk Club and receive FREE business risk alerts bulletins and latest business risk news to stay ahead of your competition.

The Club is free to join. Then you choose whether you want to contribute to BusinessRiskTV to promote your own business and inform online readers. You pay an annual membership fee to regularly contribute to BusinessRiskTV and promote your business interests cost effectively.

Key benefits of BusinessRiskTV Risk Club and reasons to join and contribute today

  1. Free to join. There is no cost to join the club. Once you join you also have the option of contributing to BusinessRiskTV to better market promote and advertise your business. In addition you will have increased access to discussions workshops and executive training to better protect your business. You are in control of what to do next after you join the club for free.
  2. Free business intelligence to inform your decision making to build your business resilience. Club members receive free news alerts and bulletins. Our risk watch service scans the horizon for emerging risks and analyses business risk trends. You can attend online discussions workshops and executive training sessions.
  3. Safe and secure. All payments are made through Paypal an independent third party online payment service which stops us receiving full details of your banking or payment details so you are protected by Paypals security systems.
  4. Build your online profile and connections to grow your business faster. BusinessRiskTV has an impressive online profile to connect you with local and global business risk management experts and new sales for your business.
Join BusinessRiskTV Business Risk Management Club

Join BusinessRiskTV Business Risk Management Club enter code #RiskClub

Fast Growing Local and Global Business Risk Management Connections

BusinessRiskTV has already built up an impressive bank of like minded business leaders and business risk management consultants for club meMbers to tap into for business tips advice and support.

The BusinessRiskTV Club is carefully expanding its reach to help business leaders to better protect and grow their own businesses and careers.

BusinessRiskTV Club is NOT just a talking shop. It is a business growth hub to practically accelerate members revenue streams. It is business accelerator where everyone has the same interest in seeing the businesses build resilience regardless of economic environment.

Join BusinessRiskTV Business Risk Management Club

Join BusinessRiskTV Business Risk Management Club enter code #RiskClub

Founder of BusinessRiskTV Risk Management Club

Read Keith Lewis Testimonials as to the quality of his work. This gives some background as to the quality of the business risk management business intelligence being gathered and distributed.

Join BusinessRiskTV Business Risk Management Club

Join BusinessRiskTV Business Risk Management Club enter code #RiskClub

You are in control of your relationship with us

In addition to controlling your own business risks better you are in total control of how you use BusinessRiskTV and how much you want to contribute to it to increase your own business growth.

You are always in control of your subscription to BusinessRiskTV club. You can choose to remain on the free membership and still receive free business intelligence and risk knowledge. Or you can regularly contribute to the content and thus increase your own business profile and business growth.

We are in it for the long term and look forward to working with members for sustainable mutual benefit. If you want to stop your membership you can at any time. We are looking forward to you working with us to help your business grow faster.

Hands Free Business Growth and Development Of Your Business

One of the great strengths of the BusinessRiskTV business risk management club is that members do not need to know how to market their business online. You can simply email us the message you want to promote and we can connect you with more new potential customers or other business leaders.

You can read business risk management articles or watch videos for free including business risk management expert opinions and analysis to inform your own business decision making process.

After you join the club you can just use it as a simple way to be kept up to date on emerging and developing corporate risks impacting on your business objectives.

Sit back and receive email alerts to important business risk intelligence to develop your risk management knowledge. Alter your business risk management plan accordingly based on expert risk analysis. Alerts bulletins and news have the potential to build your business resilience and business growth.

Join BusinessRiskTV Business Risk Management Club

Join BusinessRiskTV Business Risk Management Club enter code #RiskClub

Boost Your Business Growth

BusinessRiskTV Club could be very profitable for your business if you contribute to the content and connect to your business. There are no guarantees of returns but membership of the club expands your options for greater business success and business resilience. There will be failures. That is the nature of business marketing and development. However you will get access to innovative flexible ways to grow and protect your business better. We will minimise the cost of uncertainty impacting on your business objectives over time. At the same time we will increase the chances of become a market leader in your industry and country.

Join BusinessRiskTV Business Risk Management Club

Join BusinessRiskTV Business Risk Management Club enter code #RiskClub

Frequently Asked Questions FAQs

  • Is BusinessRiskTV Club free to join and how does BusinessRiskTV make money? It is free to join now to receive free alerts bulletins and business risk news. If you want to contribute to BusinessRiskTV by becoming a Member you pay an annual fee. BusinessRiskTV also accepts donations to support free independent business risk management news broadcasting and business risk management research. In addition businesses pay us one off fees to promote market and advertise their business products and services.
  • Am I tied into the BusinessRiskTV Club? It is free to join club. If you want to contribute to BusinessRiskTV there is a membership fee. You are free to leave the club at anytime. You will not be entitled to a refund of the annual membership fee but will not be tied to renew your membership.
  • How long does membership last? 12 months renewable annually.
  • I do not know anything about online business marketing and development? That is one of the great strengths about being in the Business Risk Management Club. You simply join now and then we will email you to find out what you need to do to grow your business faster. We will then go away and start your marketing and promotion campaign. We will design post and update your contributions to promote your business. Our team of enterprise risk experts and business risk advisers to help protect and grow your business faster.
  • How fast will my business grow? It is impossible to say. It depends on how well we can work together to get the most from your existing business development tools and initiatives. The potential is there for massive gains but the value of your membership fee could be worthless if we fail to work well together. That is why our members should always diversify our marketing options to maximise the likelihood of increasing sales. We will guide you on the diversification options based on our discussions on what you offer and when. You are not putting all your business development eggs in one basket but the affordable membership fee expands the likelihood of your business growing faster.
  • How often can my business contribute to BusinessRiskTV? Contribution levels is based on hours it takes to produce and publish each contribution. You will be buying 56 hours of work to produce and publish your contributions each year.
  • Does my business need to contribute regularly to BusinessRiskTV? No. The more you contribute the more you promote your own business interests and increase the chances of faster business growth.
  • My business marketplace is not in UK so can I still join and contribute to BusinessRiskTV? YES! The Club is open to any business selling legal and morally acceptable products and services. Legal is legal but morally acceptable comes down to our own opinion as to what is morally acceptable. Areas include Europe USA Canada Latin America Australia and Asia Pacific.
  • Is paying my membership fee safe? Yes. Your membership fee will be paid via Paypal a global independent payment provider who have their own safe and secure payment systems. We will never see your full payment details as these are retained by Paypal who will transfer your membership fee to our Paypal account.
  • What is the annual membership fee? This will vary depending on how many members we have. As the number of members increase so will the annual membership fee so get in quick to keep your membership fee low!
Join BusinessRiskTV Business Risk Management Club

Join BusinessRiskTV Business Risk Management Club enter code #RiskClub

BusinessRiskTV Business Risk Management Club

Looking Back To Move Forward

Understand your business risks with enterprise risk analysis on BusinessRiskTV for your country or industry

Looking back at past mistakes to make future better

In order to move forward we must look back. If we want to create a better future for our businesses we need to learn the lessons from the mistakes of the past.

Business Enterprise Risk Management News Opinions Reviews

BusinessRiskTV : the business and economy headlines, the risk analysis, the risk management debates – sent direct to your mobile device, PC or TV

Sometimes you have to look back to move forward

Nobody wants to make mistakes. Where they have been made we should not repeat them

  • Achieve what we want from business decisions quicker and easier
  • Reduce risk of duplicating past mistakes by learning the lessons
  • Benefit from others mistakes as well as your own mistakes

Learn how to use past mistakes to make business better. Undertake risk reviews to check what  went wrong and why. Develop real risk insight to build your business intelligence.

Often we learn more from failure than success. Ultimate business performance can be higher after lessons learnt. Not reviewing risk management errors condemns you to repeating them.

Transform your business on back of past mistakes. Your past mistakes can be the foundation of your future success. However do not dwell on past mistakes. Learn lessons move on but do not keep picking wounds.

Step into your future by looking back at past mistakes

BusinessRiskTV

Collaborate with business leaders around world. Learn lessons from their mistakes and from businesses not in the collaboration. Review business mistakes so we do not suffer same fate.

In order to move forward we must look back BusinessRiskTV.com

Looking back at past mistakes to move forward

BusinessRiskTV Looking Back To Move Forward

Why Business Risk Management Is Important

Manage business risks better with BusinessRiskTV.com

An holistic business risk management approach ensures the best use of business resources.

How To Manage Risk In Business

Practical ways to manage risk better. Tackle common business risks holistically enterprise wide. Learn best practice risk management techniques in business.

Best Practical Guide To Business Risk Management
Subscribe to BusinessRiskTV.com enter code #ManageBusinessRisksBetter

Its not about how to reduce risk

External or internal driven risks threaten your business. They also create new business development opportunities. Reducing the effect of uncertainty on your business is important.

How do you manage enterprise risks? Do you put risk into different silos like safety, insurance, cyber risk, sales strategy etc? They can be rolled into one holistic risk based approach.

What is the most effective way for a business to manage risk? Look at what you are trying to achieve? Could you achieve more with your existing assets? Has good luck been saving you from disaster?

Understand the bigger picture first. When you know what risk you have then manage it.

There is danger being in business. Danger that you could blow your value. Danger you could under perform.

Join the discussion on how to manage risk in business better

Campaign for better manage of enterprise risks. Join the discussion on business risk management for free from your twitter account.

Manage Business Risks Better

Read more about business risk management. Watch videos online from your phone pc or tablet

BusinessRiskTV.com Risk Academy Sign Up For Free
Subscribe to BusinessRiskTV.com for free enter code #RiskAcademy

Enterprise risk management articles. Latest news opinions and product and service reviews. Engage with your peers. Ask the experts for help to overcome your risk management problems.

Read more and watch more videos online. Develop your risk knowledge to improve business performance. Sign up to BusinessRiskTV.com for alerts to latest in business risk management.

BusinessRiskTV.com Free Subscription Online To Lean Business Risk Management
Subscribe to BusinessRiskTV.com for free enter code #ManageBusinessRisksBetter

Additional business risk management resources
MarketplacesExhibitions
Save MoneyRisk Magazine

#BusinessRiskTV #ManageBusinessRisksBetter #RiskAcademy

BusinessRiskTV Manage Business Risks Better

Executives Behaving Badly

Learn what not to do and why as well as what you should be doing with BusinessRiskTV

Corporate Misbehaviour Is A Misnomer

Corporate or enterprise entities do not make mistakes or create a bad business culture executives do. Illegal unethical or bad business practices arise because that’s the way executives want a company to achieve corporate objectives.   Executives may or may not consider their business practices as bad or unethical but the result is the same corporate misbehaviour.

iso 31000 Enterprise Risk Management Framework Principles Best Practices

Understanding corporate misbehaviour

It may be a pointless waste of money undertaking a business health check if the executives are going to be unreceptive to the final risk management report, or simple pay lip-service to the outcomes.

How to protect your business

Find out how to protect your business better and build business resilience with BusinessRiskTV

Many CEOs know what game needs to be played with enterprise risk management ERM before they can return to their own agenda for the business.   Internal or external risk management audits can just play into the CEO’s attitude to risk management.   Such executives short-term philosophy seems to rely on the hope that the shit doesn’t hit the fan during their time as CEO and whatever happens after they move on is not a concern for some incumbent CEOs.

Much of executive misbehaviour, and therefore corporate misbehaviour, is a direct result of executive pay and associated benefits.   Misdirecting executive pay and rewards drives most if not all catastrophic corporate collapses.   Before the collapse poor executive pay and rewards strategies poison business innovation and employee motivation.

To anticipate which companies will survive sustainably you could look at how executives are rewarded.   It is the single biggest driver of corporate culture and long-term success, or not as the case maybe.

Executive managers cause corporate scandals, corporate scandals are not externally driven.   The proximate cause of the corporate scandal or collapse doesn’t start further down the organisation nor does it start from outside the company.   CEO bad behaviour is normally the proximate cost or the catalyst for corporate collapse.

Corporate Scandals

Corporate scandals aren’t a surprise to most executives, never mind the CEO.   They take the level of risk they think is required to achieve their business objectives.   They roll the dice and sometimes it pays off and sometimes it doesn’t.

Supporting More Informed Decision-Making

Taking Risks To Achieve More In Business With BusinessRiskTV

For example, many in the banking and finance industry look upon the financial crisis as an external risk that impacted on their business strategy.   No, or little, blame can be placed at the bankers door!   It was all the other bankers and financers who were at fault for their share price collapse, mass redundancies and lost business opportunities – not their fault as their business was doing just fine until the financial crisis tsunami hit their business.

Such egotistical responses stem from either self preservation, or lack of care for their part in the near global systemic financial collapse of the banking and financial sector and the very near global anarchy which would have ensued.   Politicians, who were part of the problem, became part of the solution – make money as cheap as possible via low interest rates and massive almost unremitting quantitative easing QE.

Mothers forget how bad childbirth was

More than a decade after the start of the financial crisis there is still mass unemployment in the developed world and the developing world lost a decade of opportunity to crawl out of poverty.   However, the key decision-makers in the business world have either forgiven themselves or reinvented themselves in position of power.   In addition, a new raft of politicians are in place, or about to find positions of power, to facilitate the next financial crisis.

At its least useful, enterprise risk management ERM is a tool to spread the blame should the shit hit the fan, so one would have thought that ERM could be more popular than it is.   At its most useful it helps business leaders make business decisions that are more likely to be good ones for the long-term sustainability of the business for the benefit of all stakeholders in the business – including the CEO.

BusinessRiskTV.com Free Subscription Online Corporate Misbehaviour

Subscribe to BusinessRiskTV.com for free enter code #ExecutiveBehaviour

#BusinessRiskTV #CEObadbehaviour

BusinessRiskTV Executives Behaving Badly CEO Bad Behaviour

A to Z Guide To Risk Management

Enterprise risk management ERM tips advice and support with BusinessRiskTV.com

A to Z guides. Understand the theory and practice of risk management. Ask for help tips advice and training to embed risk management in your organisation.

Enter code #AtoZGuides

Practical Guide To Enterprise Risk Management

Help to manage corporate business enterprise risks better

A to Z Business Risk Management

BusinessRiskTV Guide To Risk Management

Access help online to understand risk management better and find a practical way to apply it to your business or enterprise.

Subscribe to BusinessRiskTV

BusinessRiskTV.com Free Subscription Online Practical Guide To Enterprise Risk Management
Practical Guide To Enterprise Risk Management enter code #AtoZGuides

#BusinessRiskTV RiskManagementGuide #RiskGuide #EnterpriseRiskManagement #ERM #AtoZGuides

BusinessRiskTV A to Z Practical Guide To Risk Management

Global Business News Headlines Analysis Discussion

Get the latest business and finance news opinions and reviews on BusinessRiskTV.com

Read global business news headlines for free. What do you need to know about business and the economy today? Keep up to date with developments in business and the global economy. Network with Citizen Journalists for a different perspective on the present and the future.

Enter code #GlobalBusinessNews

BusinessRiskTV News Headline Risk Analysis Debate Discussion

BusinessRiskTV Business News Headlines Analysis and Comment

Latest BusinessRiskTV business news including breaking personal finance news corporate news financial news business and economic news. Get news debate and opinions for free.

Breaking Business News and Business Risk Management Features
BusinessRiskTV Top Business News

Get latest running business news online including business risk analysis and business leader comment

Expert business guides and expert business analysis for UK and global business leaders. Up to the minute business reports on global business marketplace and world economy including risk analysis on how it could affect your business.

Top Business News Today

Risk Expert Business Commentary

Get the business opinions that matter straight to your email inbox for free or read online

BusinessRiskTV Business News Debate Opinions Free Subscription Online
Latest business news debate and opinions on BusinessRiskTV

Promote and market your business on BusinessRiskTV for 12 months

Cheap ways to promote your business
Find out how to promote your business locally and globally
MarketplacesExhibitions
Save MoneyRisk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #BusinessNews #EconomicNews #BusinessDebate #BusinessOpinions #RiskAnalysis #BusinessAnalysis #BusinessTips

Global Business News Headlines Analysis Discussion

Global Economy Risk Analysis and Review

Global growth and contraction news analysis and review with BusinessTiskTV

Top Business News Today

Inform your business decision making. Read and watch risk intelligence and analysis. Discover the best and worst of the global economy. Get the latest global economy news headlines opinions and reviews. Save money and time with BusinessRiskTV.

The Threat of Rising Bond Yields in European and American Bond Markets

By Keith Lewis 20th October 2023

Bond yields are the interest rates that investors receive when they lend money to governments or corporations. Bond yields have been rising steadily in recent months, both in Europe and the United States. This is due to a number of factors, including the Federal Reserve’s plans to raise interest rates and concerns about inflation.

Rising bond yields can have a number of negative consequences for investors and businesses. For investors, rising bond yields can lead to losses on existing bond holdings. For businesses, rising bond yields can make it more expensive to borrow money.

This article will explore the threat of rising bond yields in European and American bond markets in more detail. It will also discuss some of the risk management actions that investors and businesses can take to protect themselves from this threat.

Why are bond yields rising?

There are a number of reasons why bond yields are rising in European and American bond markets. One reason is the Federal Reserve’s plans to raise interest rates. The Federal Reserve raises interest rates in an effort to combat inflation. When interest rates rise, the cost of borrowing money increases. This can lead to a decrease in demand for bonds, which can cause bond yields to rise.

Another reason for rising bond yields is concerns about inflation. Inflation is the rate at which prices for goods and services are rising. When inflation is high, investors demand higher returns on their investments to compensate for the loss of purchasing power. This can lead to an increase in bond yields.

What are the risks of rising bond yields?

Rising bond yields can have a number of negative consequences for investors and businesses.

For investors, rising bond yields can lead to losses on existing bond holdings. When bond yields rise, the prices of existing bonds fall. This is because investors can buy new bonds with higher yields, which makes older bonds with lower yields less attractive.

For businesses, rising bond yields can make it more expensive to borrow money. Businesses often borrow money to finance growth and investment. When bond yields rise, the cost of borrowing money increases. This can make it more difficult for businesses to finance their growth and investment plans.

What can investors and businesses do to protect themselves from the threat of rising bond yields?

There are a number of risk management actions that investors and businesses can take to protect themselves from the threat of rising bond yields.

Investors

Investors can protect themselves from the threat of rising bond yields by diversifying their portfolios and investing in shorter-term bonds.

Diversification means investing in a variety of different asset classes, such as stocks, bonds, Bitcoin and property. By diversifying their portfolios, investors can reduce their overall risk.

Investing in shorter-term bonds can also help investors to protect themselves from rising bond yields. Shorter-term bonds have less interest rate risk than longer-term bonds. This is because shorter-term bonds are more likely to mature before interest rates rise significantly.

Businesses

Businesses can protect themselves from the threat of rising bond yields by hedging their interest rate risk and borrowing money at fixed interest rates.

Hedging interest rate risk involves using financial instruments to offset the risk of changes in interest rates. There are a number of different hedging instruments available, such as interest rate swaps and options.

Borrowing money at fixed interest rates can also help businesses to protect themselves from rising bond yields. When businesses borrow money at fixed interest rates, they lock in the interest rate for the life of the loan. This protects them from the risk of rising interest rates during the term of the loan.

Conclusion

Rising bond yields can have a number of negative consequences for investors and businesses. However, there are a number of risk management actions that investors and businesses can take to protect themselves from this threat.

Investors can protect themselves from the threat of rising bond yields by diversifying their portfolios and investing in shorter-term bonds. Businesses can protect themselves from the threat of rising bond yields by hedging their interest rate risk and borrowing money at fixed interest rates.

I urge investors and business leaders to take risk management action to protect themselves from the threat of rising bond yields. By taking action now, you can minimise the potential impact of rising bond yields on your investments and your business.

Top Business News Today
What do you fear this year

Join the global risk experts forum online

Global Business Development With BusinessRiskTV.com

Click here or email editor@businessrisktv.com to subscribe to BusinessRiskTV.com for free enter code #GlobalEconomy

Subscribe to BusinessRiskTV for free global economy alerts bulletins and reviews to your inbox

Enter code #GlobalRiskAnalysis

World Economic News Headlines

Read global economy articles and watch video updates on global economic news headlines business risk analysis business leader debate and discussion. Entrepreneurs executives and business leaders take part in our strategic growth business forum online events from you phone pc or mobile device.

Inform your business decision making from expert panel and member discussions and sign up for innovative business development online workshops from anywhere in the world where business innovators operate.

Global Economy News Analysis Review Live Online

Current global economy news articles and video content. Stress test the global economy with latest forecasts reports and global economic analysis.

Promote and market your business on BusinessRiskTV Global Economy Review for 12 months

Cheap ways to promote your business

Find out how to promote your business locally and globally. CLICK HERE or email editor@businessrisktv.com entering code #GlobalEconomyReviewMarketing

Put your products or services in front of new people already interested in your type of business offering.

Link into your existing online sales process direct from BusinessRiskTV or use our eCommerce solutions to increase your sales cash flow and profit

Increase the sources of your revenue streams more sustainably. Grow your business faster with with BusinessRiskTV.

BusinessRiskTV World Economy Journal

Taking a look at global economy data. Undertaking business risk analysis. World economy and business research and development reports and analysis.  

Subscribe to BusinessRiskTV for free to receive email alerts to live events on demand video reports and global business analysis reports

BusinessRiskTV.com World Economy Journal
Enter code #GlobalGrowthForum
AcademyMarketplaces
ExhibitionsRisk Magazine

Discover better ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #GlobalGrowthForum #GlobalEconomy #GlobalNews #GlobalMarketplace #GlobalMagazine #GlobalReview #GlobalReports #GlobalBusiness #GlobalEconomy #GlobalToday #InternationalTrade #Entrepreneurship #BusinessCoaching #RiskManagement #EnterpriseRiskManagement #GlobalEconomyReviewMarketing

Global Economy Risk Analysis and Review

Business Risk Management Training Academy Videos Webcasts Podcasts Broadcasting

Risk management knowledge and skills development with BusinessRiskTV.com

Subscribe to BusinessRiskTV for free alerts and bulletins on upcoming workshops and webinars

Develop your business enterprise corporate risk management knowledge. Find out how to manage uncertainty in business better. Save money and time with BusinessRiskTV.

Enter code #RISKTRAINING

Business risk management training programme for business leaders and managers in small to medium-sized companies

Enterprise Risk Management Partners

Our featured business risk management training programme offers ongoing, interactive, and up-to-date training on managing various types of business risks, including political, economic, social, technological, legal, and environmental risks. Our program is designed to help business leaders stay informed and make informed decisions that will protect their company’s bottom line and open new opportunities for growth.

Tune in live and on demand to corporate business enterprise risk management training academy

Watch participate in or contribute to online corporate business enterprise risk management workshops discussions and enterprise risk management training courses.

BusinessRiskTV.com Business Risk Management Training
BusinessRiskTV.com Better Protection Faster Growth Online Learning enter code #RiskAcademy
Corporate Business Enterprise Risk Management Training Courses
Subscribe to BusinessRiskTV.com Business Enterprise Risk Management Training for latest news and reviews on executive training courses enter code #ExecutiveTraining

Online Regional and InCompany Corporate Business Enterprise Risk Management Training Courses

Free risk management courses to watch and download. Sign up for free risk management discussions and debates. Register for enterprise risk management training courses.

Risk Management Courses Distance Learning
Virtual Online Remote Risk Management Short Courses

Find the best risk management training courses for your business

You will learn practical business enterprise risk management tools and techniques. Easily apply what you learn to your business. Boost performance and increase business sustainability regardless of business risk environment.

Browse professional corporate business enterprise risk management courses to improve your business prospects. Better understand the threats and opportunities facing your enterprise.

Enterprise Risk Management Training Workshops Online
Enter code #ERMtraining

Plan risk management better

Take part in online discussions and debates anywhere from your mobile device or PC.

Enterprise Risk Management Video Training
Enter code #EnterpriseRiskManagement

BusinessRiskTV Corporate Enterprise Risk Academy

Join our executive and senior management training courses to overcome lack of good risk management practices. Develop your risk knowledge and expertise needed to run a more cost effective entity.

BusinessRiskTV Risk Academy creates opportunities to cost effectively learn more about best risk management practices.

BusinessRiskTV.com Risk Academy
Enter code #RiskAcademy
  1. Protect your business assets better.
  2. Reduce liabilities.
  3. Seize new business opportunities for growth.

Complete the form about and tell us about your corporate business enterprise risk management needs.

Academy Marketplaces
Exhibitions Risk Magazine
Discover new ways to protect and grow your business with BusinessRiskTV

#BusinessRiskTV #RiskManagementTraining #BusinessTraining #RiskAcademy #BusinessRiskAcademy #RiskManagement

BusinessRiskTV Business Enterprise Risk Management Training Academy