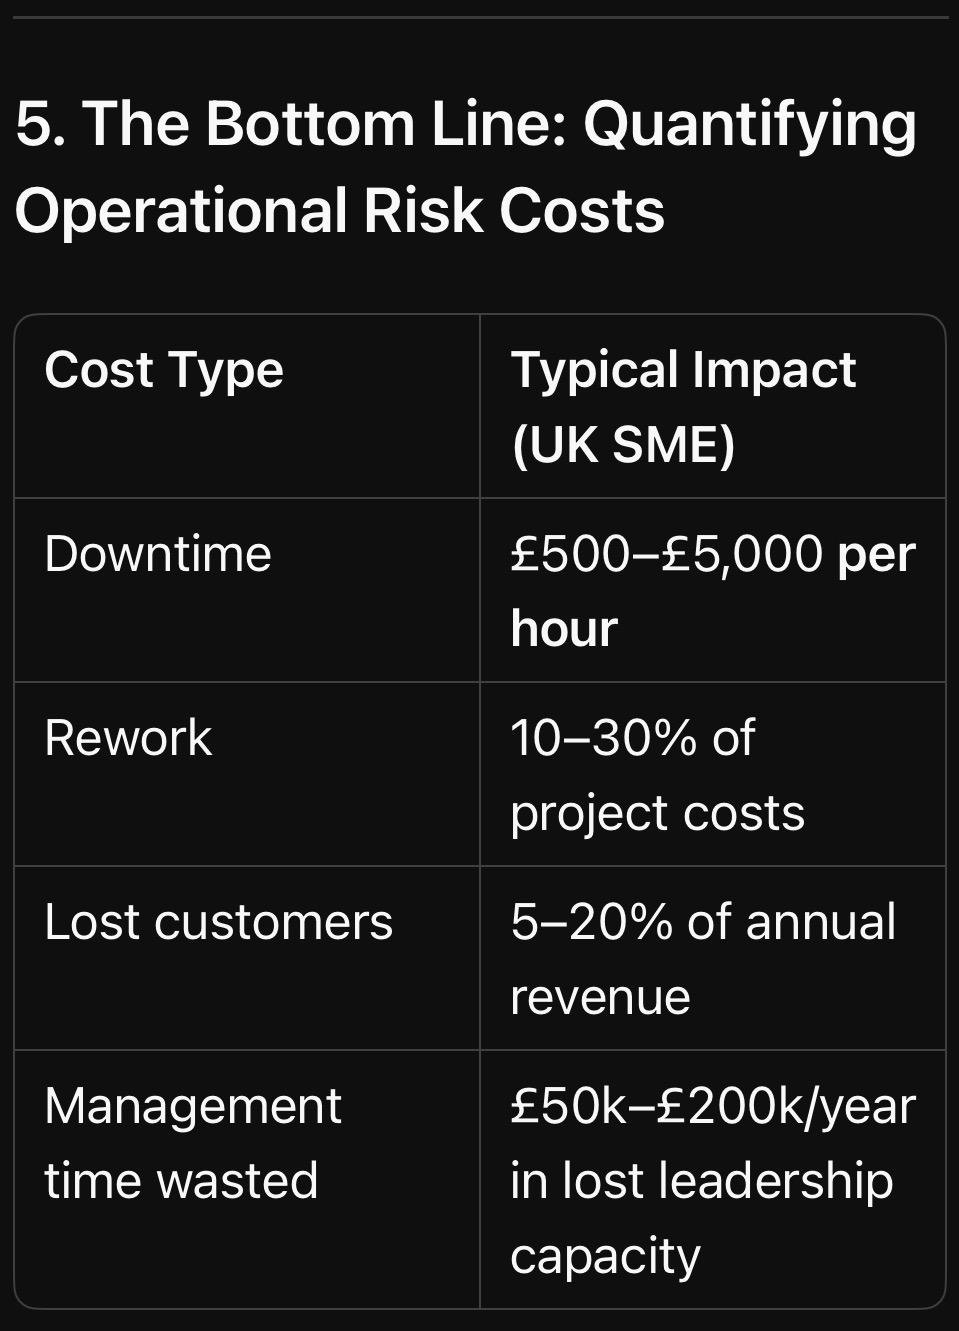
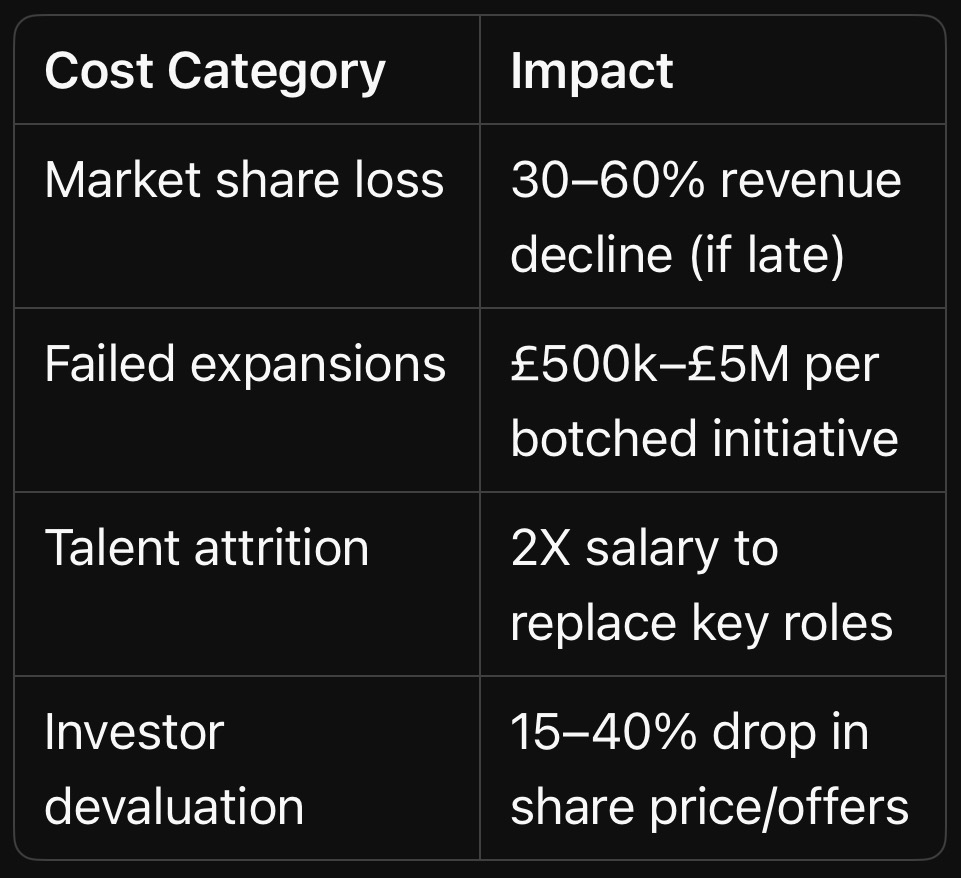
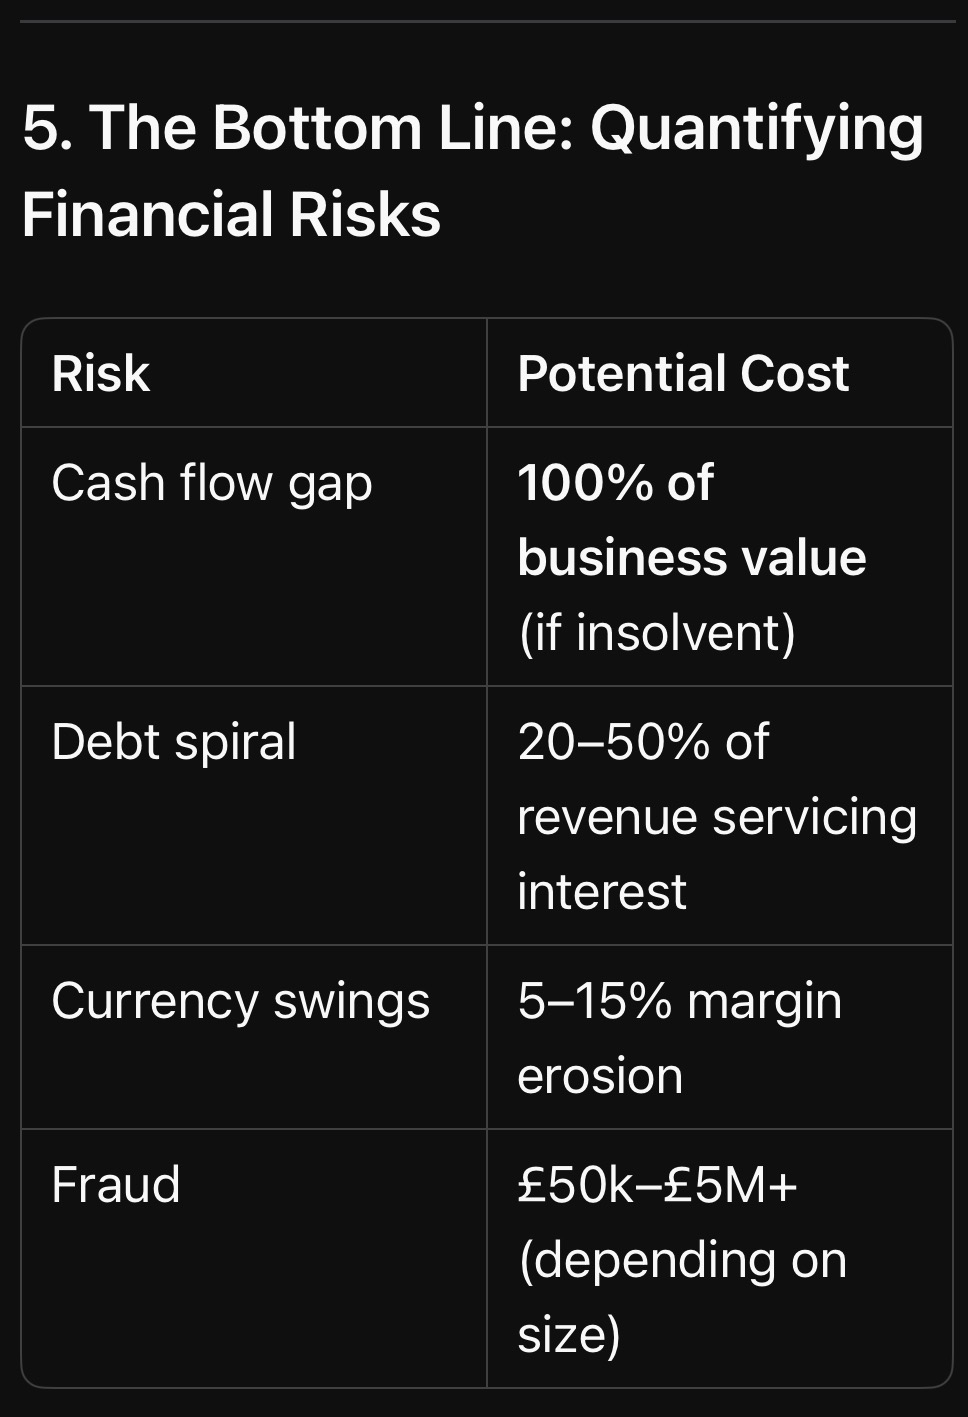
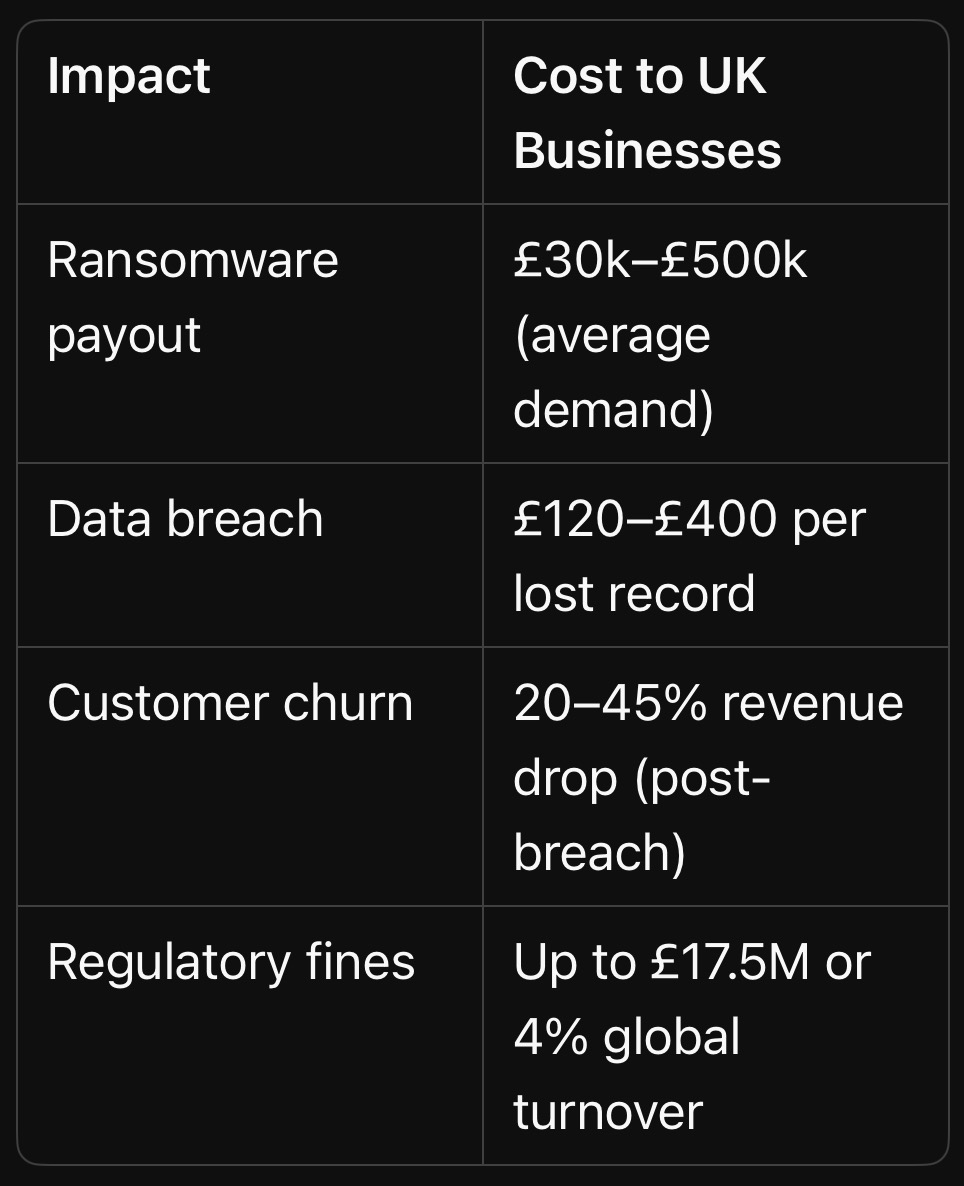
Global insolvencies are forecast to rise again in 2027—the fifth consecutive annual increase. BusinessRiskTV outlines the key risks facing businesses and 9 risk controls leaders should implement now to mitigate impact or seize new opportunities.
Business insolvencies rise again in 2027. Discover the 9 risk controls business leaders must act on now—and why waiting to react is a costly gamble.
Why Is Waiting Until 2027 to Prepare for Business Disruption a Strategic Gamble You Cannot Afford?
BusinessRiskTV Business Risk Management Club recommends key business decision makers consider proactive business risk management action now in preparation for 2027. The evidence is unambiguous: global business insolvencies are forecast to rise again in 2027, marking five consecutive years of increases, while the average business interruption claim now exceeds €850,000—roughly 70% higher than the average property damage claim that triggered it . Warren Buffett cut to the core of the issue: “Risk comes from not knowing what you’re doing” . If you do not know what is coming in 2027, you are already behind.
What Key Risks Are Facing Businesses in 2027?
Key risks facing businesses in 2027 include persistently high interest rates, geoeconomic confrontation, AI-driven competitive disruption, cyber dependency, and escalating insolvency contagion. The World Economic Forum’s Global Risks Report 2026 identifies geoeconomic confrontation as the top risk most likely to trigger a material global crisis, with economic downturn and inflation rising sharply in severity rankings . Allianz Trade forecasts global insolvencies will grow a further +1% in 2027, following +5% in 2026 and +6% in 2025, with 2.7 million jobs directly at risk across 2026 and 2027 . Meanwhile, PwC warns that the UK’s apparent resilience “should not be mistaken for a return to strong underlying growth,” and management teams should plan for a low-growth environment where financing conditions and input costs remain volatile.
Higher-for-longer interest rates: 60% of countries will maintain higher policy rates in 2027 than in the prior 12 to 24 months, inflating funding costs and squeezing margins
Geoeconomic confrontation: Trade fragmentation, export restrictions, and capital controls threaten supply chains and market access
AI competitive wedge: Early adopters pull ahead of laggards, accelerating insolvencies in smaller, less diversified markets
Cyber and technology dependency: Over 48,000 cloud and software outages were tracked in 2025 alone; cyber-related business interruption is becoming a more significant source of loss
Fiscal and debt instability: US fiscal stress was ranked as a leading global risk heading into 2027 at recent IMF meetings
Why Is Proactive Business Risk Management Preparation Important Now Instead of Waiting to React in 2027?
Proactive business risk management preparation is important now because the cost of reacting after a disruption materialises is demonstrably higher than the cost of preparing before it occurs. Splunk’s research across the Global 2000 found that the aggregate cost of downtime has soared to $600 billion annually—a 50% increase in just two years—translating to over $900,000 per hour for the average large organisation . Allianz Commercial’s analysis of 7,888 business interruption claims worth approximately €6.74 billion reveals that the average claim value increased by over 30% annually during the past two years, and recovery is taking longer due to supply chain delays, labour shortages, and volatile material costs . The Business Continuity Institute reports that 95% of organisations are now moving toward “incident-agnostic” planning—preparing for effects rather than specific causes—because the causes are becoming too numerous and interconnected to predict individually .
The cost asymmetry is brutal: A single outage event triggers an average 3.4% stock price drop, before accounting for brand damage and lost market position
Insolvency contagion is real: With 2.7 million jobs at risk across 2026–2027, your suppliers, customers, and partners are exposed—waiting to see who fails is not a strategy
Board-level engagement is already shifting: 45.4% of organisations now have a dedicated resilience lead reporting directly to the board, and 65.5% report increased financial support for continuity and resilience
The planning horizon has collapsed: UK CEOs report spending around 55% of their time on issues with horizons of less than one year, leaving dangerously little bandwidth for the structural risks crystallising in 2027 Daymond John’s warning is apt: “Don’t wait for the perfect moment—take the moment and make it perfect” . The perfect moment to prepare for 2027 is the present, when options remain open and costs remain controllable.
Who Will Benefit from Proactive Business Risk Management Now Instead of 2027?s
Business leaders who act now on proactive business risk management will benefit disproportionately compared to those who wait, because early movers capture both defensive protection and offensive market opportunities. The Business Continuity Institute’s 2025 report confirms that organisations are consolidating toward flexible, effects-based preparedness, with board engagement and resourcing strengthening amid global volatility . Companies that map their critical dependencies in advance and have practical recovery plans that can be activated immediately are demonstrably more resilient than those that improvise after the event . More provocatively, Allianz Trade’s research suggests that AI adoption can accelerate business insolvencies in smaller and less diversified markets due to the competitive wedge it creates between early adopters and laggards . The beneficiaries of proactive risk management are not just the cautious—they are the opportunists who position themselves to capture market share when weaker competitors falter.
Early adopters of AI and automation: They widen the productivity gap while laggards are still debating pilots
Boards with dedicated resilience leadership: Direct board reporting lines shorten decision speed and improve visibility
Organisations that exercise and test recovery plans: Not those that file them and forget them
Which Businesses or Industries Are Most at Risk from Potential Risk Events in 2027?
Construction, retail, and services are the most exposed sectors to potential risk events in 2027, according to Allianz Trade’s insolvency analysis, while energy-intensive European industries and technology-dependent businesses face compounding pressures. Europe accounts for almost 60% of jobs at risk (1.6 million), with France, Germany, and the UK leading the way; North America follows with 24% of total impacted jobs, representing a 13-year high for both regions . MSCI’s scenario analysis warns that in a disorderly AI transition, software and IT services fall furthest in the US and Canada, while energy-intensive cyclicals—airlines, autos, and capital goods—suffer under a supply-side energy squeeze . The message is uncomfortable: the industries that drove growth are the ones most exposed to the correction.
Construction and retail: Highest insolvency exposure, with thin margins and high sensitivity to interest rates and consumer demand
Software and IT services: Hardest hit in a disorderly AI transition scenario, with US software falling 26% and IT services 23% in MSCI’s modelled shock
Motor insurance and travel portals: AI-native competitors are already repricing risk and disintermediating traditional business models
Any business with concentrated production or supplier dependencies: A single fire at a semiconductor factory or a cyber incident at a logistics platform can cascade across thousands of organisations
What 9 Risk Controls Should Business Leaders Be Considering Now To Mitigate 2027 Impact or Seize Opportunities?
Nine risk controls business leaders should be considering now are scenario-based financial stress testing, supply chain dependency mapping, AI competitive positioning, cyber resilience investment, insurance adequacy review, dedicated board-level resilience leadership, incident-agnostic continuity planning, geopolitical exposure monitoring, and talent retention contingency planning. These controls address both the defensive imperative—surviving the disruption—and the offensive opportunity—capturing market share from unprepared competitors.
Run scenario-based financial stress tests against higher-for-longer rates: Model your debt service capacity if rates remain elevated through 2027, not just if they fall
Map tier-one and tier-two supplier dependencies by concentration risk: Identify where a single point of failure—geographic, single-supplier, or technology-platform—could halt your operations
Assess your AI competitive position honestly: Are you an early adopter widening the wedge, or a laggard about to be priced out? The competitive gap is accelerating in smaller markets
Invest in cyber resilience beyond baseline compliance:Cyber resilience is already the most well-resourced area, but over 48,000 cloud and software outages in 2025 show that third-party technology failure is a business interruption event
Appoint a dedicated resilience lead with direct board reporting: 45.4% of organisations have already done this, and reporting lines are shortening to improve decision speed
Why Is the “Wait and See” Approach a False Economy?
The “wait and see” approach is a false economy because the data consistently shows that reactive risk management costs more, recovers slower, and destroys more value than preparation. Allianz Commercial’s claims analysis demonstrates that business interruption losses are not determined by the initial event alone but by the speed at which an organisation can recover—and the most resilient companies are those that understand their critical dependencies in advance and have practical recovery plans that can be activated immediately . The Business Continuity Institute’s findings reinforce this: recognition of resilience as a standalone function has reached 45.5%, and 95% of organisations are moving toward incident-agnostic planning, because the causes of disruption are too varied and interconnected to predict individually . Yet nearly 55% of organisations cite resource constraints and 54.7% cite siloed systems or data as obstacles to full resilience integration . The gap between knowing what to do and doing it is where businesses fail.
The insolvency cycle has not peaked: Five consecutive years of increases, with the peak delayed to 2028, means the pressure does not lift after 2027
Recovery times are lengthening: Two years after Hurricane Helene, many business interruption claims remained unresolved not due to coverage disputes but because companies had not fully recovered
The AI disruption is not hypothetical: Lemonade’s autonomous vehicle policy wiped £1.3 billion off Admiral’s market value in five days in January 2026
Board attention is a scarce resource: Only 11% of UK CEOs’ time is spent on horizons beyond one year—the structural risks of 2027 will not get attention unless it is forced onto the agenda David Steward’s observation is the closing argument: “Your past does not define your future—your discipline does” . The discipline to prepare for 2027, while competitors react to 2026, is what will separate the businesses that emerge stronger from those that become a statistic in the next insolvency report.
#BusinessResilience2027 #RiskControlsNow
Get help to protect and grow your business faster with BusinessRiskTV
Proactive Business Resilience for 2027 Subscribe BusinessRiskTV
Waiting until 2027 to prepare is not risk management. It’s a bet your business can’t afford to lose.
Here’s the number that should keep you awake tonight: 2.7 million jobs are directly at risk across 2026 and 2027 from business insolvencies. That’s not a forecast from a doom-monger—that’s Allianz Trade’s insolvency analysis.
And 2027 marks the fifth consecutive year of rising global business insolvencies. Five. Years. In. A. Row.
Most business owners are still planning for a recovery that isn’t coming on the timeline they expect.
The brutal arithmetic:
→ Average business interruption claim: over €850,000
→ Average property damage claim that triggers it: around €500,000
→ The gap between the two? That’s the cost of being unprepared.
→ Cost of downtime for the Global 2000: 900,000 per hour for the average large organisation.
Still think “we’ll deal with it when it happens” is a strategy?
Here’s what the uncomfortable data actually shows:
The World Economic Forum ranks geoeconomic confrontation as the top risk most likely to trigger a material global crisis. PwC warns the UK’s apparent resilience “should not be mistaken for a return to strong underlying growth.” And MSCI’s scenario modelling shows software and IT services falling 26% and 23% respectively in a disorderly AI transition.
The industries that drove growth are the ones most exposed to the correction.
But here’s the part nobody talks about:
While 55% of organisations cite resource constraints as their barrier to resilience, 45.4% have already appointed a dedicated resilience lead reporting directly to the board. 95% are moving toward incident-agnostic planning.
The gap between knowing what to do and doing it is exactly where businesses fail.
Nine controls you should be actioning this quarter:
Stress-test debt service capacity against higher-for-longer rates
Map tier-one AND tier-two supplier concentration risk
Assess your AI competitive position honestly—adopter or laggard?
Invest in cyber resilience beyond baseline compliance
Review insurance declared values NOW (underinsurance is a silent killer)
Appoint a resilience lead with direct board reporting
Move from scenario-specific to incident-agnostic continuity planning
Monitor geopolitical exposure by jurisdiction
Build talent retention contingencies for critical roles
You’ve read nine controls. Most readers will nod and do nothing. The ones who act will capture market share from the ones who don’t. Which group are you in?
David Steward put it plainly: “Your past does not define your future—your discipline does.”
The discipline to prepare for 2027—while your competitors are still reacting to 2026—is what separates the businesses that emerge stronger from the ones that become a statistic in the next insolvency report.
Your move.
📧 For more information on the BusinessRiskTV Business Risk Management Club, contact editor@businessrisktv.com
👉 Save this post. Share it with your board. Then book the conversation.
Business risk management isn’t red tape—it’s the cheapest strategic advantage a UK SME has. This guide explains why risk management has never been more critical for SME survival, what it looks like in practice (a one-page risk register and a 30-minute monthly review), who benefits most, and when to use it in strategic, operational and project decisions. Includes 9 low-cost, high-impact tips and UK government and ONS data to back it up. Recommended by the BusinessRiskTV Business Risk Management Club.
Most UK SMEs ignore business risk management until it’s too late. Discover why it matters, what it looks like, and 9 practical tips to protect your business.
What Is Business Risk Management? A Practical Guide for Business Owners and Directors
BusinessRiskTV Business Risk Management Club recommends SME business owners and directors use business risk management philosophy and methodology to better protect and grow their business in UK. Here is the uncomfortable truth most SME owners avoid: you are already managing risk every day—you just aren’t calling it that. Every time you chase a late payment, wonder if your biggest client will renew, or hope your key engineer doesn’t quit, you are reacting to risk. The difference between surviving and thriving is whether you do it deliberately, or let it happen to you. With 5.7 million SMEs accounting for 99.9% of the UK business population and 60% of private sector employment , the collective cost of SME risk blindness is staggering. This guide is not about bureaucracy. It is about turning risk from a threat into a competitive weapon.
Why Has Business Risk Management Never Been More Critical to SME Performance, Growth and Survival in the UK?
Business risk management has never been more critical because UK SMEs now operate in a permacrisis of energy volatility, supply chain fragility, cyber extortion, and regulatory creep—where a single unmanaged shock can erase years of margin. Look at the data. In late October 2026, 77% of businesses with 10 or more employees expressed concern about energy prices, and 76% about fuel prices . Nearly two-thirds expected sourcing material costs to be impacted by supply chain concerns . This is not background noise. It is the operating environment.
The cyber threat is equally brutal. Government data shows 20% of businesses experienced a cyber crime in the last 12 months, with phishing affecting 18% of all businesses and ransomware hitting an estimated 19,000 businesses . For micro businesses, phishing is the most disruptive breach type, hitting 68% of those affected . Meanwhile, fraud incidents estimated by the Crime Survey for England and Wales reached 4.2 million in the year ending September 2025, with recorded fraud offences up 12% .
Here is the thought-provoking part: most SME owners would never dream of driving without insurance, yet they run their entire business without a risk register. As the old adage goes, “Risk comes from not knowing what you’re doing.” The SMEs that treat risk management as a luxury are the ones most likely to become a statistic.
What Does Business Risk Management Actually Look Like in Practice for a UK SME?
Business risk management in a UK SME looks like a one-page risk register, a monthly thirty-minute review, and a decision-making habit—not a forty-page policy document that nobody reads. It is identifying your top five risks, assigning a name to each, and asking one question every month: “Has this got better or worse?” ISO 31000, the international standard for risk management, defines it as a process of identifying, analysing, evaluating, treating, monitoring and communicating risk . But you do not need a consultant to do this. You need discipline.
In practice, it looks like this:
A risk register that lists your top ten risks, scored on likelihood and impact, with a named owner for each.
A cash flow stress test that asks: what happens if our biggest customer pays 30 days late, or disappears entirely?
A cyber hygiene checklist covering multi-factor authentication, phishing training, and backup protocols—because 93% of cyber crimes experienced by businesses are phishing.
A supply chain map that identifies single points of failure. The ONS found 64% of businesses with 10+ employees expected material sourcing costs to be impacted by supply chain concerns in October 2026.
A decision gate for every significant project or hire: what could go wrong, and what would we do if it did?The BusinessRiskTV Business Risk Management Club exists precisely because SMEs need a community, not a compliance manual. “You can’t control the weather, but you can build a stronger ship.”
Why Do Most SME Owners Resist Business Risk Management, and Why Are They Wrong?
Most SME owners resist business risk management because they equate it with insurance renewal paperwork and corporate box-ticking, when in reality it is the cheapest strategic advantage available to a small business. The evidence suggests a dangerous complacency. Only around 1.5% of UK SMEs apply for bank loans, reflecting a wider reluctance to engage with formal external finance and structured planning processes . If you won’t even fill in a loan application, you are almost certainly not running a risk register.
The resistance usually sounds like: “We’re too busy fighting fires to prevent them.” Or: “We know our business, we don’t need a spreadsheet to tell us what we already know.” But knowing something intuitively and managing it systematically are different things. The cyber data proves it: despite phishing being the most common cyber crime, many SMEs still do not train staff or enforce basic controls. The government’s Cyber Security Breaches Survey found that micro businesses were significantly more likely than larger firms to identify phishing as their most disruptive breach —precisely because they lack formal defences.
As Benjamin Franklin said, “An ounce of prevention is worth a pound of cure.” In SME terms, a £500 investment in phishing simulation training is cheaper than a single ransomware payment or the days of lost trading that follow a breach. Risk management is not a cost centre. It is a margin protection tool.
Who Will Benefit Most From Adopting Business Risk Management Philosophy and Practices?
The businesses that benefit most from business risk management are owner-managed SMEs with 5 to 100 employees, no dedicated risk function, and a high dependence on a small number of customers, suppliers, or key people. If you recognise yourself in that description, you are the person this is written for. The FSB reports that 5.6 million small businesses (0–49 employees) make up 99.2% of the total business population . The vast majority are owner-led, resource-constrained, and exposed.
Beyond that core group, the beneficiaries split into three categories:
Directors with personal guarantees or director loan accounts: unmanaged business risk is personal financial risk. A risk register that flags cash flow fragility is a director protection tool.
Businesses bidding for larger contracts or public sector work: procurement teams increasingly ask for evidence of risk management. A simple register signals competence and credibility.
SMEs in regulated sectors or supply chains with larger customers: the FCA’s Consumer Duty regime, for example, requires firms to evidence good outcomes and mitigate foreseeable harm. Risk management is becoming a commercial prerequisite, not a choice.The BusinessRiskTV Business Risk Management Club is built for exactly these people. “I have seen many businesses fail due to lack of planning, these workshops will provide you with the tools to plan.”
When Should Business Owners and Directors Use Business Risk Management in Strategic, Operational and Project Decision Making?
Business owners should use business risk management at three specific trigger points: before committing irreversible capital, before signing a contract that concentrates exposure, and before launching a project with a fixed deadline and no contingency. Outside these triggers, risk management should be a light-touch monthly rhythm, not a daily obsession.
Strategic decisions—acquisitions, new premises, major hires, entering new markets—demand a pre-mortem. Ask: “If this fails in twelve months, what will the most likely cause be?” The ONS shows 21% of businesses with 10+ employees were concerned about cyber attacks impacting supply chains in late 2026, up 9 percentage points year-on-year . A strategic decision to onboard a new critical supplier without a cyber assessment is a risk you can now see coming.
Operational decisions—pricing changes, credit terms, staffing levels—require a cash flow sensitivity check. If you extend payment terms to win a contract, what does that do to your working capital buffer? If you lose your second-in-command, what breaks?
Project decisions—a website rebuild, a new product line, a regulatory compliance programme—need a simple risk log with three columns: what could go wrong, how likely is it, what will we do about it. Review it at every project meeting. That is it. No software required.
As the old saying goes, “Fail to plan, plan to fail.” But the modern SME version is sharper: fail to identify the specific way you might fail, and you will almost certainly walk straight into it.
What Are the 9 Practical Tips to Adopt Business Risk Management in an SME That Has Struggled to See the Worth?
The nine practical tips to adopt business risk management in a sceptical SME are deliberately low-cost, low-time, and high-impact—designed to prove value within ninety days rather than demand a leap of faith. Each tip below is something you can start this week.
Start with a one-page risk register, not a framework. List your top ten risks. Score each 1–5 for likelihood and 1–5 for impact. Multiply them. Anything above 15 gets a named owner and a monthly review. Do not buy software. Use a spreadsheet.
Run a thirty-minute monthly risk huddle. Put it in the diary. Same time every month. Agenda: what changed, what got worse, what are we doing about it. This single habit is the difference between a living process and a dead document.
Stress-test your cash flow against a 30-day late payment from your biggest customer. If that scenario would break you, you have found your number one risk. The ONS energy and fuel concern data shows how quickly external shocks hit margins . Cash is the risk that kills fastest.
Treat cyber as a business continuity risk, not an IT problem. Enable multi-factor authentication everywhere. Run a phishing simulation. Check your backups restore properly. Government data shows phishing accounts for 93% of cyber crimes experienced by businesses . You do not need a cyber security degree to close the front door.
Map your critical dependencies. Who are the three customers, three suppliers, and three people you could least afford to lose? Write down what happens if each disappears tomorrow. Then ask what a 10% concentration reduction would look like over twelve months.
Put a risk question on every board agenda. One item: “What is the biggest risk we are currently ignoring?” This normalises the conversation and surfaces blind spots before they become crises.
Use a pre-mortem for every significant decision. Before you commit, gather the people involved and ask: “It is twelve months from now and this decision has failed. What went wrong?” The answers become your mitigation plan. This takes twenty minutes and costs nothing.
Build a simple incident response card for each top risk. If X happens, who calls who, what do we do first, where is the information? A single side of A4 per risk. Store it where you can find it when stressed. Because you will be stressed.
Measure one thing: risk actions completed. Not risks identified. Not documents written. Actions completed. This keeps the process honest and proves value. If the register grows but nothing changes, you are doing theatre, not management. The BusinessRiskTV Business Risk Management Club recommends this philosophy because it respects the two things SME owners never have enough of: time and money. “Risk management is not about avoiding risk. It is about knowing which risks are worth taking.
What Does Success Look Like for an SME That Embraces Business Risk Management?
Success looks like fewer surprises, faster recovery, and the confidence to take bigger swings because you understand the downside. It is not the elimination of risk—that is impossible and undesirable. It is the transformation of risk from a source of anxiety into a source of advantage.
You will know it is working when:
A key customer goes quiet and you already have a cash buffer plan in motion.
A phishing email lands and your team reports it instead of clicking it.
A supplier fails and you have a pre-identified alternative.
You bid for a contract you would have previously avoided because you can evidence your controls.
You sleep better, because the monsters under the bed have names and sizes.
The UK SME sector is the engine of the economy . But engines need maintenance. Business risk management is that maintenance. It is not glamorous. It is not a growth hack. It is the quiet discipline that separates the businesses that last from the ones that become a cautionary tale. The BusinessRiskTV Business Risk Management Club exists to make that discipline accessible, practical, and worth the time. Subscribe. Join the Club. Build a stronger ship.
Get help to protect and grow your business faster with BusinessRiskTV
Business Risk Management UK – Protect Grow Survive
Your business doesn’t have a growth problem. It has a risk problem you’ve been calling “bad luck.”
Three late payments. One supplier that vanished. A key client who went quiet in Q3. You called it a rough patch. It wasn’t. It was unmanaged risk — and it cost you more than you’ve admitted to yourself.
Here’s what the data says, and it isn’t comfortable:
77% of UK businesses with 10+ employees are worried about energy prices. 76% about fuel. 20% experienced a cyber crime in the last 12 months. And 93% of those cyber crimes? Phishing — the cheapest attack to defend against and the one most SMEs ignore.
You wouldn’t drive without insurance. Yet most SME owners run the entire business without a one-page risk register.
That’s not brave. That’s exposed.
What actually drives performance is what we layer on top:
A one-page risk register. Ten risks. Scored. Named owners. Reviewed monthly.
A 30-minute risk huddle in the diary. Same time every month. Non-negotiable.
A cash flow stress test: what happens if your biggest customer pays 30 days late?
A pre-mortem before every big decision: “It’s 12 months from now and this failed. Why?”
One measure that matters: risk actions completed — not documents written.None of this costs money. All of it costs discipline. That’s the trade most owners refuse to make — and it’s why the same businesses keep getting surprised by the same shocks.
The BusinessRiskTV Business Risk Management Club recommends SME owners and directors adopt risk management philosophy and methodology to better protect and grow their business in the UK.
The businesses that last aren’t the ones that avoid risk. They’re the ones that name it, size it, and plan for it before it arrives.
Want the practical version — the register template, the monthly huddle agenda, the pre-mortem script? Email editor@businessrisktv.com for more information on the Business Risk Management Club.
Save this. Share it with the director who still thinks “we know our business” is a risk strategy.
UK businesses face mounting financial and operational disruption heading into 2027, yet many boards still treat resilience as a cost rather than a survival strategy. This post reveals why preparation now is not money wasted, nine practical ways to prepare, the key mistakes leaders make, and where to find cost-effective UK resources. BusinessRiskTV Business Risk Management Club recommends acting before disruption — not after.
Business resilience in 2027: why preparation is not money wasted, 9 ways to prepare now, key mistakes UK leaders make, and where to find free UK support.
Business Resilience in 2027: The £11.7 Billion Warning UK Leaders Cannot Ignore
BusinessRiskTV Business Risk Management Club recommends building business resilience in preparation for known and unknown risk events in 2027 and beyond. The evidence is damning: UK large businesses absorbed an estimated £11.7 billion in cyber-attack costs in a single year, with £3.7 billion of that spent defending shareholder litigation rather than preventing the breach in the first place . That is not a technology problem. That is a boardroom failure of foresight, prioritisation, and courage. As Winston Churchill allegedly put it: “Let our advance worrying become advance thinking and planning.” Too many UK leaders are doing neither.
Why is preparation now to build business resilience not money wasted?
Preparation now is not money wasted because resilience spending is an ROI-positive insurance premium against catastrophic loss, not an overhead to be trimmed. Grant Thornton’s Enterprise Resilience Survey found that 69% of highly profitable companies build redundancy and flexibility into cost programmes, compared with only 26% of less profitable respondents . The gap between winners and losers is not luck. It is whether leaders treat slack, backup systems, and supplier diversity as strategic assets or as waste. Gallagher and CEBR data proves the point brutally: large UK firms spent just £226 million on external incident response support, yet £5.4 billion on direct trading losses from disruption . The ratio is roughly 24:1. Every pound not spent on preparation is a pound multiplied in consequence. As Benjamin Franklin wrote, “An ounce of prevention is worth a pound of cure” — a cliché only because so few actually act on it.
What are the 9 ways to prepare now for an uncertain 2027?
Nine ways to prepare now include stress-testing financial exposure, diversifying supplier concentration, and embedding resilience accountability at board level. PwC’s Risk Agenda 2027 warns that UK CEOs spend only 11% of their time on issues beyond a five-year horizon, while 55% is consumed by sub-one-year concerns . That is strategic inertia dressed up as busyness. Here is what decisive leaders should do:
Map single points of failure across suppliers, systems, and key customers. Nearly half (47%) of UK businesses generate more than half their sales from their top three customers — a revenue concentration risk that turns one lost account into an existential event.
Stress-test cashflow against a “no-main-system” scenario. 57% of UK businesses admit they could not continue sales order processing or purchasing if their main system failed.
Lock in financing before you need it. Lloyds data shows 75% of businesses claim they have the right financial tools, yet only 46% use cashflow forecasting and 30% have working capital facilities in place . Confidence without capability is delusion.
Build redundancy into cost-cutting programmes. 52% of UK firms have only partly commenced strategies to avoid financial losses from supply chain disruption; 14% have no strategy at all.
Run scenario exercises that assume the worst. PwC’s Minimum Viable Company framework urges boards to define what operations are truly non-negotiable before disruption hits, not during it.
Diversify supplier geography and logistics routes. Geopolitical instability in 2027 — from trade barriers to energy shocks — rewards those who are not dependent on a single corridor or vendor.
Insure for the second-order costs, not just the first. 88% of large UK firms have cyber insurance, but only 59% are covered for third-party legal claims — the exact cost that reached £3.7 billion last year.
Cross-train staff and document institutional knowledge. PwC recounts a bank whose international payments system went offline for three days because the one employee with the back-end password was hiking without internet . That is not bad luck. That is bad management.
Make resilience a standing board agenda item with named ownership. Business in the Community’s research found many firms are “unaware” of Local Resilience Forum support or simply lack the capacity to engage — a failure of curiosity and prioritisation.
What are the key mistakes business leaders often make when trying to build business resilience?
The key mistake business leaders make is treating efficiency as the opposite of resilience, cutting slack until the organisation snaps at the first shock. Grant Thornton’s Joe Mulligan put it plainly: “Lean is good up to a point. But cut too far and you weaken the muscle organisations need to perform” . The second mistake is assuming resilience is an IT project. It is not. It is a capital allocation decision, a supplier relationship decision, and a board governance decision. The third mistake is waiting for certainty. PwC notes that UK corporate debt is around its lowest level this century, yet business investment remains below its pre-2016 trend — healthy balance sheets are being hoarded, not deployed into resilience . As the old saying goes, “You can’t control the wind, but you can adjust the sails.” Too many UK boards are arguing about the forecast instead of trimming the canvas.
Who are the often-guilty key decision makers at fault?
The often-guilty key decision makers at fault are CEOs, CFOs, and boards who prioritise quarterly earnings over multi-year survivability. The UK government has written directly to FTSE 350 Board Chairs demanding cyber resilience be a top priority — a signal that ministers believe voluntary boardroom attention has failed . The Business Continuity Institute found that while 67.8% of organisations claim a board member is ultimately accountable for resilience, the CEO specifically holds that accountability in only 26.5% of cases, down from 39.5% the previous year . Accountability is being diffused, delegated, and diluted. Meanwhile, PwC’s data shows UK CEOs spending more than half their time on sub-one-year issues . The guilty party is not the risk manager who flagged the vulnerability. It is the executive who nodded, thanked them, and moved to the next slide. As John F. Kennedy observed, “The time to repair the roof is when the sun is shining.” UK boardrooms have had years of sunshine. The clouds are gathering.
When are key business decision makers involved in building business resilience?
Key business decision makers are involved in building business resilience far too late — typically after a disruption has already crystallised losses, not before. The SCALA research is unambiguous: over half of UK businesses have only partially begun strategies to protect against financial loss from supply chain disruption, and 14% have done nothing . This is involvement as firefighting, not foresight. The correct timing is continuous and embedded: resilience should sit on every board agenda, every capital allocation decision, and every supplier review. Lloyds data shows 59% of firms are adjusting strategy in response to uncertainty — but adjustment after the fact is not preparation; it is damage limitation . The Business in the Community report captures the fatalism: “Until we are in a situation, we don’t think about it and therefore react — rather than adopt a proactive approach” . That quote should be printed on the wall of every UK boardroom as a warning.
Where in the UK can you find resources to help you prepare most cost-effectively?
The most cost-effective UK resources are free, publicly funded, and embarrassingly underused: Local Resilience Forums (LRFs), Business Continuity Institute guidance, and government-backed cyber resilience tools. Leicestershire County Council’s LRF offers free webinars, business continuity plan templates, and industry-led tools through its Risk Ready Businesses page . This is not diluted advice — it is practitioner-built, locally tailored, and costs nothing but the time to engage. Business in the Community’s research found that many businesses simply do not know their LRF exists, or lack the capacity to reach out . That is an unforgivable excuse when the alternative is a £3.7 billion litigation bill . The National Cyber Security Centre provides free board-level cyber guidance, and the UK Government Resilience Framework explicitly calls for “active partnership” between business and government . The resources exist. The will does not. As Sun Tzu wrote, “In the midst of chaos, there is also opportunity” — and the opportunity here is to prepare cheaply now rather than expensively later.
The Bottom Line for 2027
UK business leaders have been warned. The data is public, the costs are quantified, and the tools are free. What is missing is the uncomfortable honesty that resilience is not a cost centre but a survival function. The £11.7 billion in cyber losses, the 57% of firms that cannot process orders if their main system fails, the 14% with no supply chain strategy at all — these are not statistics. They are indictments . BusinessRiskTV Business Risk Management Club exists for leaders who refuse to be part of that indictment. Prepare now. The alternative is paying later, with interest.
Your board just approved a £2m cost-cutting programme. Congratulations — you may have just funded your own disruption.
Here’s the uncomfortable number: 69% of highly profitable UK companies build redundancy into their cost programmes. Only 26% of less profitable ones do. That gap isn’t luck. It’s a decision.
And the cost of getting it wrong is brutal.
UK large businesses absorbed an estimated £11.7 billion in cyber-attack costs in a single year. £3.7 billion of that went on defending shareholder litigation — not on stopping the breach.
Read that again. They paid lawyers after the damage. They didn’t pay for prevention before it.
Meanwhile:
→ 57% of UK businesses admit they couldn’t process sales orders or purchasing if their main system failed.
→ 14% have no supply chain disruption strategy at all.
→ CEOs spend just 11% of their time on anything beyond a five-year horizon.
That last one should sting. The future is arriving in 2027 whether your board agenda is ready or not.
So here’s the question that separates survivors from statistics:
If your main system went down tomorrow morning, how many days of trading would you lose?
If you can’t answer that in under 10 seconds — you’ve just found your first resilience gap. And you’re not alone.
The uncomfortable truth is that most UK leaders aren’t short of information. They’re short of the courage to spend money on something that hasn’t gone wrong yet.
Winston Churchill reportedly said: “Let our advance worrying become advance thinking and planning.”
Too many UK boardrooms are doing neither. They’re waiting for certainty that will never arrive.
The good news? The most cost-effective resilience resources in the UK are free — Local Resilience Forums, Business Continuity Institute guidance, and NCSC board-level cyber tools. The reason they go unused isn’t cost. It’s curiosity.
Free tools. Public data. Quantified risk. And still, 14% of firms have no supply chain strategy.
You don’t get to call that bad luck. That’s bad management.
Traditional risk registers create the illusion of control while blinding UK business leaders to interconnected threats and opportunities. This article explains why holistic enterprise risk management is the solution to faster, safer business growth — and gives 9 practical ways to embed it in strategic, operational and project decisions.
Traditional risk registers are failing UK businesses. Discover why holistic enterprise risk management protects and grows your business faster — 9 practical ways.
Why Traditional Risk Registers Are Killing UK Business Growth — And How Holistic Enterprise Risk Management Fixes It
BusinessRiskTV Business Risk Management Club recommends holistic enterprise risk management methodology as the solution to the problem of protecting and growing a business faster in UK. The traditional risk register is not just inadequate — it is actively dangerous for any UK business leader who wants to grow, because it creates the illusion of control while blinding you to the interconnected threats and opportunities that actually determine whether your business thrives or dies. The ICAEW declared in February 2026 that “ERM as enterprise list management is dead,” warning that risk registers “grow longer, not sharper” while risk discussions remain “disconnected from strategy and capital decisions” . If your business risk management still revolves around a spreadsheet that gets updated once a quarter, you are not managing risk — you are managing paperwork. And your competitors who have embedded holistic enterprise risk management into every strategic, operational and project decision are already pulling ahead.
What is holistic enterprise risk management?
Holistic enterprise risk management is a company-wide approach that identifies, assesses, manages and monitors all risks — strategic, operational, financial and regulatory — as an interconnected system rather than as isolated items on a list . It moves beyond the traditional risk register’s static, point-in-time snapshot and instead embeds risk intelligence into the daily decision-making of the business, from the boardroom to the front line. FERMA, the Federation of European Risk Management Associations, defines the evolved approach as one where “risk, opportunity and strategy are managed in harmony to sustain long-term enterprise resilience,” explicitly shifting from a “purely threat-focused approach to one that emphasises value creation” . In practical UK terms, holistic ERM asks not “what risks do we have?” but “what outcomes must we continue to deliver, whatever happens?” — a fundamental reframing that the ICAEW argues is essential for survival in 2026’s polycrisis environment.
Why are traditional risk registers no longer enough for UK businesses in 2026?
Traditional risk registers are no longer enough because they are static, siloed and backward-looking in a business environment where threats are interconnected, fast-moving and increasingly technological. The ONS reported in November 2026 that 21% of UK businesses with 10 or more employees were concerned about cyber attacks impacting supply chains over the next year — a 9 percentage point increase from September 2025 — while 12% were concerned about artificial intelligence, the highest proportion since the question was introduced . A risk register that lists “cyber risk” as a single line item with a likelihood score of 3 and an impact score of 4 tells you nothing about how a supplier breach in one jurisdiction cascades into operational disruption, regulatory exposure and reputational damage simultaneously. Pinsent Masons warned in 2026 that controls are “degrading assets” and that static residual risk ratings are “increasingly detached from operational reality” because they fail to capture how inherent risk, control effectiveness and residual risk move together . Vanta’s 2026 research found that spreadsheets remain the most widely used GRC tool — yet they “won’t support ERM programs” because they “reinforce siloed, point-in-time risk oversight” . The register is not a management tool. It is a comfort blanket.
Who will benefit from embedding holistic enterprise risk management in business decision making?
Every UK business leader who makes decisions under uncertainty will benefit — but the gains are most dramatic for owners, directors, CFOs and risk managers in businesses with more than 10 employees operating across multiple risk domains. FERMA’s 2026 white paper explicitly calls for corporate risk management to be recognised “not as a technical or compliance function” but as “a strategic capability that supports enterprise-wide resilience and growth” . The beneficiaries are not just risk professionals. They are the CEO who needs to know whether a supply chain diversification decision will actually reduce exposure or simply shift it; the CFO who needs to quantify the correlation-adjusted impact of two simultaneous risks rather than scoring them separately; and the board director who needs to demonstrate to regulators and investors that risk oversight is active, not theatrical. The ONS found that 38% of businesses with 10 or more employees were concerned about international conflict impacting supply chains in April 2026 — a 28 percentage point rise from December 2025 — and 44% of importing businesses reported increased importing costs . Those businesses need integrated intelligence, not a longer list.
When will holistic enterprise risk management deliver positive results for a business?
Holistic enterprise risk management delivers positive results when it is embedded into the rhythm of decision-making — not when it is treated as an annual compliance exercise — with early wins typically visible within the first two to three decision cycles. The ICAEW’s 2026 analysis is blunt: traditional ERM fails because it asks “what risks do we have?” rather than “what outcomes must we continue to deliver, whatever happens?” . The shift to holistic ERM begins delivering value as soon as leadership starts using risk intelligence to inform capital allocation, project approval and strategic prioritisation. FERMA’s vision is of an ecosystem where “risk management is a cornerstone of sustainable success” — a continuous capability, not a periodic deliverable . In practical terms, the first results appear when a business stops scoring risks in isolation and starts debating which risks matter to the strategy, which opportunities are being missed because they look risky on a register, and which controls are actually degrading silently beneath the surface.
Which UK businesses will benefit most from a holistic enterprise risk management approach to strategic, operational and project decision making?
UK businesses with complex operations, multiple risk exposures, growth ambitions or regulatory scrutiny will benefit most — and the evidence suggests that nearly every business with 10 or more employees now falls into at least one of those categories. The ONS November 2026 data shows 31% of businesses with 10 or more employees concerned about international conflict impacting supply chains, 21% concerned about cyber attacks, 12% concerned about AI, and 12% concerned about climate change . A small consultancy with one office and no supply chain does not need holistic ERM. But a manufacturer importing components, a professional services firm handling client data across jurisdictions, a construction company managing project risk across multiple sites, or a technology business deploying AI tools without a governance framework — these are the businesses where the gap between a risk register and holistic ERM is the difference between resilience and ruin. FERMA’s 2026 white paper recommends “flexible” ERM frameworks that adapt to different organisational contexts, precisely because a one-size-fits-all register approach fails businesses of different shapes and exposures.
How does holistic enterprise risk management improve business performance and create value?
Holistic enterprise risk management improves business performance by connecting risk intelligence directly to strategy, capital allocation and opportunity capture — turning risk from a cost centre into a value driver. FERMA’s CEO Laurent Nihoul states it plainly: risk management should be “not merely a defensive mechanism, but an integrated system that both protects and enables value creation” . The old model treated risk as something to be minimised. The holistic model treats risk as something to be understood, priced and exploited where the reward justifies the exposure. As the ICAEW’s 2026 article argues, “there is no return without risk” — boards should be asking “where do I want to be risk seeking?” rather than only “what could go wrong?” . This is not semantic gymnastics. It changes which projects get funded, which markets get entered, which suppliers get diversified and which talent gets hired. A business that understands its risk appetite can move faster into opportunity because it knows which risks it is equipped to take.
What are 9 practical ways to use holistic enterprise risk management methodology to protect and grow a UK business faster?
These nine practical applications of holistic enterprise risk management methodology will protect and grow a UK business faster by replacing static compliance with dynamic decision intelligence.
Replace the single risk register with a risk universe hierarchy that separates enterprise-level, business-unit and project-level risks, so the board sees the interconnected picture while operational teams manage granular exposure.
Run correlation-adjusted risk scenarios that model two or more simultaneous risks — because more than 80% of the largest value-destroying risk events involve multiple concurrent risks, according to actuarial research.
Embed risk appetite thresholds into capital allocation and project approval gates, so that no material investment proceeds without an explicit statement of which risks are being accepted and why.
Treat controls as degrading assets that require continuous monitoring, not annual attestation — Pinsent Masons warns that documented controls can remain unchanged while actual effectiveness deteriorates silently.
Integrate AI and technology governance directly into risk governance, because automated decision tools are now controls in their own right and cannot be assessed as effective if the underlying models and data are not.
Use horizon scanning and scenario planning as a standing board agenda item, not an annual workshop, to anticipate the interconnected risks that a static register cannot see.
Assign named owners to every material risk and control, with decision rights escalating by severity — routine tolerance within business units, material risk acceptance to the executive or board.
Measure risk management by outcomes protected and opportunities captured, not by the number of risks logged or the completeness of the register — the ICAEW’s critique is that time is spent “scoring risks rather than debating what truly matters”.
Build a risk-aware culture where escalation is rewarded, because the ONS data shows that concerns about supply chain, cyber and AI risks are rising simultaneously — and the businesses that hear about problems early are the ones that survive them.
What do famous thinkers say about the benefits of managing business risks better?
Warren Buffett warned that “risk comes from not knowing what you’re doing” — a direct indictment of the risk register mentality that logs threats without understanding their interconnections . Peter Bernstein, author of Against the Gods, defined the essence of risk management as “maximising the areas where we have some control over the outcome while minimising the areas where we have absolutely no control over the outcome” . That is precisely what holistic ERM does: it identifies where control is possible, where exposure is unavoidable, and where the two intersect with strategy. Tom Gilb’s warning is perhaps the most urgent for UK business leaders in 2026: “If you don’t actively attack the risks, they will actively attack you” . And Buffett’s most famous risk aphorism — “only when the tide goes out do you discover who’s been swimming naked” — is a reminder that the businesses with thin risk management will be exposed first when the next supply chain shock, cyber incident or regulatory change arrives.
Why is the traditional risk register costing UK businesses money?
The traditional risk register costs UK businesses money because it consumes resources while failing to prevent the losses it is supposed to avert — and it blinds leadership to the opportunities that holistic risk management would capture. The ONS November 2026 data shows that 69% of UK businesses expressed concern about energy prices and 70% about fuel prices, with 77% of larger businesses concerned about energy . A register that lists “energy cost risk” as a line item does nothing to help a manufacturer model the correlation between energy prices, shipping costs and customer demand — or to decide whether to hedge, diversify suppliers or pass costs through. Pinsent Masons identifies the deeper cost: static risk assessments create “artificially low” residual risk reporting that is “detached from operational reality,” meaning boards are making decisions on false intelligence . The cost is not just the software licence or the risk manager’s salary. It is the bad decisions made on the basis of a false sense of security.
Who is the key business decision maker that must own holistic enterprise risk management?
The CEO owns holistic enterprise risk management, because risk and strategy are inseparable — and delegating it to a compliance function guarantees it will fail. FERMA’s 2026 white paper explicitly argues that corporate risk management should be “recognised as a strategic capability” rather than a technical or compliance function, and that governance, management and assurance functions must collaborate to shift “from a control-oriented mindset towards a proactive approach” . The ICAEW’s 2026 analysis of board risk oversight notes that the UK Corporate Governance Code places “clear expectations on boards to establish a robust framework for risk management and internal control,” and that effective practice “extends beyond compliance” to active oversight, alignment between strategy and risk appetite, and a culture of early escalation . The CEO cannot outsource this to the risk manager any more than they can outsource strategy to the finance team. The risk manager provides the intelligence. The CEO makes the decisions. But in a holistic ERM model, those decisions are informed by a continuous, integrated understanding of risk and opportunity — not a quarterly spreadsheet review.
What UK government and independent data proves holistic risk management is value for money?
The independent evidence from respected UK and European risk bodies proves that holistic risk management delivers value for money by preventing losses that static registers fail to catch. The ICAEW declared traditional ERM “dead” in 2026, citing McKinsey’s finding of “declining confidence in traditional risk frameworks, particularly in addressing emerging and interconnected risks linked to technology, resilience, and long-term value” . FERMA’s 2026 white paper represents the consensus of the European risk management profession: risk management must be repositioned “as a strategic driver of organisational value rather than a defensive function” . The ONS data provides the urgency: cyber concern impacting supply chains rose 9 percentage points year-on-year to 21% of larger businesses, AI concern hit its highest level since the question was introduced at 12%, and international conflict concern stood at 31% in November 2026 . These are not risks that can be managed by adding lines to a register. They require the integrated, forward-looking intelligence that only holistic ERM provides. The value for money case is simple: the cost of embedding holistic ERM is a fraction of the cost of a single unmanaged correlated risk event — and the opportunity cost of missing growth because your risk framework cannot distinguish between a threat to avoid and a risk worth taking is incalculable.
BusinessRiskTV Business Risk Management Club exists for UK business leaders who refuse to accept the comfort blanket of the traditional risk register. We operate outside standard structures to attract pure abundance — continuous business expansion, optimal health and resilience, and wealth creation for the risk manager who has the courage to challenge orthodoxy. The ICAEW says ERM as we know it is dead. FERMA says risk must enable value creation. The ONS data says the threats are rising and interconnected. The only question is whether you will keep updating the register while your competitors embed holistic risk management and grow faster. The choice is yours.
FERMA — White Paper on Building Organisational Value Through Strategic Risk Management (source for core statements such as “risk management is not merely a defensive mechanism but an integrated system that protects and enables value creation”) https://ferma.eu/buildingorganisationalvaluethroughstrategicriskmanagement/
Peter Bernstein — “The essence of risk management lies in maximising the areas where we have some control over the outcome while minimising the areas where we have absolutely no control over the outcome.” (Goodreads citation) https://www.goodreads.com/quotes/list/7606719-patrick-mak
Your risk register is not protecting your business. It is lying to you.
And it has been for years.
Here is the uncomfortable truth most UK boardrooms will not say out loud: a spreadsheet with 47 risks scored “likelihood 3, impact 4” is not risk management. It is theatre. It is a comfort blanket that makes directors feel prudent while the actual threats — the ones that move fast, connect to each other and destroy value — pass straight through the gaps.
Don’t take my word for it. In 2026, the ICAEW declared traditional ERM “dead,” warning that risk registers “grow longer, not sharper” while staying “disconnected from strategy and capital decisions.” Pinsent Masons went further: controls are “degrading assets,” and static residual risk ratings are “increasingly detached from operational reality.”
Translation? Boards are making decisions on false intelligence. And it is costing them.
Meanwhile, the ONS reported in November 2026 that:
21% of UK businesses with 10+ employees are worried about cyber attacks hitting supply chains — up 9 percentage points in a year
12% are concerned about AI — the highest level since the question was introduced
31% are concerned about international conflict disrupting supply chainsYou cannot manage those three risks on three separate lines of a register. They are connected. They compound. They arrive together.
That is why holistic enterprise risk management is not a nice-to-have. It is the difference between a business that grows through shocks and one that is exposed by them.
What actually changes when you embed it:
→ You stop scoring risks in isolation and start modelling correlation — because over 80% of the largest value-destroying events involve multiple concurrent risks
→ You separate enterprise, business-unit and project risk universes so the board sees the big picture and teams manage the detail
→ You build risk appetite thresholds into capital allocation and project approval gates — no material investment proceeds without naming which risks are being accepted and why
→ You treat controls as assets that degrade silently, not boxes ticked once a year
→ You measure risk management by outcomes protected and opportunities captured — not by how many rows are in the spreadsheet
Warren Buffett said it best: “Risk comes from not knowing what you’re doing.”
Peter Bernstein said it better: risk management is “maximising the areas where we have some control over the outcome while minimising the areas where we have absolutely no control.”
That is exactly what holistic ERM does. And the businesses doing it in the UK right now are not just safer — they are faster. They enter markets sooner, fund the right projects, diversify suppliers before the crisis hits, and grow while competitors are still updating column F.
Here is the retention question worth sitting with: if your risk register vanished tomorrow, what would actually change about how your business makes decisions?
If the answer is “nothing,” you do not have risk management. You have a document.
The ICAEW says ERM as we know it is dead. FERMA says risk must become a strategic driver of value creation, not a defensive function. The ONS data says the threats are rising and interlocking.
The only question left is whether you will keep updating the register while your competitors embed holistic ERM and grow faster.
BusinessRiskTV Business Risk Management Club exists for UK business leaders who refuse the comfort blanket. We operate outside standard structures — focused on continuous business expansion, optimal resilience, and creating real wealth for the risk manager with the courage to challenge orthodoxy.
Your next move: email editor@businessrisktv.com for more information on the Business Risk Management Club, and find out how to embed holistic enterprise risk management into your strategic, operational and project decisions — before the tide goes out.
#RiskRegisterIsDead #HolisticERM
Holistic Enterprise Risk Management: Why Risk Registers Fail UK Business
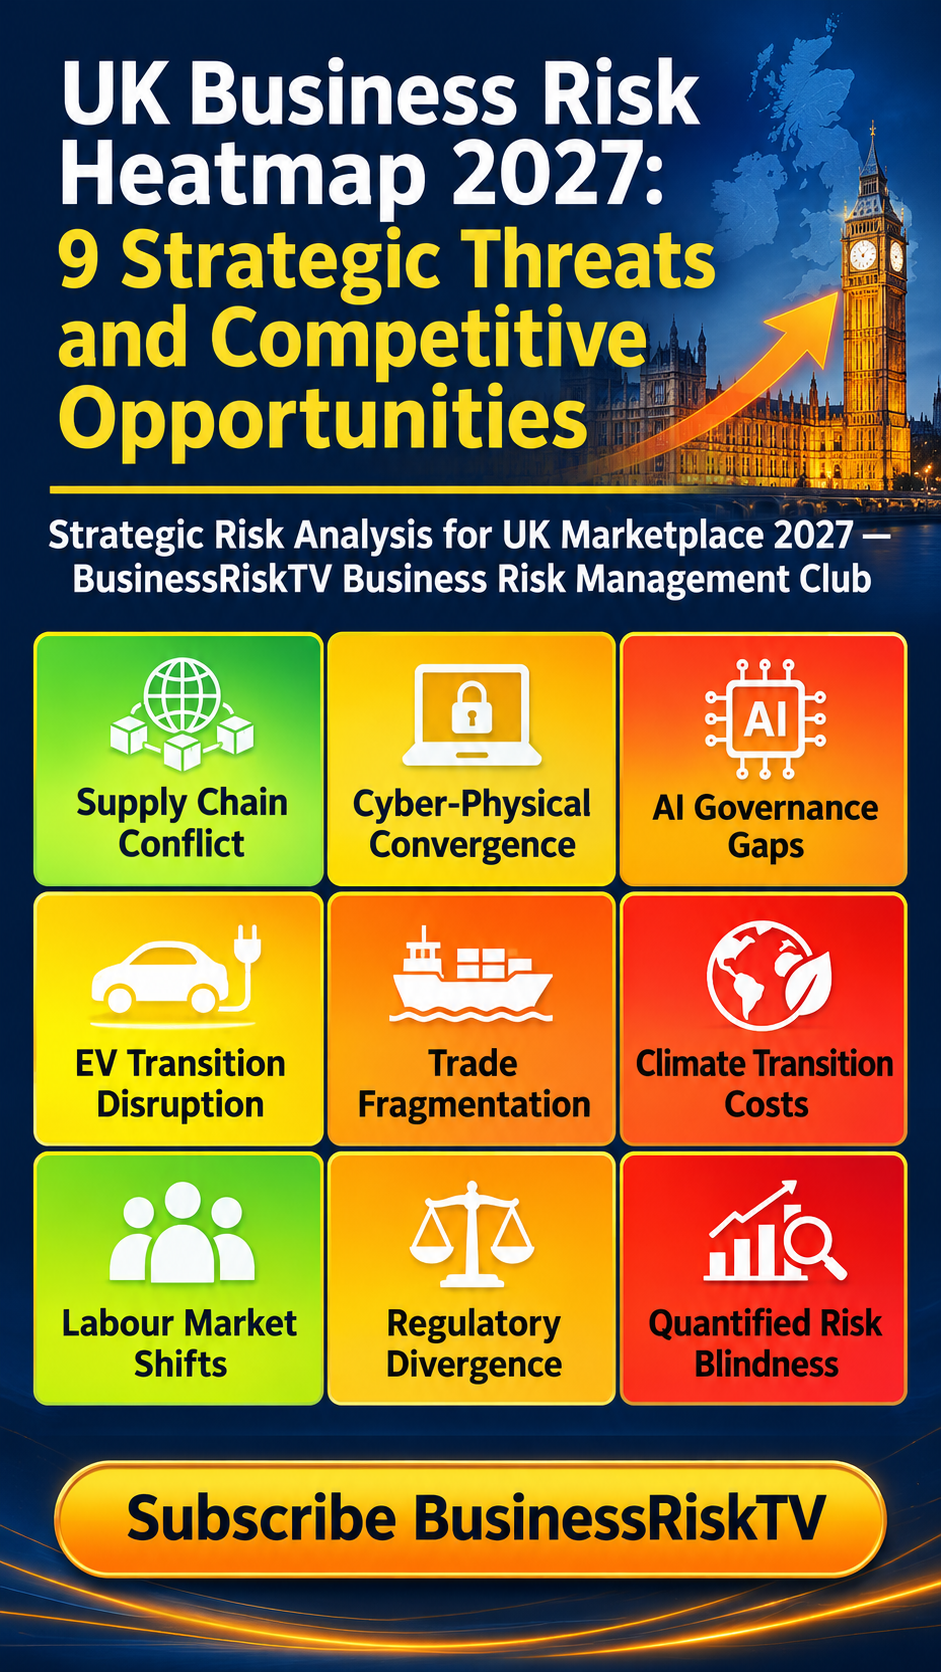
Strategic foresight gives UK businesses a competitive edge before 2027 threats crystallise. This BusinessRiskTV analysis identifies nine risks — from supply chain conflict to quantified risk blindness — with ONS and industry data, plus the steps decision-makers must take now to beat competitors.
Identify 9 strategic threats UK businesses face in 2027 and how to act now. BusinessRiskTV Business Risk Management Club strategic risk analysis.
Strategic Foresight 2027: How UK Businesses Can Identify Threats Before Competitors
BusinessRiskTV Business Risk Management Club Strategic Risk Analysis for UK Marketplace 2027 is the solution to the problem of strategic risk management in the UK for 2027. As the UK business landscape faces converging geopolitical, technological, and regulatory pressures, the window for reactive strategy is closing. The Office for National Statistics reported in May 2026 that 38% of UK businesses with 10 or more employees were already concerned about international conflict impacting supply chains—a 28 percentage point rise from December 2025 . BusinessRiskTV’s Business Risk Management Club provides the structured foresight framework UK decision-makers need to convert these early signals into competitive advantage before rivals react.
“The true sign of intelligence is not knowledge, but imagination.” — Albert Einstein, cited in INSEAD’s Distant Foresight Index research
Why Does Strategic Foresight Early Give a Competitive Advantage in the UK?
Strategic foresight early gives a competitive advantage in the UK because it enables businesses to shape regulatory environments, set industry standards, and define customer expectations before competitors recognise the threat. A firm that articulates a clear, well-researched vision of the future can effectively create the very future it is prepared to dominate . Shell’s pioneering scenario planning in the late 1960s anticipated a potential oil supply disruption; when the 1973 crisis hit, Shell was better prepared than competitors and gained a decisive advantage through diversification .
The financial case is stark. Aon’s 2026 UK report found that only 16% of UK firms have quantified their exposure to business interruption, and just 12.4% have quantified supply chain disruption exposure . Without quantification, senior leaders cannot make informed investment decisions or structure appropriate insurance programmes. Beazley’s January 2026 survey of 3,500 leaders across seven countries found that 94% of global businesses intend to build resilience through insurance and risk management in 2026, with 31% specifically planning to invest in risk management and loss prevention.
First-mover regulatory influence: Early foresight allows firms to engage with regulators before rules crystallise, shaping outcomes favourably
Talent and capital allocation: Identifying threats early enables redeployment of resources before sunk costs become stranded
Competitor blind spots: Most firms focus on immediate industry metrics; distant foresight captures weak signals beyond sector boundaries
Insurance and risk transfer pricing: Firms that quantify exposure early access better terms before insurers reprice systemic risks 
What Are 9 Potential Issues in 2027 That UK Businesses Must Prepare For Now?
Nine potential issues in 2027 that UK businesses must prepare for now include supply chain conflict exposure, cyber-physical convergence, AI governance gaps, EV transition disruption, geopolitical trade fragmentation, climate transition costs, labour market restructuring, regulatory divergence, and quantified risk blindness. Each represents a threat that can be converted into opportunity through structured foresight.
Supply chain conflict and shipping disruption will intensify in 2027, with ONS data already showing 25% of UK businesses concerned about shipping disruption in April 2026—up 18 percentage points from December 2025. Import costs increased for 44% of importing businesses in March 2026 compared with the previous year, the highest proportion since June 2023 . Act now: Map tier-2 and tier-3 suppliers for conflict-exposed regions; pre-negotiate alternative logistics routes; stress-test working capital against 20% freight cost increases.
2. Cyber-Physical Convergence and Business Interruption
Cyber-physical convergence will create business interruption events in 2027 that traditional risk frameworks cannot handle, with 27.3% of UK organisations already having suffered significant financial losses from business interruption. Beazley’s outlook warns that converging risks mean digital, transitional, and geopolitical disruption are creating simultaneous pressures across every part of the business . Act now: Quantify cyber-physical interdependencies; test incident response against a 5-day operational shutdown scenario; review insurance limits against modelled exposure.
3. AI Governance and Model Risk
AI governance and model risk will become a board-level regulatory issue in 2027, with financial services firms already facing Consumer Duty obligations that demand demonstrable oversight of automated decision-making. The FCA’s expectations and emerging AI regulation will require boards to evidence accountability. Act now: Establish an AI use-case register with risk ratings; implement model validation before deployment; train boards on AI accountability.
4. Electric Vehicle Transition Operational Disruption
Electric vehicle transition will disrupt operational models in 2027, with the Zero Emissions Vehicle Mandate reshaping the UK vehicle parc and creating different operational pressures for fleet-dependent businesses. The AA has already invested in specialist EV training and is progressively introducing EVs into its own fleet, converting transition risk into operational readiness. Act now: Audit fleet dependency on internal combustion maintenance skills; model EV charging infrastructure costs; retrain frontline staff.
5. Geopolitical Trade Fragmentation and Rules of Origin
Geopolitical trade fragmentation will raise compliance costs in 2027, with 39% of exporting businesses reporting increased exporting costs in March 2026—the highest since September 2023 . Act now: Review rules of origin documentation; model tariff scenarios for EU and US trade; consider nearshoring critical inputs.
6. Climate Transition Cost Pass-Through
Climate transition costs will accelerate in 2027, with Beazley identifying climate and environmental risk as representing 20% of average business risk concern globally. The European Space Agency’s foresight work warns that intensifying climate impacts will affect European economies through the investment required to build resilience and adopt mitigating technologies . Act now: Stress-test energy cost exposure; assess carbon border adjustment mechanism impact; identify quick-win efficiency investments.
7. Labour Market Restructuring and Skills Gaps
Labour market restructuring will create skills shortages in 2027 as AI adoption and green transition reshape demand, with 4% of UK businesses having temporarily paused trading and 2% permanently ceased by late April 2026 . Act now: Map critical skills against 2027 requirements; initiate reskilling programmes; review contingent labour strategies.
8. Regulatory Divergence Post-Brexit
Regulatory divergence will increase compliance complexity in 2027, requiring UK-specific frameworks for product marking, data, and financial services. The Food Standards Agency is already developing novel regulatory approaches for cell-cultivated products through its sandbox programme, signalling sector-specific divergence . Act now: Assign regulatory horizon scanning ownership; budget for dual compliance; engage with regulators early.
9. Quantified Risk Blindness
Quantified risk blindness will leave UK firms unable to justify resilience investment in 2027, with only 21.6% having a formal business interruption plan and just 16% quantifying exposure. Aon warns that without quantification, leaders struggle to make informed decisions or plan for the true cost of prolonged disruption . Act now: Commission quantitative risk assessment; link insurance limits to modelled loss scenarios; present board-level risk appetite statements.
What Steps Should Key Business Decision Makers Take Today to Beat Competitors in 2027?
Key business decision makers should today establish a structured distant foresight function, quantify their top three risk exposures, and integrate scenario planning into capital allocation. The INSEAD Distant Foresight Index approach helps organisations identify potentially destructive threats beyond industry boundaries, avoiding the fate of Blockbuster, Nokia, and Kodak . The European Space Agency’s foresight practice demonstrates that developing scenarios challenges assumptions and tests strategies against multiple futures, ensuring organisations remain proactive rather than reactive.
Appoint a foresight owner with board access, not buried in strategy or innovation teams
Run a 2027 threat quantification sprint covering business interruption, supply chain, and cyber, using structured financial modelling rather than intuition
Establish weak-signal monitoring across sectors beyond your own, using the INSEAD distant foresight methodology
Integrate foresight into FP&A so capital allocation is stress-tested across multiple scenarios, not a single base case
Engage regulators proactively on emerging issues before rules crystallise
Report foresight outputs to the board quarterly, treating them with the same rigour as financial reporting
“Don’t wait for the future to happen to you, create it.” — Frank Spencer and Yvette Montero-Salvatico, TFSX, cited in strategic foresight literature
Who Will Benefit Most from Strategic Foresight in the UK?
Businesses in supply chain-intensive, technology-dependent, and regulated sectors will benefit most from strategic foresight in the UK, particularly those with complex international exposure or fleet-dependent operations. Beazley’s survey found that 94% of global businesses plan to build resilience through insurance and risk management, indicating widespread recognition that interconnected risks amplify one another .
Manufacturers and importers facing 44% import cost increases and rules-of-origin complexity
Logistics and fleet operators managing EV transition and fuel price volatility
Financial services firms navigating AI governance and Consumer Duty obligations
Food and life sciences businesses facing novel regulatory pathways for emerging products
Any UK business with quantified exposure below board-level visibility—the 84% without quantified business interruption risk
When Must Key Business Decision Makers Act?
Key business decision makers must act now, in Q4 2026, because 2027 planning cycles are already underway and early movers will capture regulatory influence and insurance pricing advantages before systemic risks are fully priced. The ONS data shows concern about supply chain conflict rose 28 percentage points between December 2025 and April 2026—a pace that leaves late movers reacting to events rather than shaping them . Shell’s advantage in 1973 came from scenario work conducted years earlier.
Q1 2027: Integrate scenario outputs into capital allocation; review insurance programme against modelled exposures
Q2 2027: Launch weak-signal monitoring; report first foresight dashboard to board
Ongoing: Quarterly scenario refresh; annual full foresight review
Which Industries Should Be Most Concerned or Best Prepared to Take Advantage?
Manufacturing, logistics, financial services, food and life sciences, and fleet-dependent service industries should be most concerned about 2027 threats, while those same sectors are best positioned to capture advantage through early preparation. The FSA is actively developing regulatory pathways for cell-cultivated products, creating first-mover advantages for compliant innovators . The AA has already invested in specialist EV training and is progressively introducing EVs into its own fleet, converting transition risk into operational readiness.
Manufacturing: Highest exposure to supply chain conflict and import cost inflation ; opportunity in nearshoring and dual-sourcing
Logistics and transport: EV transition reshaping service profiles; opportunity in specialist EV capability
Financial services: AI governance and Consumer Duty convergence; opportunity in trusted AI assurance services
Food and life sciences: Novel regulatory pathways ; opportunity in early regulatory engagement
Insurance and risk advisory: Demand surge for quantification and scenario services ; opportunity in specialised foresight products
Energy-intensive sectors: Transition cost exposure; opportunity in efficiency-led differentiation
FAQ: Strategic Foresight 2027 and UK Business Risk
What is strategic foresight and why does it matter for UK businesses in 2027?
Strategic foresight is the capacity to explore multiple plausible futures and develop strategies that remain robust across a range of scenarios . It matters for UK businesses in 2027 because UK insolvencies are forecast to remain 21% above pre-pandemic averages even as they decline, with 24,800 failures expected in 2027 . The World Economic Forum notes that organisations with foresight capabilities “don’t just react to change, they shape it” . Shell has used scenario planning since the 1970s to anticipate geopolitical risks, including the OPEC oil embargo, and continues using it to navigate the energy transition.
Which UK sectors face the greatest insolvency risk heading into 2027?
Construction, wholesale and retail, hospitality and real estate face the greatest insolvency risk heading into 2027. Construction has accounted for around 17% of all UK insolvencies in every rolling period tracked by the Insolvency Service through mid-2026, with wholesale and retail trade consistently at 15% to 16% . Consumer-facing sectors have seen the sharpest rises in critical distress: leisure and cultural businesses rose 27.1%, hotels and accommodation 26.6%, and sport and health clubs 21.0% over the past year. Begbies Traynor Group warns that because insolvencies typically lag financial distress, the UK could see increases in business failures during 2027.
What do ONS statistics say about UK business concerns for 2027?
ONS statistics show UK business concerns about supply chain disruption have risen sharply. In late April 2026, 38% of businesses with 10 or more employees were concerned about international conflict impacting supply chains, a 28 percentage point rise from December 2025; 25% were concerned about shipping disruption, up 18 percentage points . Import costs increased for 44% of importing businesses in March 2026 compared with the previous year, the highest proportion since June 2023, while 39% of exporters reported increased costs . Additionally, 4% of businesses reported temporarily paused trading and 2% permanently ceased trading in late April 2026.
How does strategic foresight give a competitive advantage over competitors?
Strategic foresight gives a competitive advantage by enabling firms to shape regulatory environments, set industry standards, and define customer expectations before rivals recognize threats. The World Economic Forum states that leading companies using foresight are “more agile in crises, better prepared for disruption and more consistent in their long-term commitments to stakeholders” . Cisco employs technology foresight to spot emerging tech trends, guide R&D investments, and position itself in markets of the future . The alternative is illustrated by Nokia and Kodak, which failed to anticipate threats beyond their immediate industry boundaries despite having the resources to do so.
What geopolitical technology risks should UK businesses monitor for 2027?
UK businesses should monitor control over AI technology, critical minerals, and cloud infrastructure as geopolitical risks for 2027. PwC warns that technology is now widely seen as a national security issue, with the US and China using trade barriers to limit competitors’ progress across raw materials, components, knowledge and intellectual property, and data and compute infrastructure . Businesses need to map where AI models are used, which provider and jurisdiction controls them, and what dependencies and concentration risks they face . Access to critical minerals and rare earth elements is increasingly linked to geopolitical competition, affecting tech, defence, and energy transition sectors.
When must UK business leaders act to prepare for 2027 threats?
UK business leaders must act now, in Q4 2026, because 2027 planning cycles are underway and early movers capture regulatory influence and insurance pricing advantages before systemic risks are fully priced. Allianz Trade forecasts insolvencies declining to 24,800 in 2027, but this remains 21% above pre-pandemic averages, and 213,000 UK jobs are directly at risk from business insolvencies between 2026 and 2027 . Begbies Traynor warns that further increases in energy costs or inflation could accelerate financial distress, with insolvency increases likely in 2027 . The window between competitive trade credit insurance pricing and rising counterparty risk may not stay open indefinitely.
Which industries are best positioned to take advantage of 2027 opportunities?
Industries that quantify risk exposure early and engage regulators proactively are best positioned for 2027 opportunities. PwC’s UK economic outlook notes that UK corporate debt is around its lowest level this century, providing some protection, but real business investment remains below its pre-2016 trend . The IMF expects UK GDP growth of 1.3% in 2027, and the UK was the only G7 economy to receive an upgrade in the latest forecasts . Businesses that convert short-term resilience into private-sector investment and productivity gains will capture advantage, particularly in sectors where competitors remain paralyzed by uncertainty. PwC found that UK CEOs spend only 11% of their time on issues extending beyond five years.
What practical steps should decision-makers take today?
Decision-makers should appoint a foresight owner with board access, quantify their top three risk exposures, and integrate scenario planning into capital allocation. The World Economic Forum recommends structured dialogue with leadership teams to benchmark foresight capabilities against peers and identify blind spots in sensing change and translating foresight into strategy . ONS data shows 26% of businesses now use AI, up 8 percentage points year-on-year, and 18% plan to adopt it in the next three months . Businesses should map AI dependencies, review rules of origin documentation, and stress-test working capital against freight cost increases, given that 56% of concerned businesses expect sourcing costs to rise.
Get help to protect and grow your business faster with BusinessRiskTV
“BusinessRiskTV recommends embracing and harnessing uncertainty as the solution to the problem of improving business performance.” Discover how top business leaders use risk intelligence and strategic decision-making to transform market volatility into a sustainable competitive advantage in the UK and globally.
What Is Risk Intelligence in Modern Business Leadership?
Risk intelligence is the capability of an organisation to accurately gather, analyse, and evaluate qualitative and quantitative data to make informed strategic decisions in the face of uncertainty.
Definition and Core Scope: Risk intelligence is not merely defensive risk mitigation; it combines situational awareness, enterprise risk management, and market foresight to spot emerging opportunities while protecting enterprise value.
Quantifiable Value: A Department for Science, Innovation and Technology (DSIT) independent study highlighted that unmanaged systemic exposures—such as cyber disruption—cost the UK economy over £14.7 billion annually, proving that proactive intelligence delivers exceptional return on investment (ROI) and value for money.
Strategic Differentiation: High-risk-intelligent organisations evaluate risks as dynamic variables, allowing C-suite leaders to capitalise on market disruptions faster than risk-averse competitors.
Why Is Managing Uncertainty the Secret Sauce to Greater Business Success?
Managing uncertainty is the secret sauce to business success because it allows leadership teams to take calculated, proactive risks that drive sustainable margin growth while competitors freeze.
Revenue Protection and Upside Capture:Lloyds Bank Business Barometer data reveals that confident, resilient businesses are significantly more likely to report stronger trading outlooks (up to 55%) and capture growth opportunities in technology and international trade.
Cost Control and Margin Preservation: Effective risk management protects capital; failure to manage operational disruption can cost individual enterprises over £300,000 per major incident.
Capital Allocation: Financial Conduct Authority (FCA) operational resilience insights demonstrate that embedding risk frameworks directly into change management ensures capital investments deliver maximum long-term value for money.
How Can You Embrace Uncertainty to Improve Your Business Performance?
Continuous Risk Mapping: Audit people, key assets, technology, and third-party dependencies as outlined in government operational resilience guidelines.
Scenario Planning and Stress Testing:Run regular, severe-but-plausible scenario tests to measure impact tolerances before economic or supply chain shocks happen.
Agile Resource Reallocation: Shift investments dynamically toward high-performing, resilient business units based on real-time data signals rather than static annual budgets.
When Should You Incorporate Risk Intelligence Into Business Decision Making?
Incorporate risk intelligence into business decision making at every stage of corporate strategy, capital deployment, and daily operational planning.
Strategic Planning & M&A: Assess market entry, structural mergers, or new product launches against macroeconomic and regulatory risk factors.
Technology Adoption & Innovation: As ONS figures show that 30% to 51% of businesses are adopting AI and automation, risk intelligence helps evaluate governance, capability gaps, and execution risks.
Supply Chain Restructuring: Evaluate vulnerabilities whenever vendor contracts are signed, suppliers are changed, or international distribution networks expand.
Why Does Risk Intelligence Apply to UK and Overseas Businesses?
Risk intelligence applies to UK and overseas businesses because borderless supply chain disruptions, international market volatility, and global compliance mandates affect all organisations regardless of location.
Global Market Interdependence:UK businesses trading internationally report higher baseline confidence (58%) than domestic-only operators (33%), but they also face complex international tariffs, currency fluctuations, and geopolitical risks.
Regulatory Compliance Standards:Frameworks introduced by UK regulators like the FCA set international benchmarks for operational resilience, impact tolerances, and third-party risk management.
Universal Value for Money: Whether operating domestically in the UK or scaling across international boundaries, establishing a structured risk intelligence framework ensures capital efficiency, minimises downtime, and turns unavoidable market uncertainty into sustainable competitive advantage.
Get help to protect and grow your business faster through all uncertainty with BusinessRiskTV
Discover BusinessRiskTV advertising opportunities for businesses, consultants and professional service providers. Download our media kit, explore annual advertising packages and promote your expertise through business profiles, sponsored articles, LinkedIn posts, X posts, Instagram posts, Facebook posts and promotional videos.
Advertise with BusinessRiskTV. Explore our media kit, annual advertising packages, promotional opportunities and rate card for UK and international businesses.
BusinessRiskTV Media Kit & Advertising Rate Card
Advertise With BusinessRiskTV – Reach Business Decision-Makers and Professional Audiences
BusinessRiskTV helps businesses promote their expertise, products and services through specialist business media, promotional content and advertising opportunities.
Are you looking to advertise your business, reach new commercial audiences and develop valuable business relationships?
BusinessRiskTV provides UK and international companies with annual advertising opportunities through a specialist business risk management, corporate strategy and professional business media platform.
Whether you are a business consultant, technology provider, insurance company, professional services firm, recruitment agency or corporate supplier, BusinessRiskTV offers promotional opportunities to help increase your business visibility.
Why Advertise With BusinessRiskTV?
BusinessRiskTV focuses on subjects relevant to business owners, executives, corporate decision-makers, consultants and professionals.
Our specialist publishing themes include:
Enterprise Risk Management and corporate governance.
Business risk foresight and strategic planning.
Financial, economic and operational risks.
Supply chain and business continuity.
Cybersecurity, technology and artificial intelligence risks.
Business intelligence and commercial development.
Professional services and consultancy.
Business resilience, training and growth.
Our advertising proposition is to help relevant businesses promote their expertise and solutions alongside specialist business information.
Who Should Advertise?
We welcome enquiries from:
Business consultants and management advisers.
Risk management and insurance specialists.
Accountants and legal professionals.
Financial and professional service providers.
Cybersecurity and technology companies.
Business software and information providers.
Recruitment and executive search agencies.
Corporate training providers.
Business development and marketing agencies.
International B2B suppliers.
BusinessRiskTV Advertising Opportunities
We offer three annual advertising packages.
1. Business Directory Advertiser – £149 annually
An introductory advertising presence for businesses wanting to establish a profile on BusinessRiskTV.
Includes:
Business directory profile.
Company description up to 150 words.
Website link.
Contact details.
Relevant business category placement.
2. Featured Business Advertiser – £349 annually
For businesses wanting enhanced visibility and additional promotional content.
Includes everything in the Directory package, plus:
Featured business profile.
One promotional article of up to 600 words.
Two scheduled LinkedIn promotional posts.
Two scheduled X promotional posts
Two scheduled Instagram promotional posts
Two scheduled Facebook promotional posts
Two scheduled YouTube promotional posts
One annual content refresh.
3. Premium Business Partner – £799 annually
For businesses wanting broader promotional exposure and additional content opportunities.
Includes everything in the Featured package, plus:
Total of four scheduled LinkedIn promotional posts.
Total of four scheduled X promotional posts
Total of four scheduled Instagram promotional posts
Total of four scheduled Facebook promotional posts
Total of four scheduled YouTube promotional videos up to 12 seconds.
Four featured promotional placements or content updates on BusinessRiskTV
Premium positioning in a relevant category.
All packages cover 12 months and are payable upfront.
Combined Advertising Opportunities
Businesses targeting both corporate and consumer markets may also be interested in our combined BusinessRiskTV and CheeringUpInfo advertising package.
Two-Brand Premium Partner – £1,199 annually
Includes:
Premium advertising presence across both brands.
Two business profiles.
Four promotional articles.
Eight LinkedIn promotional posts in total.
Eight X promotional posts in total
Eight Instagram promotional posts in total
Eight Facebook promotional posts in total
Eight short YouTube promotional videos.
Eight featured placements or content updates.
This is particularly relevant to financial services, insurance, travel, technology and professional service businesses.
Promotional Content and Video Production
BusinessRiskTV offers opportunities to go beyond conventional directory advertising.
Depending on the package selected, promotional opportunities include:
Company introductions.
Business expertise articles.
Sponsored industry features.
Promotional LinkedIn posts.
Promotional X posts
Promotional Instagram posts
Promotional Facebook posts
Short-form promotional YouTube videos.
Featured business listings.
Industry-related advertising placements.
Advertisers can provide their own approved material or discuss suitable content production arrangements.
How Does BusinessRiskTV Help Advertisers?
Our aim is to provide businesses with an additional specialist promotional platform.
Advertising can help businesses:
Increase their online presence.
Present their expertise to relevant professional audiences.
Promote new products and services.
Support brand awareness.
Generate interest in their commercial propositions.
Develop additional marketing opportunities.
Advertising does not guarantee leads, enquiries, sales or search rankings. Performance will depend on the advertising content, audience relevance and distribution.
BusinessRiskTV Media Kit and Rate Card
Our annual advertising packages are available to UK and international businesses.
Prices are quoted in GBP and are not subject to applicable VAT.
All advertising is subject to approval, agreed deliverables and our advertising terms.
Become a BusinessRiskTV Advertising Partner
Are you looking for another way to promote your business, products, professional services or expertise?
We invite companies, consultants, professional service providers and commercial organisations to enquire about annual advertising opportunities.
Advertise with BusinessRiskTV and put your business, products and services in front of business owners, directors, senior executives and professional decision-makers. Explore annual advertising packages, sponsored content, promotional videos and business visibility opportunities through our Business Risk Management Club and specialist business network.
Business advertising to decision-makers. BusinessRiskTV: Access to business owners, directors, senior executives, risk professionals and key decision-makers. We connect businesses with valuable audiences, helping advertisers generate awareness, enquiries, customers and growth. Promote your business to decision-makers through BusinessRiskTV advertising, sponsored content, promotional videos and annual business visibility opportunities.
Advertise With BusinessRiskTV – Reach Business Owners, Directors and Decision-Makers
BusinessRiskTV helps businesses anticipate risk, make better decisions and accelerate growth. Our business-focused media and specialist communities provide opportunities for companies to showcase their expertise, promote their products and services, and build visibility among audiences interested in business strategy, risk management, finance, technology and commercial growth.
If your business sells to business owners, directors, senior executives, consultants or other professional decision-makers, discover how advertising with BusinessRiskTV could support your marketing objectives.
Reaching the right audience matters. Businesses need more than exposure; they need opportunities to communicate their value proposition to people who may influence purchasing decisions.
BusinessRiskTV focuses on business risk, strategic foresight, enterprise risk management, business intelligence, resilience and growth. These subjects are relevant to organisations seeking to protect their operations, improve performance and identify new commercial opportunities.
Our advertising opportunities are designed to help your business:
Increase visibility among relevant business audiences.
Showcase products, services and specialist expertise.
Build awareness of your brand and its commercial proposition.
Promote new services, solutions, research and resources.
Establish a consistent presence through annual advertising.
Generate enquiries and potential commercial opportunities.
Our approach combines business-focused content with promotional opportunities that can help make your brand more visible.
Who Can You Reach Through BusinessRiskTV?
BusinessRiskTV is designed for an audience interested in understanding business challenges, identifying opportunities and making better commercial decisions.
Our content themes include:
Business owners, entrepreneurs and company directors.
Corporate leadership and strategic planning.
Enterprise risk management and business resilience.
Finance, banking and investment.
Business intelligence and strategic foresight.
Cybersecurity, compliance and operational risk.
Technology, artificial intelligence and digital transformation.
Procurement, supply chains and operational management.
Business development, professional services and growth.
These subject areas create potential opportunities for advertisers whose products or services help businesses operate more effectively, manage uncertainty or improve performance.
The best advertising package will depend on your target customers, your proposition and the type of exposure you want to achieve.
What Advertising Opportunities Are Available?
BusinessRiskTV can offer a range of promotional opportunities, subject to the agreed package, available inventory and content suitability.
Annual Business Advertising
Promote your company through an agreed advertising placement for up to 12 months. Annual packages can be structured around your target audience, marketing objectives and preferred promotional formats.
Sponsored Articles and Business Features
Showcase your expertise through sponsored articles, company profiles, interviews and specialist business features. Explain a business problem, demonstrate your approach and introduce your products or services to relevant readers.
Promotional Business Videos
Use short promotional videos to introduce your business, explain what makes your services different or highlight a specific solution. Video content can provide an additional way to communicate your proposition across digital channels.
Featured Business Listings
Increase your visibility through relevant business listings and specialist categories, where available. Give prospective customers a clear explanation of what you do, whom you help and how they can contact you.
Specialist Industry and Network Promotion
Explore promotional opportunities across relevant BusinessRiskTV communities, magazines, forums and professional resources, subject to availability and suitability.
Thought Leadership and Expert Positioning
Share useful insights, research, commentary and professional expertise that demonstrate your knowledge of a particular business challenge. Educational content can help prospective customers understand your expertise before contacting you.
Why Choose Annual Advertising?
A single advertisement may create awareness, but a longer-term presence gives your business more opportunities to communicate its proposition over time.
Annual advertising can help you maintain visibility while promoting new services, sharing fresh content and supporting ongoing business development.
Depending on the package selected, your campaign could include a combination of advertising placements, sponsored content, promotional videos and featured listings.
We recommend agreeing clear objectives before your campaign starts. These might include increasing relevant website visits, generating enquiries, promoting a new service or building brand recognition within a particular sector.
Advertising performance depends on factors such as audience relevance, the strength of your offer, creative quality, placement and campaign measurement. We do not guarantee leads or sales.
Which Businesses Should Advertise With BusinessRiskTV?
BusinessRiskTV may be particularly relevant to companies selling products or services to other businesses, including:
Risk management and business continuity consultancies.
Accountancy, legal and professional services firms.
Business finance and insurance providers.
Cybersecurity, compliance and technology companies.
Business software and artificial intelligence providers.
Recruitment, executive training and leadership development firms.
Procurement and supply chain specialists.
Corporate service providers and B2B suppliers.
Business intelligence and strategic advisory firms.
Companies seeking greater visibility among professional audiences.
Whether you are an established business or a growing specialist provider, the starting point is to identify the customers you want to reach and determine whether our advertising opportunities are suitable.
How to Advertise With BusinessRiskTV
Getting started is straightforward.
Step 1: Tell us about your business. Explain what you sell, whom you serve and what makes your offering valuable.
Step 2: Identify your target audience. Tell us the industries, professional roles or types of businesses you want to reach.
Step 3: Discuss your objectives. You may want to build brand awareness, promote a product, generate enquiries or establish your expertise.
Step 4: Choose a suitable package. We will discuss available placements, promotional formats, duration and pricing.
Step 5: Agree your campaign. Confirm the deliverables, publication schedule, creative requirements and reporting arrangements before the campaign begins.
Ready to Reach Business Decision-Makers?
Your next customers could be looking for the expertise, products or services your business provides.
BusinessRiskTV offers an opportunity to put your brand alongside content focused on business challenges, strategic decisions, risk and growth.
Risk less. Grow more. Explore advertising with BusinessRiskTV.
Enquire About Annual Advertising
Email: editor@businessrisktv.com
Tell us about your business, your target customers and the results you want your advertising to support.
BusinessRiskTV Advertising Packages and Annual Pricing
Choose the Right Advertising Package for Your Business
BusinessRiskTV offers three levels of annual advertising designed to help businesses increase visibility, showcase their expertise and promote their products and services to relevant business audiences.
Whether you are looking to introduce your company, establish a stronger market presence or develop a more extensive promotional campaign, we can discuss an advertising package aligned with your objectives.
All packages are based on an annual advertising agreement, with promotional placements and deliverables agreed in advance.
1. STARTER – Establish Your Business Presence
An introduction to advertising with BusinessRiskTV.
Ideal for smaller businesses, specialist service providers, consultants and companies looking to establish a presence within a business-focused media environment.
Potential package features:
Annual business advertiser listing.
Company profile and description.
Business website and contact links.
Relevant business category placement.
Promotional information about your products or services.
Opportunities to introduce your business through selected BusinessRiskTV content.
Annual advertiser presence, subject to the agreed listing and publication schedule.
Best suited to: Businesses wanting to establish visibility and introduce their services to a relevant professional audience.
More opportunities to showcase your expertise and promote your business.
Designed for companies seeking a broader promotional presence through a combination of business advertising and content.
Potential package features include:
Everything included in Starter.
Enhanced business profile and promotional positioning.
Sponsored article or business feature, subject to editorial and advertising approval.
Promotional video opportunity.
Additional promotional placements across relevant BusinessRiskTV channels.
Featured product or service promotion.
Campaign tracking recommendations.
Agreed promotional schedule throughout the annual advertising period.
Best suited to: Businesses wanting to build brand awareness, explain their services and create more opportunities for prospective customers to discover them.
3. PREMIUM – Maximise Your Business Promotion Opportunities
A broader annual promotional programme for ambitious businesses.
Designed for businesses seeking a more extensive presence, multiple promotional formats and additional opportunities to position their brand within relevant business content and communities.
Potential package features include:
Everything included in Growth.
Enhanced featured advertiser positioning.
Additional sponsored articles or expert features.
Additional promotional video opportunities.
Greater promotional exposure across selected relevant channels.
Additional product, service or campaign features.
Opportunities for expert interviews and thought leadership content.
Agreed promotional calendar.
Campaign performance review and recommendations.
Priority consideration for suitable promotional opportunities, subject to availability.
Best suited to: Established businesses, professional service providers, technology companies and B2B suppliers looking for a broader annual marketing presence.
BusinessRiskTV annual advertising prices depend on the package selected, promotional formats, content production requirements, number of placements and agreed campaign duration.
Rather than offering a one-size-fits-all price, we discuss your marketing objectives and prepare a proposal based on the promotional opportunities that best suit your business.
Our three annual advertising levels provide a starting point:
Starter – establish your presence.
Growth – increase your visibility.
Premium – develop a broader promotional programme.
Request an annual advertising quotation.
Tell us about your company, your target customers and what you want to achieve. We will discuss suitable options and provide a written quotation outlining the proposed deliverables and annual price.
All advertising placements, content production, publication dates and promotional deliverables must be confirmed in writing before purchase. Additional production or promotional services may be quoted separately.
What Happens After You Enquire?
Tell us about your business and products or services.
Identify the business audience you want to reach.
Select your preferred advertising package.
Discuss the available promotional opportunities.
Receive a written annual advertising proposal.
Agree the package, payment terms and promotional schedule.
Supply your approved promotional materials and begin your campaign.
Can better business risk management help your company grow? Discover how strategic foresight, risk intelligence and holistic enterprise risk management help business leaders anticipate threats, make better decisions and identify new commercial opportunities.
Discover how business risk management, strategic foresight and enterprise risk management help businesses anticipate threats, improve resilience and identify growth opportunities.
Risk Less, Grow More: How Better Business Risk Management Creates Growth Opportunities
BusinessRiskTV – Helping Businesses Anticipate Risk, Make Better Decisions and Accelerate Growth.
What if better business risk management could do more than protect your company from failure? What if it could help you identify new opportunities, make better strategic decisions and grow faster than competitors who only react when problems arise?
Many businesses treat risk management as a defensive activity: something required for compliance, insurance, financial reporting or regulatory purposes. But effective business risk management should be much more than that.
It should help business leaders anticipate uncertainty, challenge assumptions, identify emerging threats and recognise opportunities before they become obvious to everyone else.
From financial pressures and operational disruption to cybersecurity, artificial intelligence, supply chain vulnerability and changing market conditions, businesses face an increasingly complex risk environment.
The organisations best positioned to succeed are those that understand the relationship between risk, opportunity, strategy and growth.
BusinessRiskTV believes that better risk intelligence, strategic foresight and holistic enterprise risk management can help businesses become more resilient, make smarter decisions and accelerate sustainable growth.
Why Is Business Risk Management Essential for Growth?
Business risk management is essential for growth because it helps organisations understand what could prevent them from achieving their objectives, allocate resources more effectively and make better-informed commercial decisions.
Growth creates opportunities, but it also introduces new risks.
Expanding into new markets, employing additional staff, launching products, taking on debt, investing in technology or entering new supplier relationships can all increase a company’s exposure to uncertainty.
Without an effective approach to identifying and managing these risks, businesses can find themselves growing faster than their ability to manage the consequences.
Consider some common examples:
Financial risk: Rising borrowing costs, cash flow pressures, customer defaults and excessive debt can undermine expansion plans.
Operational risk: Poor processes, inadequate controls, equipment failures and insufficient capacity can disrupt delivery.
Strategic risk: Competitors, changing customer behaviour and poor investment decisions can undermine long-term objectives.
Cybersecurity risk: Data breaches, ransomware and technology vulnerabilities can damage operations and customer confidence.
Supply chain risk: Dependence on individual suppliers, transport networks or critical infrastructure can create unexpected disruption.
People risk: Skills shortages, leadership failures and employee retention problems can restrict business performance.
Regulatory risk: Changes in legislation, compliance requirements and industry standards can create additional costs and obligations.
The important point is that risks are interconnected.
A financial problem can become an operational problem. An operational failure can damage customer relationships. A cyberattack can create financial, legal and reputational consequences.
Business leaders therefore need to look beyond individual risk registers and understand how different risks interact.
Risk management should support business objectives
An effective risk management strategy starts with understanding what the organisation wants to achieve.
For example:
If the objective is faster growth, identify the financial, operational and market risks associated with expansion.
If the objective is increased profitability, examine pricing, costs, productivity and customer concentration.
If the objective is international expansion, consider political, currency, regulatory and supply chain exposure.
If the objective is digital transformation, assess technology, cybersecurity, data and implementation risks.
This makes risk management relevant to everyday commercial decisions rather than simply an administrative exercise.
The difference between avoiding risk and managing risk
Taking no risks can be just as damaging as taking excessive risks. Organisations that refuse to innovate, invest or adapt may gradually lose their competitive position.
The objective should be to understand which risks are worth taking, which require mitigation and which should be avoided.
The best businesses do not necessarily take fewer risks. They make better-informed decisions about the risks they take.
How Can Businesses Identify Risks Before They Become Problems?
Businesses can identify risks before they become problems by combining systematic risk assessments, financial and operational monitoring, employee insight, external intelligence and forward-looking scenario analysis.
Waiting until a problem becomes visible is often too late.
A supplier failure, loss of a major customer, sudden increase in borrowing costs or technology disruption may have been developing for months before its full consequences become apparent.
The challenge is to identify warning signals early enough to take action.
1. Understand the business environment
Start by examining the internal and external factors that could influence business objectives.
Internal considerations include:
Cash flow and financial performance.
Operational capacity and processes.
Employee skills and management capability.
Technology and information security.
Customer concentration and supplier dependencies.
Business continuity arrangements.
External considerations include:
Economic conditions and interest rates.
Competitor behaviour.
Changing customer expectations.
Government policy and regulation.
Geopolitical developments.
Technology and artificial intelligence.
Climate, energy and infrastructure disruption.
A business cannot control every external development, but it can improve its understanding of potential consequences.
2. Identify early warning indicators
Risk identification becomes more effective when organisations monitor indicators that suggest a threat may be developing.
Examples include:
Deteriorating cash flow and increasing debtor days.
Falling customer retention.
Increasing supplier delivery delays.
Higher employee turnover.
Rising insurance premiums.
Increasing cyber incidents.
Declining product margins.
Growing customer complaints.
Greater dependence on a small number of customers or suppliers.
These indicators can provide management with opportunities to investigate problems before they become serious.
3. Encourage employees to identify risks
People working within an organisation often recognise emerging problems before senior management becomes aware of them.
Employees may identify inefficient processes, unrealistic targets, equipment weaknesses, customer dissatisfaction or unsafe working practices.
Businesses should create an environment where employees can raise concerns without fear of blame.
Risk management should not belong exclusively to the risk department or senior management team.
4. Challenge existing assumptions
One of the biggest weaknesses in business risk management is assuming that yesterday’s conditions will continue tomorrow.
Ask questions such as:
What happens if our biggest customer leaves?
What if our main supplier cannot deliver?
What if borrowing costs increase?
What if our key technology becomes unavailable?
What if a competitor introduces a significantly better product?
What if our current business model becomes less profitable?
These questions encourage management teams to think beyond routine forecasts.
5. Use scenario planning
Scenario planning allows businesses to explore how different future developments could affect their objectives.
For example, a business might examine:
A favourable economic recovery.
A prolonged period of weak consumer demand.
A major supply chain disruption.
A significant cybersecurity incident.
Rapid adoption of disruptive technology.
The purpose is not to predict the future with certainty.
It is to understand possible outcomes, test preparedness and identify actions that could improve the organisation’s position.
Early risk identification gives businesses more time, more choices and greater control over their response.
Can Strategic Foresight Create a Competitive Advantage?
Yes. Strategic foresight can create a competitive advantage by helping businesses recognise emerging developments, anticipate potential changes and prepare for opportunities before competitors respond.
Traditional business planning often concentrates on forecasts, budgets and expected market conditions.
Strategic foresight goes further.
It examines how the business environment might change and what those changes could mean for the organisation.
This is particularly important in an environment influenced by artificial intelligence, technological disruption, economic uncertainty, geopolitical developments and changing customer expectations.
What is strategic foresight?
Strategic foresight is the structured exploration of possible future developments to help organisations make better decisions today.
It does not claim to predict exactly what will happen.
Instead, it encourages business leaders to consider multiple possible futures, challenge assumptions and prepare for developments that could affect their strategy.
Five ways strategic foresight can improve business performance
1. Identify emerging markets
Changes in technology, consumer behaviour and regulation can create new commercial opportunities.
Businesses that identify these developments early may be better positioned to develop products, services and partnerships.
2. Recognise competitive threats
A new competitor, disruptive technology or changing customer preference can challenge an established business model.
Strategic foresight helps organisations examine these threats before their commercial impact becomes significant.
3. Improve investment decisions
Major investments should consider more than immediate financial returns.
Businesses should examine how future market conditions, technology developments and regulatory changes could affect the investment over time.
4. Prepare for economic uncertainty
Businesses can test their strategies against different economic scenarios, including higher interest rates, inflation, weak demand and restricted access to finance.
5. Develop organisational adaptability
Companies that regularly challenge their assumptions and review emerging developments can become more adaptable when circumstances change.
Why businesses should look beyond traditional forecasting
Forecasting usually extrapolates expected developments from available data and assumptions.
This is useful, but it can become unreliable when conditions change significantly.
Strategic foresight encourages management teams to ask:
What could change our industry?
Which assumptions might become invalid?
What opportunities are competitors overlooking?
What developments could threaten our business model?
What should we start doing today to prepare for tomorrow?
The organisations that ask better questions may be better prepared to recognise opportunities.
Strategic foresight turns uncertainty into something businesses can investigate, prepare for and potentially benefit from.
How Does Enterprise Risk Management Improve Business Resilience?
Enterprise risk management (ERM) improves business resilience by providing an organisation-wide approach to understanding, assessing and managing risks that could affect its strategic objectives and operational performance.
Traditional risk management can become fragmented.
Finance manages financial risks, IT manages technology risks, operations manages operational risks and compliance manages regulatory risks.
Each department may be performing its responsibilities correctly, yet the organisation can still overlook the relationships between different risks.
This is where holistic enterprise risk management becomes important.
What is holistic enterprise risk management?
Holistic ERM considers the organisation as a connected system rather than a collection of separate departments and individual risk registers.
It encourages management to understand how risks interact and how decisions in one area can affect the wider business.
For example, reducing operational costs might appear financially beneficial.
However, if the decision results in inadequate maintenance, insufficient staffing or reduced quality control, it could increase operational, customer, reputational and financial exposure.
A holistic approach examines the wider consequences before decisions are made.
Five ways ERM can strengthen business resilience
1. Better visibility of organisational risks
ERM helps management understand the major risks affecting the entire organisation rather than relying solely on departmental reporting.
2. Improved resource allocation
Management can prioritise resources towards the risks that matter most to strategic objectives.
3. Stronger business continuity
Understanding critical processes, dependencies and vulnerabilities helps organisations prepare for disruption and improve recovery arrangements.
4. Better governance and accountability
Clear responsibilities help ensure that risks are identified, escalated, monitored and addressed.
5. More informed strategic decisions
Risk information becomes part of investment, expansion, acquisition and operational decisions.
Move from piecemeal risk management to holistic ERM
A piecemeal approach can leave significant gaps between departments.
A holistic ERM approach connects financial, strategic, operational, technological, people and external risks.
The objective is to create a shared understanding of risk across the organisation.
This requires leadership commitment, appropriate governance, reliable information and an organisational culture where people understand their role in managing risk.
Businesses can use established frameworks such as ISO 31000 and the COSO Enterprise Risk Management framework to inform their approach.
However, adopting a framework is not the same as achieving effective enterprise risk management.
The real test is whether risk information improves decisions and helps the organisation achieve its objectives.
Resilience is not simply the ability to survive disruption. It is the ability to anticipate, adapt, respond and continue creating value when circumstances change.
How Can Business Leaders Turn Risk Intelligence Into Growth?
Business leaders can turn risk intelligence into growth by using information about threats, opportunities and changing conditions to improve investment decisions, identify new markets, strengthen operations and develop more effective strategies.
Risk intelligence should not end with a report or a risk register.
It should influence what the organisation does next.
The commercial value comes from translating information into decisions and decisions into action.
1. Identify opportunities hidden within risks
A developing risk can sometimes reveal an opportunity.
For example:
Supply chain disruption can create opportunities for alternative suppliers and local sourcing.
Cybersecurity threats can increase demand for specialist security services.
New regulation can create opportunities for businesses offering compliance solutions.
Changing customer expectations can create demand for new products.
Technology disruption can allow businesses to improve productivity and develop new business models.
The key is to examine both the downside and the potential upside of changing conditions.
2. Invest in the right opportunities
Risk intelligence can help management assess whether an investment is appropriate.
Before committing resources, examine:
Expected commercial returns.
Financial exposure.
Operational capability.
Market demand.
Competitor activity.
Technology requirements.
Regulatory considerations.
Potential alternative outcomes.
This can help organisations distinguish between attractive opportunities and investments carrying unacceptable exposure.
3. Improve strategic decision-making
Business leaders should bring risk information into regular management discussions.
Instead of asking only whether a project will achieve its financial targets, ask what could prevent success, what assumptions underpin the forecast and what changes would require management intervention.
This encourages better-informed decisions and earlier action.
4. Make risk ownership part of business culture
Risk management should not be treated as the responsibility of one individual or department.
Directors, managers and employees all have roles to play in identifying and addressing risks within their areas of responsibility.
A positive risk culture encourages people to challenge assumptions, raise concerns and communicate emerging developments.
5. Measure whether risk management creates value
Businesses should examine whether their risk management activities are improving organisational performance.
Useful indicators might include:
Reduced frequency or severity of operational disruptions.
Improved business continuity performance.
Better cash flow visibility.
Reduced customer and supplier concentration.
Faster identification of emerging threats.
Improved investment decisions.
Better achievement of strategic objectives.
The measures should reflect the organisation’s actual priorities rather than simply counting the number of risks recorded.
Risk intelligence should create commercial value
The purpose of risk intelligence is not to make business leaders more cautious about everything.
It is to help them understand uncertainty, make informed choices and recognise opportunities that might otherwise be overlooked.
Businesses that combine commercial ambition with strong risk intelligence can be better equipped to pursue sustainable growth.
Risk management is not just about protecting what you have. It is also about improving your ability to achieve what you want.
Risk Less. Grow More. Make Better Business Decisions With BusinessRiskTV.
BusinessRiskTV exists to help businesses understand risk, anticipate change, improve decision-making and identify opportunities for growth.
We believe that business risk management should be an integral part of strategy, not an isolated compliance exercise.
Whether you are a business owner, company director, consultant, risk professional or senior decision-maker, understanding the relationship between risk and opportunity can help you make better commercial decisions.
Explore BusinessRiskTV’s business-focused resources and communities:
Business Risk Management Club: Connect with resources and insights focused on improving business risk management.
Business Risk Academy: Explore professional development, risk management knowledge and practical learning.
Global Business Risk Network: Discover opportunities to engage with the wider business risk community.
Enterprise Risk Management Magazine: Explore ideas and developments in holistic enterprise risk management.
Risk Management Jobs Board: Discover specialist career and recruitment opportunities.
BusinessRiskTV: Follow business risk intelligence, strategic foresight and commercial developments.
Want to Improve Your Business Risk Intelligence?
Don’t wait until a developing threat becomes an expensive business problem.
Start identifying risks earlier, challenging assumptions and making better-informed decisions.
Too many changing risks, too little budget? Join BusinessRiskTV’s UK Business Risk Club — peer risk support for UK decision makers facing 2027 uncertainty.
BusinessRiskTV recommends this club for UK key decision makers as the solution to the problem of too many rapidly changing risk problems with too little risk control budget. The UK Business Risk Club exists because the old way of managing risk—waiting for the annual review, buying another dashboard, hoping the storm passes—is failing under the weight of compounding crises. Alan Watts wrote that “the more we crave security, the greater our insecurity becomes.” The tighter you grip the need to know exactly how everything will turn out, the more anxious you become. The looser you hold it, the more spacious your life feels. This club is built on that principle: uncertainty is not a problem to be solved—it is the condition of being alive or in business.
Why Is a UK-Focused Club Better Than the Global Alternatives?
A UK-focused club is better than global alternatives because the risks hitting UK decision makers in 2026 and 2027 are distinctly local in their policy triggers, regulatory texture, and supply-chain exposure. The online competition is crowded with American-dominated risk forums, generic LinkedIn groups, and expensive consultancy portals. They offer frameworks built for a different legal system, a different fiscal calendar, and a different political rhythm. They do not wake up to a UK Budget that threatens a wealth tax on property, or a Bank of England warning that firms are “squeezing margins” while energy bills surge . They do not track the insolvency rate in Northern Ireland climbing to 42.3 per 10,000 companies , or the 65 profit warnings issued by UK-listed firms in a single quarter, with more than half blaming government policy and geopolitical uncertainty . The UK Business Risk Club fills that gap. It is not another feed of global noise. It is a room of people who understand that “high-cost island” is not a metaphor but a line item on their P&L .
Who Benefits, When, and Where?
Key UK decision makers responsible for business risk benefit, starting immediately, wherever they are online, because the club delivers peer intelligence in the moments between crises rather than after them. The beneficiary is not the risk department alone. It is the finance director who sees the employer National Insurance raid eating the hiring budget. It is the operations lead watching shipping disruption concerns rise 18 percentage points since December 2025 . It is the managing director in housebuilding, a sector that has issued 14 profit warnings so far this year—more than the peak of the 2008 financial crisis . They benefit when they stop treating uncertainty as a personal failing and start treating it as a shared condition. They benefit where they already are: at the desk, on the train, in the fifteen minutes before a board call. The club does not ask them to travel to London or buy a six-figure retainer. It asks them to be around each other.
What Does The Fourth Turning Reveal About the Risks We Face Now?
The Fourth Turning reveals that the dangers of 2026 and 2027 are not anomalies but the predictable climax of a crisis cycle that Strauss and Howe mapped decades ago. Neil Howe’s framework describes a roughly 80-year cycle moving through four turnings, with the Fourth Turning being the period of civic upheaval and national mobilization—the season when institutions are openly discarded and the old assumptions simply cannot hold . The authors suggested the crisis catalyst would arrive around 2005, with the climax due around 2020 and resolution around 2026 . Howe’s later work extended the window, warning that the polarisation, civil conflict risk, and global war threats now visible will culminate by the early 2030s . Look at the evidence sitting beside that framework. In October 2026, up to 500,000 people protested across France, with the town hall in Limoges burned, 2,000 arrests, and over 600 police officers injured . Protests spread to the UK, Italy, Spain, Portugal, Belgium, and Poland. Eurozone energy prices rose 18.8% year-on-year, pushing inflation to 3.8% . In February 2026, US and Israeli strikes on Iran ignited a multi-front war that directly impacted at least a dozen countries . The UK’s own Business Insights survey found 38% of businesses with 10 or more employees concerned about international conflict impacting supply chains—a 28 percentage point rise from December 2025 . These are not separate stories. They are the texture of a Fourth Turning. “You do not need to know how the story ends to enjoy the chapter you are in.” But you do need to know which chapter you are in.
What Are the Real Benefits, Not Features, of Membership?
The real benefit of membership is a measurable improvement in your capacity to make decisions under uncertainty without waiting for perfect information. You stop being the person who reacts late. You become the person who has already heard the whisper before it becomes a headline. The benefit is not a “resource library” or a “monthly newsletter.” It is the quiet confidence of sitting in a room—even a virtual one—where someone else has already navigated the supplier collapse, the riot-related distribution delay, the sudden tax change, and can tell you what they wish they had done differently. The benefit is budget leverage: you get the collective intelligence of dozens of UK risk owners for a fraction of what one consultancy day costs. The benefit is personal performance: you sleep better because you are holding uncertainty more loosely, as Watts suggested, and you perform better because you are not frozen. The benefit is organisational performance: your business grows because you protect the downside while your competitors are still arguing about whether the downside is real.
What Should UK Decision Makers Be Worried About at the End of 2026 and Into 2027?
UK decision makers should be worried about nine specific risks at the end of 2026 and into 2027, each of which is already visible in official data and on-the-ground events.
Policy-driven cost shocks from the UK Budget. Profit warnings linked to policy change have become “a regular feature” of EY’s data, and the Chancellor’s fiscal headroom has shrunk from £23.6bn to £11.3bn, increasing the likelihood of tax raids on business.
Energy price contagion from the Iran conflict. The Bank of England has warned that firms are squeezing margins and cost-cutting because they cannot pass surging energy bills to customers, and the longer high prices persist, the more likely firms will be forced to raise prices and lose volume.
Supply chain fracture from international conflict. 38% of UK businesses with 10 or more employees are already concerned about conflict impacting supply chains, and 44% of importing businesses reported rising import costs.
Civil unrest spillover from European protests. The October 2026 riots in France, Italy, Belgium, and Portugal demonstrate how quickly cost-of-living anger escalates into property destruction and transport disruption, with direct implications for UK firms with European operations or distribution.
Insolvency contagion in the SME supply base. One in 200 UK companies entered insolvency in the year to September 2026, and individual insolvencies in March 2026 were 30% higher than the previous year, with Debt Relief Orders at a record high.
Housebuilding and construction fragility. The sector has issued 14 profit warnings this year, exceeding the 2008 financial crisis peak, and any new property or wealth tax would make the UK the worst place in the OECD to own property or assets.
Labour and employment cost escalation. The employer National Insurance raid and minimum wage rises have turned the UK into a “high-cost island,” with 57% of small businesses believing the government is not on their side.
Geopolitical escalation beyond the Middle East. CrisisWatch identified thirteen conflict deteriorations in February 2026 alone, including Pakistan-Afghanistan hostilities and Ethiopia-Eritrea tensions, any of which could disrupt UK trade routes and commodity prices.
The psychological trap of grasping for certainty. The greatest risk is the one Watts named: the tighter you grip the need to know exactly how everything turns out, the more anxious and paralysed you become. The Fourth Turning does not offer a forecast. It offers a condition. The businesses that survive are the ones that learn to move within the condition rather than wait for it to clear.
UK decision makers should take five steps today to protect and grow their business through these risk events, starting with joining a peer group that keeps them ahead of the curve rather than behind it.
Join the BusinessRiskTV UK Business Risk Club and show up consistently. The step is not to lurk. The step is to bring one live risk problem to the room in your first week and let others help you stress-test it. You will leave with at least one action you had not considered.
Map your exposure to the three contagions: energy, policy, and supply chain. Take your top three suppliers and your top three cost lines. Ask what happens if each rises 20% in the next six months. Ask what happens if one disappears. Do this with the club, not alone.
Stress-test your cash conversion cycle against a 90-day disruption. If a riot blocked your distribution route, if a supplier entered administration, if a tax change hit your sector, how many weeks of cash do you have? The answer is your real risk budget.
Build a “beginner’s mind” protocol for your leadership team. Let yourself not have all the answers. Let yourself be in process. Run a monthly 30-minute session where the only rule is that no one is allowed to pretend certainty they do not feel. The team that can say “I don’t know” faster is the team that adapts faster.
Measure your performance by decision speed, not prediction accuracy. The Fourth Turning does not reward the best forecasters. It rewards the people who can act with incomplete information and correct course without shame. Track how long it takes your organisation to move from signal to decision. Cut that time in half. That is growth.
The conclusion is not that the world is ending. The conclusion is that the world is in a season where the old grip does not hold. “Let yourself be a beginner. Let yourself not have all the answers. Let yourself be in process.” The UK Online Club is not a shelter from uncertainty. It is a place to practise holding it more loosely, together, so you can perform when it matters.
Your risk register is a work of fiction. And your board knows it.
Here’s the number that should worry you: 65 profit warnings from UK-listed companies in a single quarter — and more than half blamed government policy and geopolitical uncertainty, not their own execution. That’s not a market problem. That’s a “we planned for the wrong decade” problem.
Meanwhile, one in 200 UK companies entered insolvency in the year to September 2026. Housebuilding has issued 14 profit warnings this year — more than the peak of the 2008 financial crisis. And 38% of UK businesses with 10+ employees are now worried about international conflict hitting their supply chains, up 28 percentage points since December 2025.
Individually, those are headlines. Together, they are a pattern — and Neil Howe’s The Fourth Turning says the pattern is not random. We are in the crisis season. The institutions are being stress-tested. The old grip does not hold.
Alan Watts nailed the trap: “The more we crave security, the greater our insecurity becomes.”
So here’s the uncomfortable question. If you can’t predict 2027 — and you can’t — what are you actually doing to prepare for it? Because your competitors aren’t waiting for certainty either.
Uncertainty is not a sign you’re doing something wrong. It’s a sign you’re paying attention.
That’s why BusinessRiskTV recommends the UK Business Risk Club: the solution to too many rapidly changing risk problems with too little risk control budget. Not a dashboard. Not a six-figure retainer. A room of UK decision makers who’ve already navigated the supplier collapse, the riot-delayed distribution, the Budget tax raid — and will tell you what they wish they’d done first.
Who benefits: finance directors, ops leads, MDs, risk owners.
When: before your next board call.
Where: online, wherever you already are.
You don’t need to know how the story ends to enjoy the chapter you’re in. But you do need to know which chapter you’re in.
Email editor@businessrisktv.com with the subject line “UK BUSINESS RISK CLUB” and we’ll send you the joining details.
Drop a 🔥 in the comments if your risk register needs a rewrite this quarter.
Reading materials for your first month in the club
Use “The Fourth Turning” to understand the 2027 crisis, emphasising peer support is critical for members to invest in, and coping with uncertainty—here are the UK Amazon products best suited for recommendation in 2027. Note that several products are marked as “Kindle Edition,” which facilitates immediate purchase and learning by UK readers.
Core Recommendation: Books Directly Related to the ThemeS
The Fourth Turning (Kindle Edition)
• Why it fits: This is the theoretical cornerstone of this article. Strauss and Howe’s book explains the cyclical nature of history and is the source of the argument about currently “being in the crisis season”. It helps readers understand from the root why 2027 is full of uncertainty, rather than just reacting to headlines.
• UK Availability: Available on Amazon UK, Kindle edition priced at approximately £7.49, with immediate reading upon purchase.
Crisis Engineering: Time-Tested Tools for Turning Chaos into Clarity (Kindle Edition)
• Why it fits: Highly aligned with “practical action” call. The authors come from the Layer Aleph crisis engineering firm, with experience in high-pressure scenarios such as HealthCare.gov rescue and pandemic logistics. It teaches you what to do when “the system has collapsed and your team is waiting for you to give orders,” which directly addresses the situation where UK decision-makers “have too many risks and too little budget.”
• UK Availability: Published April 2026, Kindle edition available on Amazon UK.
Blindspots: How to See Risk Before It Strikes, Protect Your Venture and Unlock Growth (Kindle Edition)
• Why it fits: Specifically addresses “hidden risks” that UK SME and founder-level readers care about. The author is a former White & Case finance lawyer who understands contractual and governance risks that are hard to see with the naked eye. The book mentions that 55.6% of venture capital-backed CEOs are replaced by year four due to unforeseen contractual mechanisms—this data point itself can serve as a discussion hook in your post.
• UK Availability: Published February 2026, Kindle edition available on Amazon UK. Author lives in London.
Business Continuity Management: A Practical Guide to Organization Resilience and ISO 22301 (Paperback)
• Why it fits: For members from larger organisations (with compliance/continuity responsibilities), this is the most “UK-grounded” choice. Author James Crask is a Commissioner at the UK National Preparedness Commission, formerly responsible for risk at the BBC and UK Nuclear Decommissioning Authority, and is now at Marsh leading global supply chain practice. The book directly addresses geopolitical risk, supply chain disruption, and how to make decisions in “endless data”.
• UK Availability: Published May 2024, paperback available on Amazon UK. Author is based in London.
Becoming Good at Crises: A Field Guide for Leaders (Kindle Edition)
• Why it fits: Echoes Alan Watts’s “the tighter you grip, the greater your insecurity.” This book is not about prediction, but about “how to become good at crises.” With only 166 pages, it’s lightweight, and the author has real experience in UK public sector and social leadership scenarios. UK readers have commented that it “feels very much ‘of the moment’ for these crazy times”.
• UK Availability: Published March 2025, Kindle edition available on Amazon UK.
Understanding the Future: An Introduction to Scenario Planning (Paperback)
• Why it fits: If you are strategist or planner, this book provides specific tools for “operating within uncertainty”—scenario planning’s Intuitive Logics model. It doesn’t teach you to predict the future; it teaches you to make better decisions across multiple possible futures.
• UK Availability: Published January 2025, available on Amazon UK. Author is from Strathclyde Business School, with a UK perspective.
How do directors, project managers & strategists navigate systemic uncertainty? BusinessRiskTV reviews Taleb’s 3 books with UK ONS stats & practical tail risk steps.
BusinessRiskTV Business Risk Management Club recommends these 3 books to help the reader make better decisions on Operational Resilience & Tail Risk Strategy.
That single sentence encapsulates why the following review exists. The scale of the problem is not theoretical. The Office for National Statistics reported that 40% of UK trading businesses with 10 or more employees cited economic uncertainty as the most significant challenge impacting turnover in early April 2026—the highest proportion since the question was introduced in April 2022. Government analysis of operational disruption across UK sectors shows that while typical incidents cost between 0.2% and 4.6% of annual turnover, tail events can dominate total losses and threaten business continuity entirely. Cyber-attacks alone cost UK businesses £3.7 billion in litigation over the past year, with shareholder lawsuits accounting for nearly a third of that total. Against this backdrop, Nassim Nicholas Taleb’s Incerto trilogy—Fooled by Randomness, The Black Swan, and Antifragile—provides the conceptual infrastructure that directors, project managers, and strategists need to navigate systemic uncertainties and cognitive bias in decision-making.
What Makes Nassim Nicholas Taleb’s Incerto Trilogy Essential Risk & Decision-Making Literature for Operational Resilience & Tail Risk Strategy?
Taleb’s Incerto trilogy is essential risk and decision-making literature for operational resilience and tail risk strategy because it systematically dismantles the illusions that lead organisations to underestimate rare, high-impact events and overestimate their ability to predict and control complex systems. The three books form a coherent progression: Fooled by Randomness (2001) exposes how humans mistake luck for skill; The Black Swan (2007) reveals how rare, unpredictable events shape history and markets; Antifragile (2012) offers a framework for building systems that benefit from disorder.
Why This Matters for Directors, Project Managers & Strategists:
Directors face board-level decisions where governance failures linked to cognitive bias carry escalating legal and financial consequences. UK boards are already experiencing “quiet distress” as prolonged financial strain and delayed decisions create D&O exposure earlier in the risk cycle.
Project managers operate at the intersection of uncertainty and delivery, often relying on linear projections and optimistic timelines that fail catastrophically when tail events hit. Research shows that organisations with structured decision trackers score more than 20 percentage points higher on early-warning indicator tracking and bias exploration than those without.
Strategists build models that assume a stable future, yet the ONS Business Insights survey consistently shows economic uncertainty dominating business challenges month after month.
Each book serves a distinct function in the operational resilience toolkit. Together, they constitute a complete curriculum in probabilistic thinking, tail risk awareness, and adaptive system design.
What Is the Core Argument of Fooled by Randomness, and How Does It Apply to Business Decision-Making?
The core argument of Fooled by Randomness: The Hidden Role of Chance in Life and in the Markets is that humans systematically confuse randomness with causality, attributing success to skill and failure to controllable factors, thereby creating brittle decision-making frameworks that collapse when randomness reasserts itself. Taleb demonstrates that much of what passes for expertise in finance, management, and strategy is indistinguishable from luck dressed in the language of analysis.
Why This Matters Practically:
Distinguish signal from noise in performance data. Taleb argues that short-term results are dominated by variance, not skill. When evaluating business unit performance or project outcomes, directors should demand longer time horizons and statistical significance testing before drawing conclusions. UK businesses reporting turnover decreases (27% in April 2026) and increases (15% in July) often attribute these swings to strategy or market conditions when random fluctuation may be the dominant driver.
Identify survivorship bias in case studies. Business literature is filled with success stories of companies that “did everything right.” Taleb’s point is that we never see the graveyard of companies that did the same things and failed due to bad luck. Strategy teams should actively seek out failure cases and control groups.
Resist the narrative fallacy in post-mortems. After any project, there is enormous pressure to construct a coherent story explaining outcomes. Taleb warns this narrative impulse prevents genuine learning.
Business Application:
Project managers should implement decision journals that record expectations before outcomes are known, creating a feedback loop that reveals whether success was skill or circumstance. Directors should push for probabilistic language in board papers—”we assess a 60% likelihood” rather than “we are confident”—forcing explicit recognition of uncertainty. Strategists should stress-test strategic plans against scenarios where random negative events cluster, rather than assuming they distribute evenly across time.
What Is the Central Thesis of The Black Swan, and Which Businesses Are Most Vulnerable to Its Implications?
The central thesis of The Black Swan: The Impact of the Highly Improbable is that rare, unpredictable, high-consequence events—Black Swans—dominate outcomes in complex systems, yet our psychological and institutional frameworks are systematically blind to their possibility, leaving businesses dangerously exposed to catastrophic surprise. Taleb identifies the “triplet of opacity”: the illusion of understanding, the retrospective distortion of events, and the overvaluation of factual information.
Which Businesses Are Most Vulnerable:
Financial services firms face existential Black Swan exposure. Bank of England research shows 82% of UK banks, insurers and asset managers now cite cyber attacks as a top-five risk to the financial system, up ten percentage points from 2024. A meaningful share of large financial institutions face a roughly 10% annual probability of losing 10% or more of annual profit to a single cyber event.
Supply chain-dependent manufacturers and retailers are directly exposed to geopolitical Black Swans. In April 2026, 47% of UK businesses experiencing global supply chain disruption cited the conflict in the Middle East as the reason—up 34 percentage points from February.
Energy-intensive businesses face compounding tail risks from price volatility and geopolitical disruption. 60% of UK businesses reported concern about energy prices in early May 2026, with accommodation and food service businesses reaching 86% concern.
Technology and digital businesses are exposed through cyber, regulatory, and concentration risk. The PRA’s 2026 operational resilience policy statement explicitly addresses “rising threats to operational resilience at firms and their growing reliance on externally supplied services”.
During risk register reviews—to identify where the organisation has conflated “hasn’t happened yet” with “can’t happen.”
During post-incident reviews—to avoid the retrospective distortion that makes Black Swans appear predictable after the fact.
During investment decisions—to assess whether the organisation is exposed to ruin, not just underperformance.
Business Application:
Directors should establish dedicated tail risk committees that meet independently of standard risk reviews, focusing exclusively on low-probability, high-impact scenarios. Project managers should build “kill criteria” into major projects—pre-defined conditions under which the project is stopped—rather than assuming continuation. Strategists should model scenarios where multiple Black Swans occur simultaneously, recognising that disruptions cluster rather than distribute evenly.
What Does Antifragile Teach About Building Organisations That Improve Under Stress, and How Can This Be Implemented?
Antifragile: Things That Gain From Disorder teaches that some systems are not merely robust (resistant to shocks) or resilient (recovering after shocks), but antifragile—they actually improve, strengthen, and grow when exposed to volatility, randomness, and stressors. Taleb argues this property is the highest form of adaptation available to organisations, and it can be deliberately engineered through structural choices, incentive design, and optionality.
Key Antifragile Principles for Business:
Barbell strategy: Combine extreme conservatism in core operations with aggressive, small-scale experimentation in growth areas. 75% of grant-funded UK charities use formal risk tools compared to 35% of non-grant-funded organisations, suggesting structured approaches enable greater risk capacity when combined with appropriate funding.
Optionality over prediction: Rather than forecasting the future, build portfolios of options that benefit from multiple possible outcomes. This directly addresses the observation that economic uncertainty has been the most reported challenge affecting business turnover since October 2022.
Skin in the game: Decision-makers must bear the consequences of their decisions. HM Treasury’s 2026 guidance to accounting officers frames value for money as a “balanced judgement of strategic alignment, long-term resilience, and risk,” moving beyond simple cost minimisation.
Redundancy as investment: Duplicate systems, diversified suppliers, and cross-trained teams are not waste—they are the raw material of antifragility.
When to Apply Antifragile Learning Points:
During organisational design—to build structures that benefit from uncertainty rather than merely surviving it.
During supply chain strategy—to move from just-in-time efficiency to diversified, optionality-rich sourcing.
During technology investment—to prioritise systems that learn from attacks and failures rather than merely resist them.
During talent development—to cultivate teams comfortable with volatility and skilled at rapid adaptation.
Business Application:
Operations directors should conduct “stress tests with benefit”—scenarios where the organisation not only survives disruption but emerges stronger because competitors are weakened. For example, a manufacturer with diversified suppliers can gain market share when single-source competitors face disruption. Project managers should build rapid prototyping and learning loops into delivery schedules, treating small failures as information rather than stigma. Strategists should allocate a portion of capital to small, high-optionality bets that could pay off massively in Black Swan scenarios, while simultaneously reducing exposure to ruinous tail risks.
Which Businesses Will Benefit Most from Taleb’s Frameworks, and Where in the World Are They Likely Operating?
The businesses that will benefit most from Taleb’s frameworks are those operating in high-uncertainty, high-interconnection, and high-consequence environments—particularly in the UK, Europe, North America, and Asia-Pacific where regulatory pressure, geopolitical fragmentation, and technological disruption intersect.
Sector-by-Sector Analysis:
Financial services in London, New York, Singapore, and Frankfurt face the most acute combination of regulatory scrutiny, cyber exposure, and tail risk concentration. The PRA’s PS7/26 operational resilience policy, effective from 2026, requires firms to report operational incidents and material third-party arrangements with significantly reduced burden but enhanced oversight. UK financial services compliance costs now exceed £33.9 billion annually, representing roughly 13% of average operating costs.
Manufacturing and logistics across the UK, Germany, Netherlands, and key Asian hubs are directly exposed to supply chain Black Swans. The ONS reported 7% of UK businesses experiencing global supply chain disruption in April 2026, with nearly half citing Middle East conflict.
Energy and utilities in the UK, Norway, Gulf states, and Australia face compounded tail risks from price volatility, geopolitical disruption, and transition uncertainty. 28% of UK businesses cited energy prices as a reason for considering raising prices in June 2026.
Technology and digital platform businesses globally face cyber Black Swans, regulatory tail risks, and concentration risk. The Bank of England’s 2026 H1 Systemic Risk Survey found 82% of financial institutions citing cyber attacks as a top-five systemic risk.
Healthcare and pharmaceutical supply chains across Europe, North America, and Asia are exposed to pandemic Black Swans, regulatory disruption, and geopolitical supply chain risk.
Professional services firms advising on risk, strategy, and resilience are both beneficiaries (demand for their services grows) and exposed to reputational tail risks if they fail to apply these frameworks themselves.
Geographic Concentration:
United Kingdom: Highest regulatory intensity for operational resilience, with FCA/PRA rules now in “steady-state” from 2026, enhanced regulatory powers, and cost recovery provisions.
European Union: DORA (Digital Operational Resilience Act) in force across Europe, aligning with UK approaches but creating additional compliance complexity for cross-border firms.
United States: Less prescriptive regulation but higher litigation and shareholder activism risk, particularly around cyber governance failures.
Asia-Pacific: Rapid economic growth combined with geopolitical tension, supply chain concentration, and varying regulatory maturity creates a high-Black-Swan environment.
Middle East and Africa: Geopolitical disruption, energy price volatility, and infrastructure risk create compounding tail exposure.
How Should Organisations Integrate Taleb’s Key Learning Points into Decision-Making to Boost Performance and Reduce Risk Events Derailing Business Objectives?
Organisations should integrate Taleb’s key learning points by embedding probabilistic thinking, tail risk assessment, and antifragile design principles into the governance, project management, and strategy functions at the point of decision, not as an afterthought. The evidence suggests this is not optional: UK business confidence dropped to a net figure of -76 in March 2026, compared to -63 in February, according to Institute of Directors research. Fewer businesses were set up in Q1 2026 than in any comparable period on record. The organisations that survive and thrive will be those that internalise Taleb’s lessons before the next Black Swan arrives.
Board-Level Integration:
Establish a Tail Risk Committee reporting directly to the board, separate from the standard audit and risk committee, with a mandate to challenge assumptions of normality and identify ruin exposure.
Require probabilistic decision papers: every significant capital allocation or strategic decision must include explicit probability assessments, not point forecasts.
Implement decision journals that record expectations, rationale, and confidence levels before outcomes are known, reviewed quarterly to identify systematic biases.
Project Management Integration:
Build kill criteria into every major project: pre-defined conditions under which the project is terminated, removing sunk-cost bias from continuation decisions.
Apply barbell resource allocation: commit 80-90% of resources to high-confidence, low-variance delivery, and 10-20% to experimental, high-optionality initiatives that could benefit from disorder.
Conduct pre-mortems at project initiation: assume the project has failed catastrophically and work backwards to identify causes.
Strategy Integration:
Replace single-scenario planning with multiple scenarios including Black Swan scenarios where multiple disruptions compound.
Develop antifragile supply chains with diversified sourcing, redundancy, and optionality—accepting higher baseline costs as insurance against tail events.
Invest in optionality: maintain cash reserves, flexible contracts, and strategic options that can be exercised when volatility creates opportunity.
Operational Resilience Integration:
Align with regulatory requirements proactively: the PRA’s operational resilience framework requires firms to remain within impact tolerances for important business services under severe but plausible disruption scenarios.
Conduct regular stress tests that include cyber, geopolitical, and supply chain scenarios simultaneously, recognising that disruptions cluster.
Measure resilience value not just as cost avoidance but as competitive advantage: government analysis shows that increased resilience reduces both the likelihood of severe outcomes and the scale of losses when disruption occurs.
When to Apply These Frameworks:
Annually during strategy and budget cycles: full Black Swan scenario review and antifragile portfolio assessment.
Quarterly during board risk reviews: tail risk exposure review and decision journal analysis.
Monthly during project reviews: kill criteria assessment and pre-mortem updates.
Continuously through operational monitoring: early-warning indicators and antifragile capacity metrics.
Post-incident after any disruption: structured learning review applying Fooled by Randomness lessons about attribution.
Why Are These Books Particularly Relevant for Operational Resilience & Tail Risk Strategy in September 2026?
These books are particularly relevant in September 2026 because the operating environment has become precisely the kind of high-volatility, high-interconnection, high-consequence system that Taleb’s frameworks were designed to address. The ONS Business Insights survey for April 2026 showed economic uncertainty at 40% for larger businesses—the highest proportion since the question was introduced. Global supply chain disruption reached 9% in March 2026, the highest since December 2022. The PRA’s operational resilience rules are now in full effect, with “steady-state” expectations and enhanced regulatory powers to demand information, direct remediation, and recover supervisory costs. Bank of England analysis confirms that “average impacts are not representative of overall risk exposure” and that “tail events can dominate total losses and can threaten business continuity”.
Taleb’s trilogy provides the intellectual architecture to navigate this environment. Fooled by Randomness teaches the discipline of statistical scepticism. The Black Swan reveals the structural blind spots that make organisations vulnerable to rare events. Antifragile offers the design principles to build systems that improve under stress. Together, they constitute a complete risk literacy curriculum for directors, project managers, and strategists who need to make decisions when the future refuses to behave as forecast.
The value proposition is not merely defensive. Organisations that internalise these lessons will identify opportunities that competitors miss—in supply chain restructuring, in optionality-rich investment strategies, in resilient operational models that become competitive advantages when disruption hits. The question is not whether the next Black Swan will arrive, but whether your organisation will be fooled by randomness when it does.
#OperationalResilience #TailRiskStrategy
Get help to protect and grow your business faster with BusinessRiskTV
Most “resilient” UK businesses are just lucky. And 40% of larger UK firms just admitted economic uncertainty is beating them.
That’s not a vibe. That’s the ONS Business Insights survey, April 2026: 40% of UK trading businesses with 10+ employees cited economic uncertainty as the top challenge hitting turnover — the highest since the question began in April 2022.
So here’s the uncomfortable question: if your risk register still assumes the future looks like the last 5 years, what exactly are you protecting?
BusinessRiskTV Business Risk Management Club recommends these books to help the reader make better decisions on Operational Resilience & Tail Risk Strategy.
Keep reading — because the third book is the one that changes how you allocate capital.
There are 3 books that do more for operational resilience than most 40-page board packs:
1. Fooled by Randomness — Nassim Nicholas Taleb
It asks: how much of your “performance” is skill, and how much is luck?
If UK businesses swing from 27% reporting turnover decreases to 15% reporting increases in a matter of months, how much of that is strategy — and how much is noise?
Most post-mortems invent a story. Taleb shows you why that story is usually wrong.
2. The Black Swan — Nassim Nicholas Taleb
It asks: what rare event would wipe out the plan?
82% of UK banks, insurers and asset managers now cite cyber attacks as a top-five risk to the financial system, per Bank of England H1 2026 research.
47% of UK businesses hit by global supply chain disruption in April 2026 blamed the Middle East conflict — up 34 percentage points from February.
Cyber-attacks cost UK businesses £3.7bn in litigation over the past year.
That’s not a tail risk. That’s a board-level blind spot.
Wait — here’s the counterintuitive part.
3. Antifragile — Nassim Nicholas Taleb
It asks: what gets stronger when stressed?
Not “robust.” Not “resilient.” Antifragile.
The PRA’s 2026 operational resilience policy puts firms in “steady-state” with enhanced powers to demand information, direct remediation and recover supervisory costs.
UK financial services compliance costs now exceed £33.9bn a year — roughly 13% of average operating costs.
If you’re spending that much on defence, Taleb’s barbell strategy is the difference between surviving volatility and profiting from it.
Here’s the 3-question test most teams never run:
What would actually ruin us — not just hurt quarterly earnings?
What looks like skill but is statistically indistinguishable from luck?
What part of the business gets stronger when suppliers fail, cyber hits, or energy spikes?
If you can’t answer those three with specific numbers and named owners, you don’t have a tail risk strategy. You have a hope strategy!
Directors, project managers and strategists: this is why these books matter now. Not in theory. In capital allocation, kill criteria, supplier diversification, decision journals and pre-mortems.
Email editor@businessrisktv.com with the subject line TALEB 3 and tell me which of the three books your board needs to read first.
BusinessRiskTV reviews Douglas W. Hubbard’s The Failure of Risk Management—why heat maps fail and how quantitative risk analysis fixes ERM in 2026.
BusinessRiskTV Book Review: The Failure of Risk Management
BusinessRiskTV Business Risk Management Club recommends this book product as the solution to the problem of poor enterprise risk management application in business.
That recommendation carries weight because the problem is measurable. 65% of UK organisations now believe a serious cyber attack could threaten their survival, yet 1 in 5 have chosen not to report a serious cyber incident to avoid negative consequences. With economic uncertainty cited by 29% of UK trading businesses as their top challenge affecting turnover in September 2026, and 28% reporting decreased turnover, the gap between how businesses think they manage risk and how they actually do is costing real money. Hubbard’s book confronts that gap head-on.
What Is The Failure of Risk Management About?
The Failure of Risk Management explains why common risk management techniques are causing bad decision-making and provides a practical framework for adopting accurate, quantitative risk analysis methodology. Renowned risk analysis expert Douglas W. Hubbard argues that many popular risk management methods are “mere placebos which do nothing to reduce risk and improve decisions”. The book is divided into three parts: an introduction to risk analysis, a critique of what is broken, and a practical guide to fixing it.
Hubbard’s core argument is that qualitative methods like risk matrices and heat maps look sophisticated but are often misleading. He presents a convincing case for probabilistic risk analysis using Monte Carlo simulation as the best approach. The second edition includes updated case studies and expanded guidance on probability modelling, emphasising the efficacy of appropriate risk methodology in practical applications.
Why Should Risk Officers and Business Leaders Read This Book in 2026?
Risk officers and business leaders should read this book in 2026 because the gap between qualitative risk theatre and quantitative risk reality has never been more costly, as current UK business data demonstrates. The UK Government’s own 2026 National Risk Register acknowledges that “the risks the UK faces are more volatile, varied and interconnected than any time in living memory,” listing 95 distinct risks including 87 standalone risks and 8 linked scenarios. Yet the Government Major Projects Report at the end of March 2026 revealed that only 15% of major projects held a Green rating, while 58% were Amber and 18% were Red. These are the very projects where quantitative risk modelling should be standard practice.
Hubbard’s critique is not abstract. The Wood Group was fined almost £13m in March 2026 for failures in financial reporting and systems of controls, with the FCA citing a “poor financial culture”. Carillion’s former finance directors were fined for failing to reflect serious financial troubles in company announcements. These are not failures of risk identification—they are failures of risk quantification and honest communication. Hubbard’s framework directly addresses these systemic weaknesses.
Who Will Benefit Most from Buying and Applying This Book?
Risk officers, compliance teams, project managers, CFOs, board members, and enterprise risk management professionals will benefit most from buying and applying this book. The book targets management consultants and economists primarily, but Hubbard offers important suggestions for war quants and actuaries as well. Specifically:
Risk officers seeking to move from qualitative heat maps to quantitative modelling will find a step-by-step methodology for calibration and probability estimation
Compliance teams facing increasing regulatory scrutiny—the FCA’s actions against Wood Group and Carillion directors show that regulators now expect boards to monitor risk management frameworks effectively
Project managers managing complex programmes will benefit from Hubbard’s practical rules for risk registers, including the principle that risks requiring executive notification belong on the register, while those with trivial impacts do not
CFOs and finance directors grappling with supply chain disruptions—70% of UK businesses have faced greater financial exposure due to supply chain instability, with average annual collection costs rising to over £420,000
Board members who need to understand why “seeing all risks displayed in an organised, visual format” does not mean they are under control
When Should Potential Buyers Buy This Book?
Potential buyers should buy this book immediately if their organisation currently relies on qualitative heat maps, colour-coded risk matrices, or consensus-based risk scoring, because these methods are failing under the weight of 2026’s interconnected risk landscape. The timing is critical for several reasons:
Regulatory pressure is intensifying: The UK Corporate Governance Code now asks boards to monitor company risk management and their controls frameworks, yet many boards lack the quantitative tools to do so
Cyber risk is existential: 65% of UK organisations say a serious cyber attack could threaten their survival, and AI-driven attacks have more than doubled in frequency over the last 12 months, now affecting 25% of organisations
Supply chain volatility is structural, not temporary: 28% of UK businesses with 10 or more employees reported concern about international conflict impacting supply chains, while 21% were concerned about shipping disruption
The cost of inaction is quantifiable: Late payments cost the UK economy £11 billion annually, and 38 businesses close every day due to cashflow problems
Buy the book before your next risk committee meeting. Buy it before your next board reporting cycle. The organisations that adopt quantitative methods now will be the ones still trading in 2027.
Where in the World Will Your Business Be to Take Advantage of This Book’s Knowledge?
UK-based businesses of all sizes—from SMEs to FTSE-listed corporates—will benefit most from this book’s knowledge, because the UK’s current risk environment provides the most immediate and measurable case for quantitative risk management. The UK is uniquely positioned to apply Hubbard’s framework:
UK SMEs are owed an average of £66,770 in late payments, and nearly half of UK companies expect the economy to deteriorate in the next 12 months
UK corporates face heightened governance scrutiny following the Carillion and Wood Group enforcement actions, making Hubbard’s methodology for demonstrating risk competence at board level directly applicable
UK public sector bodies managing the 95 risks in the National Risk Register need quantitative prioritisation to allocate limited resources effectively, as the Resilience Action Plan acknowledges the need to “assess how resilient the UK is to target interventions and resources”
UK critical national infrastructure operators in water, power, and communications face risks that Hubbard’s methods were originally designed to address—his approach draws from “nuclear power, exploratory oil, and other areas of business and government” where quantitative risk analysis is already standard practice
What Are the Key Takeaways for Business Decision Makers?
Key takeaways from The Failure of Risk Management that business decision makers can immediately apply include abandoning heat maps for quantitative methods, calibrating probability estimates, and using Monte Carlo simulation to model uncertainty. The most actionable insights are:
Heat maps create false confidence: Colour-coded risk matrices oversimplify complex risks, lack granularity, cannot account for risk tolerance, and encourage subjective assessment—yet executives treat them as rigorous analysis
Quantitative analysis is achievable without a PhD: Hubbard provides practical guidance on probability modelling and empirical inputs, showing that “you don’t need high levels of complexity or a PhD in math to make significantly better-informed risk management decisions”
Calibrate your experts: People do not naturally estimate probabilities well, but a little training can significantly improve accuracy—Hubbard provides tests in the appendix for calibrating probability estimations
Review past models against reality: The best way to know if a model works is to check how past forecasts performed—Hubbard checked over 100 of his own probability forecasts and found events predicted at 30% occurred approximately 30% of the time
Apply simple risk register rules: If the impact is so trivial you don’t need to tell anyone, it doesn’t belong on the register; if the probability exceeds 1 (it’s expected to happen), it’s not a risk but a project plan item
Learn from near misses: Treating near misses as successes rather than failures is a critical barrier to organisational learning that Hubbard identifies as a common failure mode
How Can You Maximise the Knowledge in This Book for Practical Business Benefit?
To maximise the knowledge in this book for practical business benefit, implement Hubbard’s four key measures: identify deficiencies in your current strategy, adopt a calibrated approach to risk analysis using up-to-date statistical tools, employ accurate quantitative risk analysis and modelling methods, and revisit your models against real outcomes. The practical implementation path is clear:
Start with a risk audit: Hubbard advises risk managers to identify deficiencies in their current strategy and fix them, rather than attempting a wholesale replacement of existing systems
Convert qualitative to quantitative: Where your risk register uses high/medium/low, convert these to probability estimates—”estimate the probability that the event will happen inside of the timeframe”
Use existing data before building new models: Where possible, review historical data to see what the real impact of similar events has been, rather than relying on subjective estimates
Frame risks in financial terms: Quantitative risk assessments assign numerical values to risks, allowing decision-makers to weigh the cost of each risk against its potential impact, enabling more strategic resource allocation
Establish feedback loops: Create a culture of purchase reflection where you document experiences, ask what happened and why, price assess reoccurrence likelihood, and identify practical steps to change outcomes
Join a community of practice: The BusinessRiskTV Business Risk Management Club provides access to exclusive webinars, workshops, and reports from leading risk management experts, with monthly risk intelligence briefings covering geopolitical, economic, and technological trends
Is The Failure of Risk Management Value for Money?
The Failure of Risk Management represents exceptional value for money when measured against the cost of poor risk management decisions that it helps prevent. Consider the arithmetic:
The book retails at approximately £39, while the average annual cost of collections from late payments alone has risen to £421,800 per business—a 14.5% increase from £368,400 in 2025
Cyber incidents cost UK small firms an average of $52,000 (approximately £41,000) per year and cause about 32 hours of disruption, yet average investment in cyber resilience measures stands at only $51,000—almost matching the cost of incidents themselves
Late payment costs the UK economy £11 billion annually, and 38 businesses close every day due to cashflow problems
The book’s insights, if applied to even one significant risk decision, could save an organisation many multiples of its
Hubbard’s methodology has earned critical praise from Gartner and Forrester Research, and the second edition includes fresh examples from the 2008 credit crisis, natural disasters, outsourcing failures, and engineering disasters. As Sam L. Savage, Executive Director of ProbabilityManagement.org, wrote: “Some study the theory of risk management. Some actively engage in risk management and find that what works in theory does not always work in practice. Some develop new technologies that will make risk management work better in the future. Doug Hubbard does all three. That’s why this book should be your risk management must-read”.
Final Verdict
The Failure of Risk Management is essential reading for any business decision maker who suspects their current risk approach is not delivering genuine insight or protection. In a year where the UK terrorism threat has increased to SEVERE, the National Risk Register lists 95 distinct risks, and 65% of organisations fear cyber attack could threaten their survival, continuing to rely on colour-coded heat maps is not risk management—it is risk theatre. Hubbard provides the practical, proven alternative that business leaders need.
BusinessRiskTV Business Risk Management Club recommends this book product as the solution to the problem of poor enterprise risk management application in business.
Get help to protect and grow your business faster with BusinessRiskTV
That’s not my line. It’s the uncomfortable conclusion Douglas W. Hubbard forces you to confront in The Failure of Risk Management: Why It’s Broken and How to Fix It.
And in September 2026, the numbers back him up.
65% of UK organisations say a serious cyber attack could threaten their survival. 1 in 5 have chosen not to report a serious cyber incident. ONS-linked business data shows 29% of UK trading businesses cite economic uncertainty as their top challenge affecting turnover. 28% report decreased turnover.
The UK Government’s own National Risk Register lists 95 distinct risks. The Government Major Projects Report at the end of March 2026 showed only 15% of major projects rated Green. 58% Amber. 18% Red.
Wood Group was fined almost £13m in March 2026 for financial reporting and controls failures. Carillion’s former finance directors were fined for failing to reflect serious financial troubles in company announcements.
Yet many boards still stare at red-amber-green heat maps and call it risk management.
Here’s the part most risk committees miss: Hubbard doesn’t just attack heat maps. He shows you what to replace them with. And the replacement does not require a PhD in math.
What to apply immediately:
Convert “high / medium / low” into probability estimates. If it’s a risk, ask: what is the probability this happens inside the timeframe?
Calibrate your experts. Hubbard checked over 100 of his own probability forecasts. Events predicted at 30% occurred approximately 30% of the time. Most organisations never test their experts this way.
Use Monte Carlo simulation to model uncertainty instead of arguing over colour codes.
Apply Hubbard’s risk register rule: if the impact is so trivial you don’t need to tell anyone, it doesn’t belong on the register. If the probability exceeds 1, it’s not a risk—it’s a project plan item.
Review past models against reality. If your 2024 risk register said “low likelihood” and it happened twice, your model is broken.
Treat near misses as data, not as successes. That is one of the biggest barriers to organisational learning Hubbard identifies.
Wait—there’s more. This is where it gets expensive
70% of UK businesses have faced greater financial exposure due to supply chain instability. Average annual collection costs have risen to over £420,000. Late payments cost the UK economy £11 billion annually. 38 businesses close every day due to cashflow problems.
The book costs about £39. One avoided bad risk decision pays for it thousands of times over. That is not a book expense. That is risk management value for money.
Who benefits most? Risk officers, compliance teams, project managers, CFOs, board members, and enterprise risk management professionals. When should you buy it? Before your next risk committee meeting. Before your next board reporting cycle. Where will it pay off? UK SMEs owed an average of £66,770 in late payments. FTSE corporates under FCA scrutiny. Public sector bodies managing 95 National Risk Register risks. Critical national infrastructure operators in water, power, and communications.
Read to the end for the one question that exposes a broken risk process:
If your risk register disappeared tomorrow, what decision would actually change?
If the answer is “none”, you don’t have a risk process. You have risk theatre.
Want the practical rollout? Email editor@businessrisktv.com with the subject line RiskClub for more information on BusinessRiskTV Business Risk Management Club.
BusinessRiskTV Business Risk Management Club recommends CyberPower Line-Interactive UPS as one solution to power outages and infrastructure downtime risk.
“BusinessRiskTV Business Risk Management Club recommends CyberPower Line-Interactive UPS as one solution to the problem of Power Outages & Infrastructure Downtime Risk.”
That recommendation is grounded in hard numbers: UK businesses lost an estimated £3.7 billion in 2023 from internet outages alone, with smaller businesses facing up to £1,000 per hour of downtime. For mid-sized commercial operations, downtime costs typically range from £5,000 to £18,000 per hour during power outages. Meanwhile, 64% of UK remote workers have suffered an internet or power outage in the past year — equating to an estimated 12 million people.
What Is the Power Outages & Infrastructure Downtime Risk Review?
The Power Outages & Infrastructure Downtime Risk Review is a structured assessment of how vulnerable your organisation is to electricity supply disruption, brownouts, surges, and the cascading operational failures they trigger.
This review examines three critical layers of exposure:
Grid-level risk: The likelihood and frequency of power interruptions in your region
Infrastructure vulnerability: Whether your servers, network hardware, and workstations can survive a sudden power loss without damage or data corruption
Business continuity gap: How long your operations can continue — or safely shut down — when mains power fails
The UK government’s Statutory Security of Supply Report 2025 concludes that while GB is expected to access sufficient electricity supplies, network reliability remains a live concern, with growing focus on resilience against high-impact weather events. The National Preparedness Commission has noted that risk vectors including extreme weather and infrastructure ageing “create a troubling outlook” for UK energy security.
Why Do Small-Business Owners and Remote Workforces Buy UPS Systems?
Small-business owners and remote workforces deficit buy UPS systems to shield servers, network hardware, and work ofstations from sudden power drops, brownouts, and hardware -damaging surges that cause data loss, equipment destruction,1 and operational paralysis.
The purchase drivers are overwhelmingly practical:
Data integrity: An unexpected shutdown can corrupt databases, lose unsaved work, and trigger hours of IT recovery. For remote workers handling time-critical tasks, this risk is acute — research found that roughly 5% of remote workers experiencing outages are doing time-critical or high-value work, potentially affecting 470 million hours annually.
Hardware protection: Voltage spikes and surges can shorten equipment lifespan or destroy it outright. Power outages are not merely inconvenient; they carry secondary costs including lost productivity, idle staff wages, and the administrative burden of system restoration.
Revenue protection: For retail and hospitality businesses, even brief outages disrupt POS systems, refrigeration, and security — leading to spoiled stock and lost sales. A Sheffield café owner reported losing between £2,000 and £3,000 worth of food in a single outage.
Remote workforce resilience: ONS data shows that 40% of the UK workforce spent time working from home in early 2023, and home office setups are “nowhere near as resilient as a traditional office environment”. A UPS provides that missing layer of protection.
How Do You Maximise the Benefit of a UPS as a Risk Control Measure?
You maximise the benefit of a UPS as a risk control measure by matching the unit to your actual load profile, implementing automatic shutdown protocols, and integrating the UPS into a broader business continuity plan that includes regular testing and staff awareness.
Right-size the unit: Calculate the total wattage of equipment you need to protect — servers, routers, switches, NAS devices, and critical workstations — and choose a UPS with at least 30% headroom above that load.
Use the management software: CyberPower’s PowerPanel software enables automatic, graceful shutdown of connected systems before battery depletion, preventing data corruption and enabling rapid recovery.
Prioritise critical loads: Not everything needs battery backup. Use surge-only outlets for peripheral devices and battery-protected outlets for core infrastructure.
Test regularly: Simulate outages quarterly to verify runtime meets your safe shutdown window. The Wyre Council’s procurement report noted their UPS provided approximately 30 minutes of power — “enough for a clean shutdown of all systems”.
Layer with cloud backup: A UPS buys time; cloud-based backup ensures data survives even if local hardware is damaged.
Who Will Benefit Most from Purchasing a CyberPower Line-Interactive UPS?
Small-business owners, remote workforces, home office professionals, and IT managers responsible for small server rooms or network closets will benefit most from purchasing a CyberPower Line-Interactive UPS.
The beneficiary profile breaks down as follows:
Remote workers and home offices: With 64% of UK remote workers having experienced a recent outage, a compact UPS protecting a router, modem, and laptop dock can mean the difference between a minor inconvenience and a lost workday.
Small businesses with on-premise infrastructure: Retailers, clinics, accountants, and professional services firms running local servers, POS systems, or VoIP telephony need battery backup to maintain transactions and communications.
Small server rooms and network closets: A line-interactive UPS protects switches, firewalls, and NAS devices, preventing network-wide outages that cascade across the organisation.
Businesses in high-outage regions: The North West of England recorded 50,892 unplanned outages since 2021, followed by Scotland at 15,831 and Wales at 9,036.
When and Where Are Businesses Most at Risk as at September 2026?
Businesses are most at risk as at September 2026 in regions facing extreme weather, ageing grid infrastructure, and hydroelectric dependency — with the UK, parts of North America, and Latin America currently under heightened threat.
United Kingdom: Digital modelling by Neara found that over 3.5 million people are currently at risk of power outages, with a nationwide 100mph storm potentially cutting power to 3.6 million people and a Category 2 hurricane-equivalent event threatening 23 million. The UK had already experienced 14,500 unplanned outages by July 2025, with expectations of a further 10,000 before year-end — a 30% increase on 2024.
Latin America (Ecuador and Venezuela): As of late September 2026, officials in both countries have warned of renewed nationwide power outages driven by El Niño-related drought reducing hydroelectric output. Ecuador faces a structural power–1,200 MW, with rationing potentially extending to medium-consumption firms.
United States: Summer 2026 saw multiple large-scale outages and price spikes driven by extreme heat, hurricanes, and AI data centre demand straining an ageing grid where over 75% of distribution transformers are more than 50 years old.
Seasonal timing: September marks the transition from summer heat stress to autumn storm season in the Northern Hemisphere — a period when grid operators in the UK and Northern Europe face elevated risk from high winds and falling trees damaging overhead lines.
What Are the Features of CyberPower Line-Interactive UPS?
CyberPower Line-Interactive UPS features include Automatic Voltage Regulation (AVR), line-interactive topology, LCD status display, surge and spike protection, energy-saving GreenPower UPS™ technology, PowerPanel management software, and generator compatibility.
Key technical features across the CyberPower line-interactive range include:
Line-interactive UPS topology: The UPS regulates voltage continuously and only switches to battery when necessary, extending battery life and improving efficiency compared to offline/standby units.
Automatic Voltage Regulation (AVR): Single boost and single buck AVR corrects brownouts and overvoltages without draining the battery, maintaining stable output voltage during fluctuations.
Simulated sine wave output: Provides compatible power for most IT equipment including servers, routers, and workstations.
LCD status display: Real-time information on operation type, power status, battery status, load status, and fault warnings, with configurable settings for alarms, input/output, and battery management.
Surge and spike protection: Protects connected equipment from voltage spikes, with surge suppression ratings (e.g., 450 joules on the VP1200ELCD model) and EMI/RFI filtration.
PowerPanel management software: Enables automatic, graceful shutdown of connected systems during extended outages, monitor UPS status, and configure alerts.
Generator compatible: Designed to work with backup generators, enabling seamless transition from battery to generator power during prolonged outages.
Energy-saving GreenPower UPS™ technology: Bypass technology reduces energy consumption and heat loss, lowering running costs and carbon footprint.
Data line protection: RJ11/RJ45 and coax protection for phone, network, and cable connections, guarding against surges travelling through communication lines.
USB charging ports: Select models include USB-A and USB-C charging ports for mobile devices.
Runtime specifications: For example, the VP1200ELCD provides 12 minutes at half load and 4 minutes at full load — sufficient for safe shutdown of critical systems. The BR700ELCD provides 6 minutes at half load and 1.5 minutes at full load.
What Evidence Supports the Cost-Effectiveness of UPS as a Risk Control?
UK government, Ofgem, and independent research evidence supports the cost-effectiveness of UPS as a risk control, showing that the financial damage from a single outage event vastly exceeds the purchase and maintenance cost of protective equipment.
Government economic modelling: The UK government’s electricity engineering standards review simulated a 24-hour GB-wide power outage and estimated economic damage of between £5.2 billion and £5.5 billion.
Ofgem SME valuations: Ofgem research found that SMEs require an average payment of £165.07 to accept a one-hour interruption during winter at non-peak times on a typical working day. The Value of Lost Load (VoLL) for SMEs ranges from £33,358 to £39,213 per MWh.
Real-world procurement evidence: Wyre Council approved a UPS and generator solution at an initial cost of £39,184, with the assessment that “the solution still represents value for money” and offers “competitive value for money taking into consideration the additional elements required for fully automated failover”.
Return on investment: UPS systems prevent downtime, data loss, and hardware damage — often saving far more than their purchase and maintenance costs. More than 33% of organisations that experience a computer disaster lose between £7,500 and £250,000, while 20% lose between £250,000 and £750,000.
Business continuity value: A solid UPS setup can be a core part of the wider business continuity plan, making outages “unnoticeable” for small teams.
How Does the CyberPower Line-Interactive UPS Compare for Value?
The CyberPower Line-Interactive UPS compares favourably for value because it combines essential protection features — AVR, surge protection, management software, and generator compatibility — at a price point accessible to small businesses and remote workers.
Energy efficiency savings: CyberPower’s GreenPower UPS™ bypass technology reduces power consumption during normal operation, lowering electricity costs over the unit’s lifetime.
Battery replaceability: Select models feature user-replaceable batteries, extending the unit’s service life and reducing long-term ownership costs.
Scalability: The range spans compact desktop units (700VA) to tower models (1200VA and above), allowing businesses to start small and expand protection as infrastructure grows.
Comprehensive protection package: Unlike basic surge protectors, a line-interactive UPS provides both surge protection and battery backup — two distinct risk controls in one device.
What Should Your Next Step Be?
Your next step should be to conduct a Power Outages & Infrastructure Downtime Risk Review, then consider deploying CyberPower Line-Interactive UPS units at critical points identified in that review.
Audit your critical loads: Identify every device that cannot tolerate a sudden power loss — servers, network switches, routers, POS terminals, and workstations handling time-critical tasks.
Calculate runtime requirements: Determine how many minutes of battery backup you need for safe shutdown (typically 10–30 minutes for servers and network equipment).
Select CyberPower models: Match the UPS capacity to your load profile, choosing from the Value, BR, or VP series based on runtime and outlet requirements.
Implement automatic shutdown: Install PowerPanel software and configure graceful shutdown for all protected systems.
Document and test: Include the UPS in your business continuity plan, test quarterly, and train staff on what to do when the alarm sounds.
“BusinessRiskTV Business Risk Management Club recommends CyberPower Line-Interactive UPS as one solution to the problem of Power Outages & Infrastructure Downtime Risk.”
In a landscape where a single outage can cost a small business up to £1,000 per hour — and where 3.5 million people in the UK already face elevated outage risk — the question is not whether you can afford a UPS, but whether you can afford to operate without one.
If your business runs without a UPS, you’re not saving money — you’re gambling £5,000–£18,000 per hour on the assumption that the grid will never blink.
That sentence annoys people. Good. Because the numbers don’t care how you feel.
“BusinessRiskTV Business Risk Management Club recommends CyberPower Line-Interactive UPS as one solution to the problem of Power Outages & Infrastructure Downtime Risk.”
Here’s the topic hiding in plain sight: Power Outages & Infrastructure Downtime Risk Review. Not “buy a battery box.” A review of what actually fails, what it costs, and what to protect first.
The UK lost an estimated £3.7bn to internet outages in 2023. Small businesses: up to £1,000/hour. Mid-sized operations: £5k–£18k/hour. But the outage is only the first invoice. The second invoice is corrupted data, dead switches, lost POS sales, spoiled stock, and staff sitting idle.
Keep reading — the third number below is the one that should make you audit your server room tonight.
3.5 million people in the UK are currently at risk of power outages, according to Neara digital modelling. A 100mph storm could cut power to 3.6 million.
14,500 unplanned outages had already hit the UK by July 2025 — with 10,000 more expected before year-end, a 30% increase on 2024.
Wyre Council approved a UPS and generator solution at £39,184 and still assessed it as value for money. That’s what real resilience costing looks like.
Ofgem research found SMEs need an average £165.07 to accept a one-hour winter interruption. The Value of Lost Load for SMEs runs £33,358–£39,213 per MWh.
64% of UK remote workers have suffered an internet or power outage in the past year. That’s roughly 12 million people.
But here’s the part most UPS buyers get wrong: they buy a surge strip, plug in a router, and call it business continuity. That’s not a risk control. That’s a placebo.CyberPower Line-Interactive UPS features that actually matter:
Automatic Voltage Regulation (AVR) corrects brownouts and overvoltages without draining the battery.
Line-interactive topology switches to battery only when needed — better efficiency and longer battery life.
PowerPanel software triggers automatic, graceful shutdown before the battery dies.
LCD status display shows load, battery, fault, and operation status in real time.
GreenPower UPS™ bypass technology cuts energy consumption and heat loss.
Generator compatible, surge/spike protected, and available with user-replaceable batteries.
Example runtime: VP1200ELCD gives 12 minutes at half load, 4 minutes at full load — enough for a clean shutdown.If you only remember one line, make it this one: a UPS doesn’t stop the outage. It stops the outage from becoming a data loss, hardware replacement, and payroll problem.
So what do you do next?
Audit every critical load: servers, switches, routers, POS, NAS, workstations.
Size the UPS with at least 30% headroom above your total wattage.
Install PowerPanel and configure graceful shutdown.
Test quarterly. Document it in your business continuity plan.
Train staff on what to do when the alarm sounds.
Email editor@businessrisktv.com with the subject line “UPS RISK REVIEW” for more information on Business Risk Management Club. If you’re still running critical infrastructure on mains power alone, you’re one storm away from finding out what downtime really costs.
BusinessRiskTV Business Risk Management Club recommends Jackery Solar Generator 1000 v2 for business continuity & supply chain power disruptions. 1070Wh LiFePO4.
BusinessRiskTV recommends Jackery Solar Generator 1000 v2 for business continuity & supply chain power disruptions. 1070Wh LiFePO4, 1500W AC, 1hr fast charge.
That recommendation carries weight because it is not made lightly. In 2024 alone, the UK recorded over 18,398 unplanned power outages — a 4.7% increase year-on-year — while more than 80,000 blackouts have occurred since 2021. The Energy Networks Association reported that Storm Darragh left over 2 million homes without power in winter 2024-25, and Storm Éowyn cut electricity to more than one million customers. When UK businesses lost an estimated £3.7 billion in a single year from internet outages alone, and smaller businesses face downtime costs of up to £1,000 per hour, the question is no longer whether a power disruption will affect your operations — it is whether you will be ready when it does.
What Happens to Your Business When the Grid Goes Down?
What happens to your business when the grid goes down is that operations stop, revenue halts, and recovery costs escalate — fast. The data paints a stark picture of the exposure UK organisations carry:
14,500 unplanned power outages had already occurred by the end of July 2025, with a projected 30% increase compared to 2024 totals
The North West alone suffered 50,892 unplanned outages since 2021 — over 1,000 per month
88% of businesses without a continuity plan fail within just over a year of a major disruption
Only 16% of employees say they have received clear instructions on what to do during a power outage or similar crisisFor mobile operations, pop-up retailers, and field workers, the grid is not a convenience — it is a dependency. When it fails, point-of-sale systems go dark, refrigeration units stop, communications collapse, and stock spoils. One Brighton trader estimated that power cuts were costing his business up to £10,000 on a busy sales day. A town centre in Malvern reported at least 10 outages in 18 months, leaving restaurants and shops repeatedly unable to serve customers.The Heathrow substation fire in March 2025 demonstrated that even the UK’s most critical infrastructure — with multiple independent power intakes — can be taken offline by a single point of failure, disrupting over 200,000 passengers and halting supply chains across the nation. The Kelly Review concluded that redundancy alone does not equal resilience.”Businesses across the UK are operating in an environment where downtime can have serious financial and reputational consequences. When connectivity, power or systems fail, the impact is immediate.” — Comms Business, 2026
How Can Portable Power Stations Protect Your Business Continuity?
Portable power stations protect your business continuity by providing immediate, silent, emission-free backup power that activates the moment the grid fails. Unlike diesel generators that require fuel storage, ventilation, and regular maintenance, modern LiFePO4 power stations are plug-and-play, require zero ongoing consumable costs, and can be deployed in indoor and outdoor locations without regulatory complications.
The business case is straightforward:
Revenue protection: An hour of downtime costs up to £1,000 for smaller businesses. A portable power station that keeps tills, card readers, and lighting operational through a 4-hour outage can pay for itself in a single incident.
Operational flexibility: Mobile operations, pop-up retail, construction sites, and field teams can run entirely off-grid without trailing cables or noisy generators.
Supply chain resilience: When local grid failures disrupt logistics and communications, battery backup maintains the critical systems that keep orders moving and customers informed.
Regulatory alignment: The UK government’s National Business Resilience Planning Assumptions explicitly identify power infrastructure failure as a key risk requiring business continuity provisions.The Continuity Forum has warned that “power outages, supply disruptions, flooding, and IT failures carry human and economic costs far beyond what is captured in current regulatory and corporate accountability frameworks”. In other words, the true cost of being unprepared is systematically underestimated by most organisations.
Why Is the Jackery Solar Generator 1000 v2 the Standout Solution?
The Jackery Solar Generator 1000 v2 is the standout solution because it delivers 1,070Wh of LiFePO4 battery capacity, 1,500W AC output (3,000W surge), 100W USB-C output, and a 1-hour fast charge — all in a unit weighing just 23.8 lbs. It is the portable power station that bridges the gap between professional-grade reliability and consumer-friendly portability.
Key specifications:
Battery: 1,070Wh LiFePO4 (lithium iron phosphate) — the chemistry used in commercial energy storage for its 4,000+ cycle lifespan, thermal stability, and safety profile
Output: 1,500W AC continuous / 3,000W surge, 100W USB-C, multiple DC ports — capable of running fridges, power tools, laptops, lighting, communications equipment, and medical devices
Recharge: 1-hour fast charge from mains; solar recharge via the included 100W SolarSaga panel for indefinite off-grid operation
Portability: 23.8 lbs with an integrated handle — genuinely transportable by a single person
Solar pairing: The 100W SolarSaga panel uses high-efficiency monocrystalline cells and folds for easy transport, enabling true energy independence during extended grid failuresPopular Mechanics testing found that the Explorer 1000 v2 powered a 25-cubic-foot refrigerator for more than 18 hours — a real-world benchmark that translates directly to business continuity for food retail, hospitality, and cold-chain operations. ZDNet’s reviewer described it as falling into the “Goldilocks zone of both price and portability” and a “solid, expandable portable power station” for emergencies and power outages. For RV adventures, van life, and off-grid living, the 100W solar panel provides a sustainable recharge loop. For business deployments — mobile operations, pop-up retail, field engineering, construction — the 1-hour mains recharge means the unit can be back to full capacity during a lunch break.Cost and value for money:
The Jackery Solar Generator 1000 v2 with 100W panel has been discounted from £1,199 to £521 — a £678 saving (57% off)
Earlier promotional pricing saw the package at £699 (42% discount)
With a LiFePO4 lifespan of 4,000+ cycles, the cost per cycle is approximately £0.13–£0.17 depending on purchase price — significantly lower than the cost of even one hour of business downtime
No fuel costs, no maintenance contracts, no emissions, no noise — a fraction of the total cost of ownership of a diesel generatorFor context: if a single power outage costs your business just one hour of lost trading at the smaller-business benchmark of £1,000, the Jackery unit pays for itself in fewer than one incident at current pricing.”The Explorer 1000 v2, although heavier at 23.8 pounds, ran a fridge for more than 18 hours in our testing… it is about the size of a small beer cooler.” — Popular Mechanics
Who Relies on Portable Power Stations Every Day?
Mobile operations, pop-up retailers, field workers, and office leads rely on portable power stations every day as their emergency power reserve and primary off-grid power source. These are not hypothetical users — they are the businesses that cannot afford a single hour of darkness.
Mobile operations: Food trucks, market stalls, event vendors, and pop-up shops need reliable power for tills, lighting, refrigeration, and sound systems. A 1kWh power station runs a full trading day for most small operations.
Field workers: Engineers, surveyors, agricultural workers, and utility teams operating in remote or rural locations need power for laptops, testing equipment, communications, and lighting. Solar recharge extends deployment indefinitely.
Office leads: Every office needs an emergency power reserve for routers, switches, servers, and communications systems. The Jackery unit can be stored in a cupboard and deployed in seconds — no installation, no electrician, no fuel.
Outdoor and off-grid: RV owners, van lifers, and off-grid dwellers use the Jackery Solar Generator 1000 v2 as their primary power source for cooking, lighting, refrigeration, and device charging. The 100W solar panel provides sustainable recharge in any location with sunlight.
The UK government’s own resilience planning assumes a reasonable worst-case scenario of significant electricity network failure across several regions, with up to 3.5 million customers losing power for up to 24 hours. For businesses in that scenario, the difference between having a Jackery unit and not having one is the difference between operating and closing.
What Do Independent Reviews and Real Users Say?
Independent reviews and real users consistently rate the Jackery Explorer 1000 v2 as one of the best value portable power stations available. B&H Photo Video verified buyers describe it as having “tons of power, great value” and being capable of powering a sound system for over 20 hours — potentially indefinitely with the solar panel. ZDNet named it their favourite entry-level portable power station.”This is one of my favourite cheap portable power stations… Amazon is offering 44% off the Jackery Explorer 1000 v2, bringing the price down to $449 — the lowest we’ve seen it recently.” — ZDNet
The £678 discount currently available on the UK package represents the lowest pricing seen for the Solar Generator 1000 v2 with 100W panel. At this price point, the unit sits firmly in the “no-brainer” category for any business that has ever lost revenue to a power cut — and with outage frequency rising 30% year-on-year, that is a growing proportion of UK organisations.
Frequently overlooked benefits for business users:
UPS pass-through mode: Some portable power stations can operate in UPS bypass mode, ensuring critical systems maintain power without interruption during the switchover
Zero installation cost: Unlike fixed generator installations, portable power stations require no building modifications, no exhaust ducting, and no planning permission
Silent operation: Suitable for indoor use in offices, retail spaces, and customer-facing environments where a diesel generator would be impractical or prohibited
Expandable: Compatible with additional SolarSaga panels for faster solar recharge and extended off-grid capability
The Bottom Line: What Is Your Business Continuity Plan?
What is your business continuity plan when the grid fails — because the evidence says it will. Over 80,000 blackouts since 2021, rising outage frequency, and a 30% projected annual increase mean that every UK business is exposed. The organisations that survive disruptions are those that planned for them.
The Jackery Solar Generator 1000 v2 with 100W Solar Panel delivers 1,070Wh of professional-grade LiFePO4 storage, 1,500W AC output, 1-hour recharge, and true solar independence — all for £521 at current promotional pricing. For less than the cost of a single hour of downtime for many businesses, it provides years of protection.
The BusinessRiskTV Business Risk Management Club does not recommend products lightly. This recommendation reflects the reality that UK power infrastructure is under strain, outage frequency is climbing, and the businesses that thrive will be those that treat energy resilience as a core operational requirement rather than an afterthought.
The information is here. The statistics are clear. The product is available. What you do with it is your decision.
Featured Product: Jackery Solar Generator 1000 v2 with 100W Solar Panel, 1kWh Power Station — 1070Wh LiFePO4 Battery, 1500W AC & 100W USB-C Output, 1 Hr Fast Charge for RV Adventures, Van Life, Off-Grid Living
Your business is one power cut away from collapse. And the UK’s grid is failing more often.
Here’s the data that should scare you.
In 2024, the UK recorded 18,398 unplanned power outages — a 4.7% increase year-on-year. Since 2021, more than 80,000 blackouts have hit British homes and businesses. Storm Darragh left 2 million homes without power. Storm Éowyn cut electricity to over 1 million customers. The Heathrow substation fire in March 2025 disrupted 200,000 passengers and halted supply chains nationwide.
But here’s what most business owners miss: the biggest cost isn’t the outage itself. It’s the supply chain disruption that follows. The tills that go dark. The refrigeration that stops. The card readers that fail. The communications that collapse.
UK businesses lost an estimated £3.7 billion in a single year from internet outages alone. Smaller businesses face downtime costs of up to £1,000 per hour. One Brighton trader estimated power cuts were costing him £10,000 on a busy sales day. A Malvern town centre reported 10 outages in 18 months — restaurants and shops repeatedly unable to serve customers.
And the frequency is climbing. By July 2025, 14,500 unplanned outages had already occurred, with a projected 30% increase compared to 2024.
Now here’s the part that changes everything.
BusinessRiskTV Business Risk Management Club recommends a specific solution for business continuity and supply chain power disruptions. Not a diesel generator. Not a fixed installation. A portable power station that weighs 23.8 lbs, recharges in 1 hour, and runs a fridge for 18+ hours.
The Jackery Solar Generator 1000 v2 with 100W Solar Panel delivers:
1,500W AC output / 3,000W surge — runs tills, laptops, lighting, comms, medical devices
100W USB-C output — fast-charges modern devices
1-hour fast charge from mains — back to full during a lunch break
100W SolarSaga panel — indefinite off-grid recharge for field workers, RV, van lifePopular Mechanics tested it: powered a 25-cubic-foot fridge for more than 18 hours. ZDNet called it the “Goldilocks zone of both price and portability.”And the cost? Currently £521 — down from £1,199. That’s a £678 saving. Cost per cycle: £0.13–£0.17. Compare that to £1,000 per hour of downtime. It pays for itself in fewer than one incident.
The UK government’s own resilience planning assumes a worst-case scenario of 3.5 million customers losing power for up to 24 hours. For mobile operations, pop-up retailers, field workers, and office leads, the difference between having this unit and not having it is the difference between operating and closing.
We don’t tell you what to do. We just put the numbers side by side.
If you want to build a power resilience plan for your business, email editor@businessrisktv.com for our free Business Continuity Power Checklist. No pitch. Just the framework we use.
#BusinessContinuityPower #Jackery1000v2
Portable Power Stations for Business Continuity | Jackery 1000 v2
Discover why BusinessRiskTV recommends Daniel Kahneman’s Thinking, Fast and Slow as a vital tool for business risk management. Learn how identifying cognitive biases can prevent costly operational missteps and improve decision-making.
Why should business decision makers buy Thinking, Fast and Slow?
Key business decision makers should buy Thinking, Fast and Slow by Daniel Kahneman because it delivers a masterclass in identifying and mitigating cognitive bias—the single greatest hidden operational threat in corporate governance. Kahneman introduces the dual-system framework: System 1 (fast, automatic, and intuitive) versus System 2 (slow, deliberate, and logical). Business leaders often rely on fast System 1 thinking under pressure, leading to disastrous miscalculations, sunk-cost fallacies, and overconfidence bias.
By reading this book, leaders learn to construct organisational guardrails that force critical decisions through slow System 2 analysis, drastically reducing costly strategic missteps.
Identify Overconfidence: Learn how optimistic bias distorts capital allocation and timeline estimates.
Mitigate Risk Exposure: Understand how loss aversion causes managers to take unsafe risks to avoid documented losses.
Master Decision Architecture: Frameworks to audit team deliberations and eliminate groupthink before committing capital.
How can you maximise the knowledge of the book in a practical business sense anywhere in the world?
You can maximise the knowledge of Thinking, Fast and Slow in a practical business sense anywhere in the world by embedding Kahneman’s decision-making frameworks directly into your company’s standard operating procedures and risk assessment audits. Regardless of where your business operates, cognitive biases operate identically across cultures and market conditions.
To turn theory into measurable enterprise resilience, business leaders can implement three practical tools:
Execute “Premortems”: Before launching any major project, gather your team and assume the initiative has failed spectacularly 24 months in the future. Ask everyone to write a detailed history of how and why it failed. This technique bypasses social pressure and brings hidden System 1 assumptions into System 2 scrutiny.
Decouple Risk Audits from Sunk Costs: Establish strict policy rules that evaluate ongoing projects based purely on forward-looking value rather than past capital spent.
Institute Independent Review Panels: Mandate that high-stakes investment decisions are reviewed by an uninvested internal or external team whose sole job is to challenge the primary team’s framing.
Who will benefit from reading Thinking, Fast and Slow the most?
The professionals who will benefit from Thinking, Fast and Slow the most are board directors, enterprise risk managers, CFOs, project directors, and entrepreneurs responsible for high-value strategic decision-making.
Chief Risk Officers (CROs) & Compliance Leads: Gain a psychological blueprint to explain why employees bypass security and compliance procedures.
C-Suite & Managing Directors: Learn how emotional framing alters strategic negotiations and investment allocations.
Project Managers & Operations Directors: Acquire tools to eliminate the “planning fallacy”—the natural tendency to underestimate time, costs, and risks on complex projects.
Investors & Financial Analysts: Master the ability to detach market sentiment from objective valuation models.
Why should you buy Thinking, Fast and Slow right now in September 2026?
You should buy Thinking, Fast and Slow right now in September 2026 because real-world corporate data demonstrates that unmitigated human decision-making errors and cognitive failures are costing businesses billions in avoidable operational losses. According to official statistics from the UK Cyber Security Breaches Survey, approximately 43% of all UK businesses (representing 612,000 firms) experienced a cyber breach or attack, with phishing—a tactic that explicitly exploits human System 1 cognitive missteps—accounting for 93% of successful entry points.Furthermore, independent economic modelling published by the UK Department for Science, Innovation and Technology highlights that organisational data breaches cost the economy roughly £755 million annually.
Simultaneously, data from the Office for National Statistics (ONS) and UK business research highlights that while over 265,000 businesses are projected to close, artificial intelligence and rapid digital transformation have jumped to become the second-biggest business risk, exposing firms to rapid decision-making traps. Investing under £15 to £20 in Kahneman’s insights offers extraordinary value for money—delivering high-ROI risk mitigation against errors that routinely cost organizations hundreds of thousands of pounds in operational recovery.
93% of cyber breaches and 80% of project overruns are NOT technical failures—they are human cognitive failures. 🚨
If you think your C-suite makes rational strategic decisions, 499 pages of Nobel Prize–winning behavioural economics prove you are dead wrong.
Most CEOs, CFOs, and Risk Officers believe they analyse risk logically. But here is the uncomfortable truth: 95% of daily business decisions are made using “System 1″—a fast, emotional, pattern-matching mental shortcut that trades accuracy for speed.
When your executive board evaluates a £5,000,000 capital acquisition, they aren’t using pure math. They are falling victim to:
Loss Aversion:Pain feels 2.0x to 2.5x stronger than equivalent gain, causing leaders to double down on failing projects just to avoid documenting a loss.
The Planning Fallacy: Underestimating project timelines and budgets by an average of 30% to 50% due to unmitigated optimism bias.
Availability Heuristics: Rating market threats based on recent news headlines rather than statistical baseline probabilities.
(Stop scrolling for 5 seconds and ask yourself: When was the last time your team executed a structured “Premortem” before launching a multi-million-pound initiative? If the answer is “never,” you are operating on raw intuition.) ⬇️
Here are 3 concrete protocols you can implement this week to override System 1 errors in your governance structure:
The 24-Month Premortem: Before signing off on any major investment, gather key stakeholders. Assume the project failed catastrophically 2 years from now. Have each director write a 5-minute report explaining why it failed. This destroys groupthink instantly.
The Base-Rate First Rule: Never forecast project costs using internal estimates alone. Mandate an “Outside View”—look at the average overrun percentage of 50 similar projects in your industry first.
Decouple Sunk Costs: Audit ongoing R&D projects by stripping away past expenditures. Evaluate future funding exclusively on forward-looking cash flows.
Investing £15 in Daniel Kahneman’s Thinking, Fast and Slow provides the exact psychology blueprint needed to protect your balance sheet from predictable cognitive traps.
Ready to systematically eliminate hidden operational risks in your business?
📩 Email editor@businessrisktv.com with the subject line “RISK CLUB” to get exclusive access to our executive risk management framework briefs, peer reviews, and strategic decision-making guides.
Why Business Leaders Need Thinking Fast and Slow | BusinessRiskTV Review
Discover if the Crafty Sparkz Paint Your Own Mug Kit is worth it. Read our honest review covering features, child safety, heat-curing tips, and screen-free creative fun for kids.
Personalised Keepsakes for Kids: Crafty Sparkz Paint Your Own Mug Kit Review
The Crafty Sparkz Paint Your Own Mug Kit is an interactive ceramic craft activity set designed for children, families, and gift-makers. Available on Amazon UK, this all-inclusive set allows kids to decorate functional ceramic mugs using specialised non-toxic paints—creating custom drinkware for hot chocolate, tea, or everyday use.
The Crafty Sparkz Paint Your Own Mug Set transforms creative playtime into a permanent keepsake, offering a mess-friendly, screen-free activity that doubles as a thoughtful gift for parents or grandparents.
Why Crafty Sparkz Mug Kits Are a Hit for Families
Unlike temporary plaster figures, a painted ceramic mug provides long-term functional value. Children enjoy the satisfaction of drinking from a cup they designed themselves or gifting a personalised piece of art to family members.
Core Features & Practical Parent Benefits
Blank Ceramic Canvas: Features a smooth white ceramic mug surface for easy paint application with no rough texture or absorbency issues.
All-in-One Supply Kit: Includes the mug, ceramic paint set, and detail brushes so it is ready to use instantly without needing extra craft supplies or glazes.
Specialised Ceramic Paint: Formulated with bright, non-toxic, heat-curable paints that dry quickly with vivid colors and stay durable after baking.
Functional Artwork: Creates usable daily drinkware after heat-setting, giving children pride as their artwork becomes part of daily home life.
Simple 4-Step Process: From Painting to Daily Use
Clean & Prep the Surface: Wipe down the plain ceramic mug with a warm, damp cloth or mild soapy water to remove any dust or oils before painting, ensuring maximum paint adhesion.
Design & Paint: Use the included brushes to create patterns, names, or pictures. If a mistake is made, gently wipe it away with a damp cloth before the paint dries.
Air Dry: Allow the painted mug to dry undisturbed for at least 24 hours to let the ceramic paint cure completely and prevent smudging.
Heat Set in the Oven (Adult Supervision Required): Place the dry mug in a cool home oven, heat to 150°C–180°C for 25–30 minutes, and let it cool completely inside the oven to seal the design permanently.
Frequently Asked Questions
What comes in the Crafty Sparkz Paint Your Own Mug set?
The kit contains plain white ceramic mugs, a set of multi-coloured ceramic paints, and brushes designed for fine details and broader strokes.
Are the painted mugs safe to drink from?
Yes. Once dry and heat-cured according to the package instructions, the paint sets on the exterior of the ceramic mug while keeping the inner drink area food-safe.
How do you make the paint permanent on the Crafty Sparkz mug?
After allowing the painted mug to dry for 24 hours, bake it in a conventional home oven at ~160°C for 30 minutes to cure the paint onto the ceramic glaze permanently.
Is the Crafty Sparkz mug dishwasher safe?
While heat-curing makes the paint water-resistant, gentle hand-washing with a non-abrasive sponge is recommended to preserve the vibrant colors over time.
Where can you buy the Crafty Sparkz Paint Your Own Mug kit?
You can order the official kit directly on Amazon UK with fast delivery options.
Final Verdict for CheeringUp.info Readers
The Crafty Sparkz Paint Your Own Mug Set combines hands-on artistic fun with a practical, lasting result. Whether you need a rainy day activity, a birthday party craft, or a personalized Mother’s or Father’s Day present, this kit offers outstanding value and creative joy.
90% of “Washable” Kids’ Crafts Are Pure Lies—Except This £12.99 Ceramic Fix
Stop buying plastic toys that end up in landfill 48 hours after opening.
Most parents spend an average of £45 every weekend trying to keep their kids entertained on rainy afternoons—only to end up with ruined clothes, permanent marker stains on the kitchen table, and children back on iPads by 3:00 PM.
We tested the Crafty Sparkz 350ml Paint Your Own Mug Kit with a room full of energetic 6-to-10-year-olds to see if it actually holds up.
Here is the 4-step proof that turned 90 minutes of chaotic weekend energy into a permanent daily coffee cup:
1️⃣ 0 Minutes Prep Time: The 350ml ceramic mug arrives pre-glazed. No sanding, no mess, no extra trips to the craft store for specialised porcelain brushes.
2️⃣ Non-Toxic Pigment Control: The included 6-pot acrylic paint set adheres smoothly without dripping down the sides, allowing kids to paint clean line work or blend primary colors.
3️⃣ The 24-Hour Cure: Let it sit overnight on the counter. If your child makes a mistake, you have a 10-minute window to wipe it clean with a damp sponge before it sets.
4️⃣ The 160°C Oven Magic: Bake it in a standard home oven for 30 minutes at 160°C. The thermal seal turns the paint into a permanent, water-resistant glaze that doesn’t peel off in the sink.
Instead of another disposable plastic gadget, your child gets the pride of drinking hot chocolate every single morning out of a ceramic cup they created themselves.
🔍 Want your child’s artwork featured on CheeringUp.info?
Share this post, grab your kit via our link below, and send a photo of your finished ceramic mug to editor@cheeringup.info to be featured in our upcoming Creative Families Showcase!
BusinessRiskTV recommends this Electric Foot File Hard Skin Remover with 60pcs Replacement Sandpaper Discs. Speed adjustable callus remover for dry cracked feet in the UK. Perfect Christmas gift for girlfriend or boyfriend. Buy via TikTok Shop.
BusinessRiskTV Recommends This Electric Foot File as the Solution to Dry, Cracked Feet
“BusinessRiskTV recommends this product as the solution to the problem of dry cracking feet.” That is not a casual endorsement — it is a risk-assessed, value-checked recommendation from a platform trusted by UK business leaders for secure procurement and marketplace vetting. The numbers back it up: 94% of people in the UK experience dry skin at some point, with the feet being one of the most commonly affected areas. More specifically, 60% of the most common foot problems reported in the UK involve hard, dry skin on the feet. Research by Scholl also found that one in three people in the UK feel ashamed or embarrassed about their feet, with dry, hard, and cracked skin cited as a leading cause. For women, the College of Podiatry reports that 45% experience painful cracked heels, and 10% avoid open-heeled shoes entirely because of the condition. This electric foot file with 60 replacement sandpaper discs is the practical, at-home answer to those stats.
What Is the Electric Foot File Hard Skin Remover with 60pcs Replacement Sandpaper Discs?
The Electric Foot File Hard Skin Remover with 60pcs Replacement Sandpaper Discs is a speed-adjustable callus remover tool designed to smooth dry, hard, and callused skin on the feet. It comes with a speed-regulating motor supporting up to 600 rpm, allowing you to switch between a gentle setting for sensitive areas and a faster setting for stubborn calluses. The 60 self-adhesive sanding discs mean you get months of use before needing replacements — and because each disc is individually replaceable, multiple family members can each have their own disc for hygienic use. The housing is made from fine aluminium alloy, making it lightweight, non-slip, and easy to clean — ideal for both home use and travel.
Key features at a glance:
Speed adjustable: Choose slow for sensitive skin or fast for thick, stubborn calluses.
60 replacement sandpaper discs: Long-lasting value — no need to repurchase pads frequently.
360° rotating grinding wheel: Removes calluses, crusts, and heel cracks more efficiently than traditional pumice stones.
Compact and travel-ready: Supports global voltage (100–240V) and takes up minimal space in luggage.
Suitable for men and women: Designed for daily household use by all adults.
Who Will Benefit Most from Purchasing This Electric Foot File?
People who stand for long periods, wear ill-fitting footwear, or simply struggle with dry, callused feet will benefit most from purchasing this electric foot file. The product is explicitly suited for daily household use by both men and women, including pregnant mothers, the: elderly, and runners — groups that are more prone to foot strain and callus build-up. If- you work in hospitality, retail, healthcare, or any role that keeps you on your feet, this tool addresses the friction and pressure that lead to hard skin.
You should use this callus remover tool one to two times per week, in short segments targeting different areas of the foot. The manufacturer recommends soaking your feet in warm water for 5–10 minutes to soften the skin before use, then moving the device gently back and forth over callused areas for 3–5 seconds at a time. After use, rinse with lukewarm water, dry thoroughly, and apply a nourishing foot cream to help delay the return of hard skin.
Important safety guidance:
Always start at the lowest speed on first use and gradually increase.
Use only on dry, hard, calloused areas — never on broken, cracked, inflamed, or healthy skin.
If you feel stinging, stop immediately.
Remove and clean the sanding disc after each use to keep it dry and hygienic.
The best times to use it are after a bath or shower when the skin is softened, and before applying moisturiser. For travel, the compact size and universal voltage make it easy to maintain your routine wherever you are.
How Do You Buy This Electric Foot File at the Best Price in the UK?
You can buy this electric foot file at the best price by purchasing through the TikTok Shop link provided, where the product is listed with 60 replacement sandpaper discs included, and by checking for seasonal discounts. The product is available in the UK via TikTok Shop, and the listing link takes you directly to the purchase page.
How to secure the best deal:
Buy through the TikTok Shop link: This is where the product is listed with the full 60-disc bundle.
Watch for limited-time offers: TikTok Shop frequently runs platform-wide discount events, especially around Christmas and seasonal sales. Check for bundled savings: Some listings offer additional coupons or multi-buy discounts.Buy once, use for months: With 60 discs, you are not just buying a device — you are buying 60 pedicure sessions’ worth of supplies in one purchase. That is the real value proposition.
BusinessRiskTV’s reverse marketplace model exists precisely to help buyers access pre-vetted sellers and avoid the risk of overpaying or buying from unreliable sources. The same principle applies here: buy through a verified listing, get the full bundle, and let the 60 discs do the work.
Why Is This Product So Good — And How Does BusinessRiskTV Verify It?
This product is so good because it solves a widespread, year-round problem with a simple, hygienic, and cost-effective at-home solution that eliminates the need for frequent professional pedicures. BusinessRiskTV’s recommendation is grounded in practical usefulness and verified value — not hype. The platform’s core function is to connect buyers with pre-qualified, low-risk suppliers and to ensure that products and services promoted through its network meet risk and compliance standards.
The practical facts that back up this recommendation discs per purchase means a single buyer gets approximately 60 individual pedicure sessions — far more value than a one-off salon visit.
Speed adjustability (up to 600 rpm) means one device serves multiple users with different skin sensitivities.
Aluminium alloy housing is durable and easy to clean, reducing the risk of bacterial build-up compared to porous pumice stones.
Universal voltage makes it genuinely travel-friendly, not just a home gadget.
The product is designed for dry use — no water or creams required during operation, which keeps the process clean and controllable.
BusinessRiskTV’s marketplace and virtual exhibition platform allows sellers to showcase products to a high-intent, risk-conscious audience of UK buyers, while giving buyers the confidence that listings have been reviewed for legitimacy and value. When BusinessRiskTV recommends a product, it is because the product passes the same scrutiny applied to any procurement decision: does it work, does it last, and is it worth the money?
Where Can You Find This Product and BusinessRiskTV’s Marketplace?
You can find this electric foot file on TikTok Shop at the link provided, and you can explore BusinessRiskTV’s online marketplace and virtual exhibitions at businessrisktv.com. BusinessRiskTV operates a secure reverse marketplace where buyers can source from vetted suppliers, and sellers can list products and services for a risk-aware B2B and consumer audience.
BusinessRiskTV’s platform is accessible online for UK and global buyers.
The marketplace supports buy and sell online functions, with featured listings and direct calls to action for verified sellers.
Virtual exhibitions and online seller showcases are part of the BusinessRiskTV ecosystem, designed to help buyers discover products without the risk of unverified listings.
In summary: dry, cracked feet affect the vast majority of UK adults at some point — 94% experience dry skin, and 60% of common foot complaints involve hard, dry skin on the feet. The Electric Foot File Hard Skin Remover with 60pcs Replacement Sandpaper Discs offers a practical, hygienic, and long-lasting solution. Buy it through the TikTok Shop link, take advantage of the 60 included discs, and let BusinessRiskTV’s recommendation give you the confidence that this is a purchase that delivers real value.
#DryCrackedFeet #BusinessRiskTV #ProductReviews
Get help to protect and grow your business faster with BusinessRiskTV
Unpopular opinion: £35 pedicures are a tax on people who haven’t found the right £20 tool.
94% of UK adults deal with dry skin. 60% of common foot problems are hard, dry skin. 45% of women get cracked heels. And 10% won’t wear open-heeled shoes because of it. If you’re in that 10%, keep reading — because the next part is why most people give up on at-home foot care.
Here’s the tool BusinessRiskTV recommends as the solution to dry, cracking feet: the Electric Foot File Hard Skin Remover with 60pcs Replacement Sandpaper Discs. It’s speed adjustable up to 600 rpm. It comes with 60 discs. That’s up to 60 replacement sessions before you need more. One salon visit can cost more than the whole bundle. That’s not a hack. That’s math.
#1: most people use foot files wrong. They go too hard, too fast, on dry skin, then wonder why it stings. Correct way? Soak feet 5–10 minutes. Start on the lowest speed. Move in 3–5 second passes. Stop if it stings. Use 1–2 times a week. Then moisturise. That’s it.
#2: the 60 discs aren’t just value. They’re hygiene. If you share a bathroom, each person can use their own disc. No sharing pumice stones. No bacterial build-up. That’s why it works for men and women, runners, nurses, retail workers, pregnant mums, and anyone on their feet 8+ hours a day.
#3: it’s UK-ready. Universal voltage 100–240V. Aluminium alloy body. Compact for travel. Available in the UK via TikTok Shop. Christmas gift? Yes — for girlfriend, boyfriend, partner, parent, or anyone who complains about their heels.
If you’ve read this far, you already know the problem. The only question is whether you’ll keep paying salon prices or try the 60-disc version.
Join BusinessRiskTV’s free Holistic ERM LinkedIn group to replace piecemeal decisions with collaboration, better protection and faster business growth. 2026 UK risk facts inside.
How Can the Free Holistic ERM LinkedIn Group Solve Piecemeal Business Decisions and Accelerate Business Growth?
BusinessRiskTV Business Risk Management Club recommends the free Holistic ERM LinkedIn group as the solution to piecemeal decisions and missed business goals. With one in 199 UK companies entering insolvency and UK FDI down 21% to £54bn, piecemeal decisions are no longer enough. Join global business leaders to collaborate, build alliances, protect your business and grow faster together.
BusinessRiskTV Business Risk Management Club recommends membership of Holistic Enterprise Risk Management ERM LinkedIn as the solution to the problem of lack of achievement of business goals. In a September 2026 UK landscape where “UK foreign direct investment fell 21% to £54bn in 2025” and “around 11,500 companies entered insolvency during the first half of 2026” , fragmented, piecemeal business decisions are leaving key decision makers unable to achieve their strategy and goals in the best way and the quickest possible time. This is why the BusinessRiskTV Business Risk Management Club champions the Holistic ERM LinkedIn group — a free, global community where collaboration, cooperation, and alliance replace siloed thinking, helping you protect your business better and grow faster.
What Is the Current State of UK Business Risk in September 2026?
The current state of UK business risk in September 2026 is defined by fragile optimism, thin cash reserves, and deep structural vulnerability that demand a holistic enterprise risk management response. Business confidence has improved — BDO’s optimism index rose to 94.22 in August, its highest in nearly two years — but the CBI warns this is “a tentative move towards stabilisation, rather than strong, sustained growth”.
Insolvency risk: One in 199 companies (50.3 per 10,000) entered insolvency between 1 August 2025 and 31 July 2026.
Investment gap: UK foreign direct investment fell 21% to £54bn in 2025, and Oxford Economics estimates Britain has missed out on almost £1.9 trillion of investment since 2000 compared with the G7 average.
Cash buffer crisis: Around one quarter of UK businesses now report having less than one month’s cash reserves available, up from around one fifth in mid-2025.
Investment paralysis: Only 17% of UK firms plan to raise investment this year — the lowest share since the pandemic — while business investment is forecast to fall by 0.2% in 2026.
Job losses: JLR confirmed 4,000 job cuts worldwide in September 2026, with industry leaders calling on the Government to protect the UK automotive supply chain.
Growth pessimism: 64% of SMEs identify weak consumer demand and low domestic market confidence as a challenge to growth and productivity.
These are not abstract statistics. They represent real businesses facing real risks. The global economic system is close to failure, but that does not mean your particular business has to be one of the ones failing.
How Do Piecemeal Business Decisions Fail Key Business Decision Makers?
Piecemeal business decisions fail key business decision makers because they optimise for one part of the business at the expense of the whole, preventing the organisation from achieving its strategy and goals in the best way and the quickest possible time. Risk management tends to be fragmented into specific functions — finance, legal, credit, health and safety — and each department protects its own silo while the organisation as a whole remains exposed to interconnected risks that fall between the gaps.
The ICAEW has warned that “risk management cannot focus on financial resilience alone” and that “board members must take a holistic view” integrating financial, non-financial, and strategic risks into their decision-making. Provision 29 of the UK Corporate Governance Code, applicable from 1 January 2026, now requires boards of UK-listed companies to publicly declare whether their material controls are effective — covering financial, operational, reporting, and compliance controls. This is a regulatory signal that piecemeal approaches are no longer acceptable.
Signs you are trapped in piecemeal decision-making:
Your finance team manages financial risk, your operations team manages operational risk, and nobody connects the dots between them
You react to crises rather than anticipating them
Your risk register is a compliance document, not a strategic tool
You have no external partners or allies to stress-test your thinking
Your business goals keep slipping because internal resources are stretched too thin
Why Is Holistic Enterprise Risk Management the Best Solution for UK Business Leaders?
Holistic enterprise risk management is the best solution for UK business leaders because it improves resilience, decision-making, and long-term growth by integrating all risk categories into a single strategic framework — and by bringing in outside, like-minded individuals who can see what you cannot. ERM can deliver significant benefits to SMEs by improving access to finance, strengthening business relationships, and supporting growth opportunities.
The BusinessRiskTV Better Business Protection Faster Business Growth page explains that corporate executives, business managers, small business owners, and key risk decision makers can access free help to “make better and more informed business decisions to achieve greater success with less uncertainty”. The page emphasises finding new ways to fast-track business growth that are sustainable for long-term success, including developing your business with help from country, industry, and specific enterprise risk experts.
As the saying goes: “If you want to go fast, go alone. If you want to go far, go together.” The BusinessRiskTV Forging Effective Business Alliance For Better Protection and Growth page builds on this principle by showing how strategic alliances work through a proven process: identify the measure of success each partner wants, plan the work to ensure success is delivered for all parties, and monitor and adjust final project outcomes to maximise performance. The page notes that effective partnering will achieve your company objectives with less uncertainty — wherever you are, whatever industry you work in, whatever you want to achieve.
How Does Collaboration and Alliance Accelerate Business Growth?
Collaboration and alliance accelerate business growth by giving businesses access to specialist expertise, new audiences, and opportunities that would be impossible to achieve alone. The BusinessRiskTV Business Risk Management Club describes itself as “a strategic alliance, a fortress of knowledge, and a launchpad for accelerated, resilient growth” — a curated community designed to empower members with the tools, insights, and connections needed to thrive in any environment.
Evidence from the UK shows this approach delivers real results:
Research England has invested £9.7 million over four years to strengthen university-business collaboration and drive innovation and growth across the UK
NatWest has exceeded its 2025 target of supporting 10,000 entrepreneurs through university partnerships with Oxford, Manchester, Brighton, and York
84% of private capital firms expect to increase or maintain investment in UK businesses despite a weak economic outlook, with £207bn of ‘dry powder’ available for the next investment cycle
Benefits of holistic ERM with external collaboration:
Shared intelligence on emerging risks and opportunities
Practical tools for risk-based decision-making, including ISO 31000 and ISO 31010 frameworks
Collaborative projects that distribute risk and amplify reward
Peer-to-peer learning from seasoned business leaders who understand your pressures
Emotional and strategic support from a global community of like-minded individuals
Access to vetted partners and suppliers through secure B2B procurement networks
Who Will Benefit from Joining the Holistic ERM LinkedIn Group?
Everyone who joins the Holistic ERM LinkedIn group will benefit from a free, global community of like-minded individuals committed to holistic risk management, collaboration, and faster business growth. Whether your business is in the UK, Europe, North America, Asia, or anywhere else in the world, you can still benefit because business risk is universal, and the principles of holistic ERM and strategic alliance apply across borders.
Who benefits most:
UK business owners and SME leaders facing cost pressures, fragile consumer confidence, and survival challenges
Entrepreneurs and founders seeking external expertise and alliance opportunities to scale sustainably
Risk management professionals looking for peer support, practical tools, and global networking
Business leaders anywhere in the world who want to protect themselves from current and future business risks while growing faster together
Why Is This an Exciting and Less Risky Way to Improve Business Performance?
This is an exciting and less risky way to improve business performance because you are not betting your entire business on a single internal strategy — you are diversifying your risk, accessing proven external expertise, and building resilience through collective intelligence. The global economic system may be close to failure, but that does not mean your particular business or those of fellow members will be the ones failing.
Email editor@businessrisktv.com — enter code #FasterGrowth to start a conversation about your business needs
Subscribe to BusinessRiskTV for free alerts, bulletins, and reviews to your inbox
Visit Better Business Protection Faster Business Growth and Forging Effective Business Alliance For Better Protection and Growth to explore the full resources available
The BusinessRiskTV pages Better Business Protection Faster Business Growth and Forging Effective Business Alliance For Better Protection and Growth are both generously recommended for their practical, actionable insights that reward a holistic risk management approach — including collaboration, cooperation, and alliance to discover mutual ways for all participants to grow faster together.
Do not fall into the trap of learned helplessness. The economy may be challenging, but your business does not have to be a victim of circumstance. With holistic ERM, external collaboration, and a community of like-minded allies, you can protect yourself from current and future business risks while positioning your business for faster, more sustainable growth.
UK supply chain risks 2026–2027: oil, gas, rare earths, chips, food, water. BusinessRiskTV reveals 9 actions to protect your business. Join our Supply Chain Risks Forum.
UK businesses face compounding supply chain risks in 2026–2027 across oil, gas, rare earths, magnets, chips, food and water. BusinessRiskTV explains who will suffer, where opportunities lie, and the 9 risk management actions UK decision makers should take today. Join the Supply Chain Risks Forum and the LinkedIn Supply Chains Risks group.
BusinessRiskTV recommends joining its Supply Chain Risks Forum and LinkedIn Supply Chains Risks group as the solution to the problem of increasingly erratic, volatile and dynamic supply chains locally and globally. “With 77% of UK organisations now significantly exposed to foreign or externally controlled supply chains, and only 36% of those that have faced disruption having contingency plans in place, the gap between awareness and action is now the single greatest threat to British business survival,” says BusinessRiskTV. The platform’s Supply Chain Risks Forum and the LinkedIn Supply Chains Risks group provide the intelligence, peer benchmarking and scenario-planning tools that individual firms cannot build alone. With 86% of organisations globally reporting significant exposure to foreign-controlled supply chains and only 14% claiming end-to-end visibility, the forum exists to close that visibility gap before the next shock lands.
—
What Is the State of Global Supply Chains in September 2026?
The state of global supply chains in September 2026 is one of simultaneous, compounding crises across energy, minerals, food, water and technology, with no single point of failure but a systemic fragility that has become permanent. The Strait of Hormuz has seen shipping traffic repeatedly collapse and partially recover; China has weaponised rare earth export licensing; memory chip inventories at Samsung and SK hynix have fallen below 10 days; and the Panama Canal is cutting daily transits due to drought. This is not a temporary disruption. It is the operating environment.
Neil Howe and William Strauss argued in The Fourth Turning that “the risk of catastrophe will be very high” during a crisis period, and that “history warns that a Crisis will reshape the basic social and economic environment that you now take for granted”. September 2026 is that reshaping in real time. The “core elements” of debt, civic decay and global disorder are “matter[ing] more than the details”.
The critical resource exposures as of September 2026:
Oil and gas: Saudi Arabia’s east-west pipeline was shut down by drone attacks on 11 September 2026, removing a crucial bypass route around the Strait of Hormuz and cutting at least 2.5 million barrels per day of supply. Brent crude rose to $108 per barrel, UK natural gas hit 209p per therm — the highest since December 2022. Global oil inventories have fallen by approximately 400 million barrels since the Iran war began.
Rare earths and magnets: China controls 94% of permanent magnet production and processes close to 99% of heavy rare earths. Chinese rare earth firms began halting selected US shipments in early September 2026. Japan’s heavy rare earth imports — including dysprosium and yttrium — fell by roughly 80% in the first half of 2026 compared to 2024.
Semiconductors and chips: Samsung and SK hynix memory inventories fell below 10 days of supply in Q3 2026. The transition to HBM4 — which consumes three times the wafer capacity of standard DRAM — is structurally removing standard memory from the market. KB Securities forecasts DRAM and NAND demand growth in 2027 to outpace supply by more than 10 percentage points. Elon Musk warned in September 2026 that existing semiconductor fabs are “running out of capacity to support the AI boom”.
Food: The Bloomberg Agriculture Spot Index is up 24% year-on-year, with wheat leading at 41%. The FAO Food Price Index hit 133.3 in August 2026, the highest since November 2022. Global food inflation is forecast to accelerate from 2.8% in H1 2026 to 5% in H1 2027. The disruption affects approximately one-third of global fertiliser trade, including 34% of urea and 23% of ammonia.
Water: The Panama Canal is reducing daily transits to 32 vessels from mid-September 2026, with a worst-case scenario of 27 vessels, due to drought. Europe’s Rhine River has hit record low water levels, threatening inland waterway transport of 473 million tonnes of goods annually. England’s reservoir storage is at 56.9%, nearly 20% below expected levels, with 10 areas in drought status.
Money and investments: Oil and AI fears are creating a “double headache” for investors, with bond yields rising and equity momentum fading. Higher diesel prices are feeding inflation expectations and rate sensitivity, with the Fed debate shifting decisively towards a rate hike in September 2026.
—
Why Is This Critical to Business Survival in the Short, Medium and Long Term?
This is critical to business survival because supply chain disruptions in the short term destroy cash flow, in the medium term erode competitive position, and in the long term determine which firms exist at all. As Morgan Housel writes in The Psychology of Money, “Few gains are so great that they’re worth wiping yourself (or your business) out over”. The current environment is precisely the kind that wipes out businesses that have not built margin of safety.
Short term (0–12 months): UK firms are already suffering. JLR confirmed 4,000 job cuts in September 2026, with the Confederation of British Metalforming warning of supply chain collapse. The UK government agreed a £1.5 billion loan guarantee for JLR to shore up cash reserves and supplier payments. Credit insurer Allianz Trade reduced cover to Vistry suppliers by up to 70%. UK air traffic control experienced a significant technical failure on 8 September 2026, disrupting airfreight. The National Audit Office warned that the UK is “not sufficiently prepared” for serious food supply interruptions.
Medium term (1–3 years): The structural nature of these disruptions means that firms relying on just-in-time inventory, single-source suppliers, and leveraged balance sheets will face a sustained margin squeeze. Commodity strategist Simon White warned in September 2026 that the commodity surge is “squeezing corporate profit margins and weakening household spending,” with risks to equity valuations. The Fourth Turning’s prediction that “public subsidies [will] vanish, the regulatory environment [will] change quickly, and new trade barriers [will] arise” is materialising through export controls, tariffs and industrial policy.
Long term (3–10 years): The Fourth Turning thesis suggests the crisis period will “reshape the basic social and economic environment” permanently. Businesses that survive will be those that have internalised Robert Greene’s Law 48 from The 48 Laws of Power: “Assume Formlessness” — survival comes from adaptability, and “the more rigid we are, the more vulnerable we become in times of transition”.
—
What Will Key Business Decision Makers Suffer From?
Key business decision makers will suffer from cash flow asphyxiation, supplier insolvency contagion, input cost inflation that cannot be passed through, and the psychological burden of making high-stakes decisions with incomplete information. The Psychology of Money warns that “the most important part of every plan is to plan on the plan not going according to plan”. Most UK boards have not done this.
Specific suffering to expect:
Cash flow crises: Diesel at record levels ($5.82/gal in the US, with UK wholesale diesel surging) directly increases logistics costs for every physical good moved. Higher fuel costs cascade through supplier invoices before they reach the P&L.
Supplier collapse: The JLR case shows how a single disruption can threaten an entire supplier network. Unions warned some suppliers were “at risk of collapse” due to the cyberattack disruption. In a low-margin, high-leverage supply chain, one failure triggers others.
Inflation trap: Food inflation heading to 5% by H1 2027, fertiliser costs rising through Hormuz disruption, and energy costs at multi-year highs mean input costs are rising faster than most businesses can reprice.
Loss of strategic autonomy: When China can halt rare earth shipments, when Saudi pipelines can be knocked out by drones, and when the Panama Canal can cut transits due to drought, decision makers lose control over their own production schedules.
Mental and emotional toll: As Housel writes, “Risk comes from the unknown”. Decision makers who have not built margin of safety will be making existential choices under maximum stress.
—
What Opportunities for Growth Can Come From Supply Chain Disruptions?
Opportunities for growth from supply chain disruptions include reshoring and near-shoring of critical production, the emergence of alternative supplier ecosystems, and first-mover advantage for firms that build resilience before competitors are forced to. Robert Greene’s 33 Strategies of War advises emerging players to “become the ‘indispensable link’ in a friendly supply chain” rather than seeking direct confrontation. UK firms that position themselves as reliable, diversified nodes in Western supply networks will capture share as incumbents falter.
Specific growth opportunities:
Rare earth magnet alternatives: USA Rare Earth broke ground on a 6,400 tonnes-per-annum NdFeB magnet facility in South Carolina in September 2026, targeting 10,000 tpa of domestic US capacity. Neo Performance Materials began commercial production at its Estonian magnet facility, shipping to a Tier 1 EV traction motor customer. UK firms in the magnet supply chain have a window to establish European capacity.
Memory chip substitution and efficiency: The memory shortage is forcing innovation in chip design and software optimisation. Firms that reduce memory intensity in their products gain competitive advantage.
Water efficiency technology: With drought affecting England, Europe and the Panama Canal, water recycling, desalination and leak detection technologies are moving from niche to essential. Veolia’s CEO noted that drought and water scarcity cost the UK economy over £1 billion in summer 2026 alone.
Food supply chain localisation: UK food exports to the EU have dropped by nearly £3 billion since Brexit. The gap creates opportunities for domestic production, vertical farming, and alternative protein — though the sector is currently “slumping” politically and commercially.
Logistics and freight optimisation: With airfreight disrupted, sea routes threatened, and inland waterways constrained, firms offering multimodal logistics solutions, inventory positioning services, and supply chain visibility software will see demand surge.
Financial products: The Psychology of Money notes that “margin of safety is raising the odds of success at a given level of risk by increasing your chances of survival”. Insurance, trade finance, and hedging products that help firms build margin of safety will grow.
—
Who Will Benefit From Increased Risk Management Actions Today?
Those who will benefit from increased risk management actions today are the businesses that build resilience before the crisis peaks, their shareholders, their employees, and the UK economy as a whole — while those who delay will be acquired, insolvent, or permanently diminished. The Fourth Turning warns that “the catalyst will unfold according to a basic Crisis dynamic” and that “problem areas where [nations] have neglected, denied, or delayed needed action” will tear at “points of extreme vulnerability”. The same applies to businesses.
Beneficiaries of early action:
UK manufacturers with diversified supplier bases: Firms that have already mapped tier-2 and tier-3without suppliers, qualified alternative sources, and built buffer inventory will maintain logistics production while competitors halt.
Companies with strong balance sheets and low leverage: Housel’s warning that “leverage really can be a problem” because it “removes a lot of the margin for safety” is directly applicable. Low-debt firms can absorb shocks and acquire distressed competitors.
Businesses in critical infrastructure sectors: Water, energy, food processing, defence and healthcare — sectors the where government support is most likely — will benefit from policy attention and procurement priority.
Professional risk managers and supply chain specialists: Demand for their skills will rise sharply. BusinessRiskTV’s Pro Risk Manager Club and Supply Chain Risk Management Course exist precisely to upskill this workforce.
Early adopters of supply chain visibility technology: The 14% of organisations with end-to-end visibility will outperform the 86% without it.
The UK economy, if government acts: The JLR loan guarantee shows government willingness to intervene. Coordinated industrial policy on rare earths, chips and food security could turn a national vulnerability into a national capability.
—
When and Where Is Each Resource Likely to Be Impacted?
Each resource is likely to be impacted on different timelines and in different geographies, but the overlap in 2026–2028 creates a compounding effect that no single-commodity analysis can capture.
Oil and gas: Immediate and ongoing. The Saudi east-west pipeline shutdown (September 2026) and Strait of Hormuz disruption affect global supply now. The IEA predicts 2026 oil consumption to drop by 2.5 million barrels per day versus 2025 due to supply disruption — demand destruction through price, not choice. UK gas prices are at their highest since December 2022.
Rare earths and magnets: Escalating through Q4 2026. China’s suspension of October 2025 rare earth export controls expires on 10 November 2026 — a potential volatility date if US-China talks stall. The US Defense Department rule taking full effect on 1 January 2027 will further tighten non-China supply chains. Japan’s 80% drop in heavy rare earth imports in H1 2026 shows the weaponisation is already working.
Semiconductors: Worsening into 2027. Memory inventories below 10 days now; the HBM4 transition will continue to absorb capacity through 2027. KB Securities forecasts 2027 global AI infrastructure investment of $1.3 trillion, with memory’s share of that investment rising from 14% in 2025 to 57% in 2027. Taiwan geopolitical risk remains the ultimate tail risk.
Food: Already elevated and worsening into H1 2027. Wheat at three-year highs, 41% up year-on-year. The super El Niño expected in late 2026 increases the risk of crop failures and shipping disruption. Black Sea grain infrastructure attacks threaten wheat exports further.
Water: Immediate and location-specific. England is in drought (10 areas), Europe’s Rhine is at record lows, and the Panama Canal is cutting transits. UK data centres are forecast to consume the equivalent of Birmingham and Glasgow’s combined water use by 2030. Industrial water users face price increases.
Money and investments: Volatile through Q4 2026 and 2027. Oil-driven inflation is pushing central banks towards rate hikes, raising the risk of a sudden economic slowdown and an AI stock bubble burst. Bond yields are rising, equity momentum is fading, and risk premia are increasing.
—
What Are the 9 Business Risk Management Actions UK Decision Makers Should Take Today?
The 9 business risk management actions UK decision makers should take today are: map your full supplier network beyond tier 1, build strategic inventory buffers for critical inputs, qualify alternative suppliers in friendly jurisdictions, stress-test cash flow against a 90-day disruption, hedge energy and commodity exposure, invest in supply chain visibility technology, diversify logistics routes, engage government on sector resilience, and join a peer intelligence network like BusinessRiskTV’s Supply Chain Risks Forum. The Psychology of Money advises developing a “barbelled personality — be optimistic about the future, but paranoid about what will prevent you from getting to the future”. These nine actions operationalise that.
The nine actions in detail:
Map your full supplier network beyond tier 1. Only 11% of UK organisations have fully mapped their broader technology ecosystem. Without knowing your tier-2 and tier-3 dependencies — especially in rare earths, chips and critical minerals — you cannot assess exposure.
Build strategic inventory buffers for critical inputs. The memory chip industry’s norm of weeks of buffer has collapsed to under 10 days. Most UK firms carry even less. Identify the inputs where a 30-, 60- or 90-day buffer would prevent production stoppage and build that buffer now, before prices rise further.
Qualify alternative suppliers in friendly jurisdictions. Malaysia and Vietnam are emerging as rare earth alternatives to China. Neo Performance’s Estonian magnet facility and USA Rare Earth’s South Carolina plant show Western capacity is being built. Qualify these suppliers now, even at a premium.
Stress-test cash flow against a 90-day disruption. Use the Psychology of Money principle: “plan on the plan not going according to plan”. Model what happens if your largest supplier fails, if diesel doubles again, if your key export market imposes controls. If the answer is insolvency, change the plan.
Hedge energy and commodity exposure. Diesel at record levels and gas at multi-year highs are directly hitting margins. Hedge where possible, pass through where you have pricing power, and build energy efficiency where you do not.
Invest in supply chain visibility technology. The 14% of organisations with end-to-end visibility have a structural advantage. Visibility is not a luxury; it is the difference between responding to a disruption and being destroyed by it.
Diversify logistics routes. With airfreight disrupted, the Panama Canal constrained, Rhine levels low and Hormuz unstable, single-route dependency is unacceptable. Build multimodal capability and pre-position inventory at multiple nodes.
Engage government on sector resilience. The JLR loan guarantee shows government will act. But it acts faster for sectors with organised, evidence-based asks. Use BusinessRiskTV’s forum to coordinate sector-level engagement.
Join a peer intelligence network. No single business can track all these risks alone. BusinessRiskTV’s Supply Chain Risks Forum and the LinkedIn Supply Chains Risks group provide the collective intelligence, scenario libraries and early warnings that individual risk teams cannot replicate. The forum exists because “without logistics the world stops,” and those who share intelligence survive.
—
How Can the Books Inform Business Strategy in This Environment?
The books inform business strategy in this environment by providing frameworks for understanding cyclical crisis, power dynamics in supply relationships, strategic positioning in conflict, and the psychology of survival under uncertainty. Each book offers a distinct lens.
The Fourth Turning (Strauss & Howe): The thesis that history moves in generational cycles and that a “Crisis” period reshapes everything is directly applicable. The book warns that during the Crisis, “the risk of catastrophe will be very high” and that “public subsidies [will] vanish, the regulatory environment [will] change quickly, and new trade barriers [will] arise”. The prescription: prepare for a world where the old rules no longer apply, build community and institutional resilience, and expect the crisis to “reshape the basic social and economic environment that you now take for granted”.
The 48 Laws of Power (Robert Greene): Law 48, “Assume Formlessness,” is the survival principle for volatile times: “The more rigid we are, the more vulnerable we become in times of transition”. Law 11, “Learn to Keep People Dependent on You,” suggests that the UK’s position in supply chains should be one of indispensability — not of a consumer dependent on others, but of a provider that others depend on. Law 2, “Never Put Too Much Trust in Friends, Learn How to Use Enemies,” cautions against assuming that “friendly” jurisdictions will always remain friendly.
The 33 Strategies of War (Robert Greene): Strategy 19, “Create a Centre of Gravity,” advises becoming the “indispensable link” in a friendly supply chain rather than seeking confrontation. The book’s core lesson on logistics is that ” world stops” and that “leaders win through logistics”. The strategic imperative is to control your own logistics and supply lines, not to trust that others will keep them open.
The Psychology of Money (Morgan Housel): The central lesson is margin of safety. “Margin of safety is raising the odds of success at a given level of risk by increasing your chances of survival. Its magic is that the higher your margin of safety, the smaller your edge needs to be to have a favorable outcome”. Also critical: “Few gains are so great that they’re worth wiping yourself (or your business) out over”. And the barbelled approach: “Be optimistic about the future, but paranoid about what will prevent you from getting to the future”.
—
What Are the Conclusions and Tips for Protection?
The conclusions are that supply chain risk has become permanent, not cyclical; that the UK is structurally exposed; and that the only viable response is to build resilience before the crisis peaks — and the tips for protection are to act now, act collectively, and act with margin of safety built into every decision. As The Fourth Turning warns, “Don’t think you can escape the Fourth Turning. History warns that a Crisis will reshape the basic social and economic environment that you now take for granted”.
Final tips for UK business decision makers:
Accept that this is the new normal. The era of cheap, reliable, global supply chains is over. Plan for volatility as a permanent condition, not a temporary phase.
Build margin of safety into every dimension. Cash reserves, inventory buffers, supplier diversity, logistics redundancy — all of these are forms of margin of safety. As Housel writes, “the higher your margin of safety, the smaller your edge needs to be”.
Use the books as strategic guides, not just inspiration. The Fourth Turning tells you to expect systemic crisis. 48 Laws of Power tells you to stay flexible and indispensable. 33 Strategies of War tells you logistics is survival. The Psychology of Money tells you margin of safety is the only thing that matters.
Engage government early and with evidence. The JLR loan guarantee shows government will act, but only when the case is compelling and the sector is organised. BusinessRiskTV’s forum is the platform for that coordination.
Remember that opportunities exist alongside risks. Reshoring, alternative suppliers, water technology, food localisation, logistics optimisation — these are growth markets. The firms that build resilience will also build market share.
Start today. The cost of delay is not just money — it is survival.
In 2026, UK business insolvencies are near 30-year highs. With 2,022 companies folding in March alone, leaders face a triple threat: maturing debt at 8% rates, a looming private credit crash warned of by the Bank of England, and geopolitical tariff shocks. This guide reveals 12 risk management steps to stop your business going bankrupt, including refinancing strategies, HMRC defence tactics, and supply chain shifts to survive the 2026 liquidity crunch.
Stop guessing about bankruptcy. Join the Business Risk Management Club today.
The average cost of a mid-sized company insolvency is £90,000 in director losses. The cost of our club membership? Less than a cup of coffee a day.
3 Facts to Back Up Our Value:
1. Cost: We charge £49.99 per month for full access (introductory deals available for limited time). An insolvency practitioner charges £350+ per hour.
2. Speed: Members get 24/7 access to alternative risk reviews. Banks and risk analysts take weeks.
3. Certainty: We provide real-time geopolitical risks; majority of failed businesses didn’t see the shock coming before too late.
—
Why Should UK Business Leaders Be Worried About Bankruptcy in 2026? (The “Triple Lock” Crisis)
Why UK business leaders should be worried about bankruptcy in 2026 because insolvencies are currently near a 30-year high due to a “triple lock” of debt maturity cliffs, geopolitical trade wars and geopolitical risks, and a hidden private credit crash.
We are not in a normal recession; we are in a debt maturity trap. In March 2026 alone, England and Wales recorded 2,022 company insolvencies, matching the peak levels of the 2008 financial crisis . For a 10-year-old: Imagine borrowing a toy for a week, but when you try to return it, the shop says you now owe 10 times the price, and your pocket money just got cut because your friends are fighting far away. That is 2026.
Are Maturing Debt Instruments the #1 Cause of UK Business Bankruptcies Right Now?
Yes, maturing debt instruments taken out at 2% that are maturing at 8% rates are the single biggest driver of cash flow collapse in the UK in 2026 because refinancing has dried up for the mid-market.
UK borrowing costs hit their highest levels since 1998 recently, with 30-year gilt yields hitting 5.78% . For a 10-year-old: You borrowed £1 to buy lemonade supplies, promising to pay back £1.02. Now, the bank says you must pay back £1.15. If you don’t have that extra 13p, your lemonade stand is gone.
How Do Geopolitical Changes and Tariffs in 2026 Hurt My UK Supply Chain?
Geopolitical changes in 2026, specifically the Iran conflict and the UK-US trade deal delays, are forcing costs up by up to 20% for importers, strangling margins just as debts come due.
The UK just signed a $5 billion Gulf trade deal to bypass Iran war fallout, but the US remains rocky . UK Parliament admits the US deal is “not yet delivering growth” as tariffs fragment the global system . For a 10-year-old: Your favourite toy is made across the street. If the street gets blocked by a fight, you have to fly a helicopter to get the toy. That helicopter costs more than the toy.
Is the “Private Credit” Market Really Drying Up for UK Businesses in 2026?
The threat of credit drying up is real because the Bank of England has warned that the $2.5 trillion private credit market has “echoes of the Great Financial Crisis” and has never been tested at this scale.
Deputy Governor Sarah Breeden explicitly stated that a “private credit crunch” is coming where funds are “gated” (locked) . The House of Lords reports that SME finance has been “squeezed” because banks retreated after 2008 and private credit is now freezing . For a 10-year-old: You usually borrow money from a rich friend. But that friend is suddenly broke and hiding under their bed. Now nobody will lend you the money to buy your lunch.
Are These the Most Common Causes of Bankruptcy in the UK Right Now (2026 Stats)?
Yes, these are the most common causes, but rising employment costs and HMRC aggression are the “silent killers” pushing the UK toward the highest bankruptcy rate in 20 years.
In 2025, an estimated 288,018 UK businesses failed (roughly 5% of all firms) . The construction sector accounts for 17% of all insolvencies due to material costs, while retail is collapsing due to wage bills . The UK is seeing the highest rate of bankruptcies since the early 1990s, driven not just by debt, but by the Employment Rights Act 2025 which doubles redundancy costs .
—
🛡️ 12 Business Risk Management Steps UK Business Leaders Should Take Today
To avoid joining the 2,000+ companies failing monthly, execute these steps immediately:
1. Refinance NOW, not later.
· Action: Approach challenger banks (e.g., Shawbrook, OakNorth) before your current loan matures. Lending growth has slowed to 4.5%, get in the queue now .
2. Stress test for 10% Interest Rates.
· Action: Model your cash flow assuming base rates hit 8%. If you break, cut costs today.
3. Audit your “Phantom Stock”.
· Action: Check supplier contracts for geopolitical escalation clauses. If they aren’t there, add them for the Iran/Gulf fallout .
4. Diversify away from US supply chains.
· Action: Shift 30% of sourcing to the new GCC trade deal partners (UAE, Saudi) to bypass US tariffs .
5. Invoice factoring for immediate cash.
· Action: Sell your unpaid invoices. With credit drying up, cash in hand is king.
6. The “Credit Committee” meeting.
· Action: Hold a weekly 15-minute meeting to check if your customers have issued winding-up petitions. Don’t sell to companies about to go bust .
7. Prepare for Employment Rights Act 2025.
· Action: Set aside a specific fund for “protective awards” (now 180 days pay) before making redundancies .
8. HMRC negotiation strategy.
· Action: HMRC is taking aggressive debt action. Do not ignore their letters; agree on a Time to Pay arrangement before they file a winding-up petition.
9. Invest in Internal Controls (Governance).
· Action: Under the new UK Corporate Governance Code (Jan 1 2026), directors are personally liable for “material weaknesses” in financial controls .
10. Explore a CVA before it’s too late.
· Action: Company Voluntary Arrangements (CVAs) are up 29% year-on-year. Use them to bind creditors to a reduced payment plan before you run out of cash .
11. Cancel the “Golden Quarter” overspend.
· Action: Consumer spending is dropping . Do not stockpile inventory unless it is paid for.
12. Join an Early Warning System.
· Action: Use data providers to see if your bank is increasing “expected credit losses” (like HSBC did with $1.3bn) – this means they will stop lending to you .
Get help to protect and grow your business faster regardless of business environment with help from Business Risk Management Club
Additional Tags: UK Insolvency Statistics 2026, Maturing Debt Risk, Private Credit Market UK, Bank of England Warning 2026, Geopolitical Tariffs UK, Supply Chain Disruption, Business Risk Management Steps, Avoid Bankruptcy UK, UK Interest Rates 2026, Corporate Governance Code 2026.
⚠️ Important Legal Notice: I am not a licensed insolvency practitioner or financial advisor. The above information is for educational purposes based on current data trends. For specific legal or financial advice regarding your business, you must consult a qualified professional like those found via the BusinessRiskTV.com network.
UK Bankruptcy Crisis 2026: Why Debt Maturity, Private Credit Fears & Tariffs Are Killing Businesses (12 Steps to Survive)
The BRICS group’s pilot launch of the “Unit,” a gold-backed digital trade instrument, signals a major shift away from the US Dollar. For international businesses, this de-dollarisation trend creates significant FX and market access risks. Discover the 6 essential business risk management actions—from diversifying payment rails and currency hedging to supply chain re-evaluation—that business leaders must implement now to protect and grow their business in a rapidly changing, multipolar global financial landscape.
The launch of the BRICS “Unit” gold-backed digital trade instrument, even in its pilot phase, signals a significant, long-term shift toward de-dollarisation and the emergence of a multipolar financial system. This development primarily creates currency volatility risk, geopolitical risk, and market access risk for international businesses.
Business Risk Management Actions For BRICS Gold Backed Currency
Business leaders must take proactive steps to protect profit margins and capitalise on new trade opportunities that bypass the traditional dollar-centric financial architecture.
1. Diversify Currency Exposure and Payment Rails
Action: Systematically audit all accounts receivable and accounts payable to quantify exposure to the US Dollar (USD) versus BRICS currencies (BRL, CNY, INR, RUB, ZAR) and the new “Unit” if it becomes readily available for international trade.
Mitigation: Establish banking relationships or payment channels that can facilitate settlements in multiple currencies, including BRICS members’ local currencies and potentially the Unit. This reduces reliance on USD-centric payment systems like SWIFT.
2. Adopt Dynamic Currency Hedging Strategies
Action: Move beyond simple forward contracts and explore more flexible hedging instruments like currency options to protect margins while retaining the ability to benefit from favourable exchange rate movements.
Mitigation: Implement a formal, actively monitored Foreign Exchange (FX) risk management policy. Consider utilising natural hedging by matching revenues and expenses in the same currency to reduce net exposure (e.g., sourcing materials in Chinese Yuan if sales are also made in Yuan).
3. Revise Trade and Procurement Strategies
Action: Evaluate the cost-competitiveness of suppliers and buyers within BRICS and Global South nations who may preferentially adopt the Unit for trade settlement, benefiting from lower transaction costs.
Mitigation: Proactively renegotiate existing contracts to include multi-currency settlement clauses or specify pricing in a currency basket that aligns with the Unit’s composition (gold + BRICS currencies) to stabilise invoice values against pure fiat currency volatility.
4. Geographic and Supply Chain Re-evaluation
Action: Map the geographic distribution of your supply chain and customer base to identify regions most likely to adopt the “Unit” (i.e., BRICS nations, Global South/Africa).
Mitigation:Increase market intelligence focus on these regions. Where feasible, localise manufacturing or sourcing in key BRICS countries to operate and transact more easily within their emerging financial ecosystem and reduce cross-currency friction.
5. Monitor Political and Regulatory Developments
Action: Designate a senior executive or external consultant to track the official adoption status, technical specifications, and regulatory compliance requirements of the BRICS Unit in relevant markets.
Mitigation:Develop contingency plans for scenarios where major trading partners impose tariffs or sanctions in response to de-dollarisation efforts, such as the potential for US tariff actions.
6. Model Financial Impact Scenarios
Action: Incorporate high-impact, low-probability events—such as a rapid 10-20% USD devaluation or the swift, widespread adoption of the Unit across key commodity markets—into financial forecasting and budgeting.
Mitigation: Use the scenario models to determine acceptable levels of currency volatility for profit margins and establish clear trigger points for enacting the new, diversified hedging and payment strategies.
Get help to protect and grow your business faster with BusinessRiskTV
This analysis critiques the UK’s reliance on OBR fiscal forecasts, arguing that it creates unaccountable economic policy and business uncertainty. We explore the risks of governing by five-year predictions and propose alternative models for a more stable and democratically accountable fiscal framework, empowering UK citizens and businesses to set their own destiny.
OBR Forecasts and Fiscal Rules: A Flawed System for UK Economic Policy?
The Problem with Forecasting Dependency in UK Fiscal Policy
The UK’s fiscal framework operates on a paradoxical foundation. We base binding five-year fiscal rules on Office for Budget Responsibility (OBR) forecasts that struggle to accurately predict economic outcomes just twelve months ahead. This creates a system where unaccountable economic policy dictates business conditions and living standards through increasingly speculative longer-term projections.
The core issue isn’t the OBR’s technical competence—it’s the structural flaw of building rigid fiscal rules on inevitably imperfect predictions. When even the OBR acknowledges its central forecasts have “virtually no chance of being correct,” constructing national economic strategy around these numbers represents a fundamental governance failure that undermines both democratic accountability and economic stability.
How OBR Forecasting Creates Business Uncertainty
The Volatility of Forecast-Led Policy Making
Businesses face constant uncertainty from a system that reacts to forecast revisions rather than economic fundamentals. The bi-annual budget cycle creates policy instability as taxes and spending adjustments are made to hit moving targets based on numbers that will likely be revised in the next forecast.
The Accountability Deficit in Economic Governance
When policies are presented as necessary responses to OBR forecasts, elected politicians gain convenient insulation from difficult decisions. This democratic deficit means voters cannot properly hold decision-makers accountable for tax and spending choices that fundamentally shape their economic lives.
A Better Framework for UK Fiscal Responsibility
Moving Beyond Point Forecasts to Scenario Planning
A more robust approach would replace dependency on single-point forecasts with mandatory scenario analysis. Government fiscal plans should demonstrate resilience across multiple plausible economic pathways—including downside risks and upside potential—rather than optimising for one central scenario that will almost certainly prove wrong.
Reforming the Budget Process for Economic Stability
Eliminating the two-main-fiscal-events-per-year cycle would reduce policy volatility and discourage short-term manipulation of forecasts. A single annual budget would force longer-term thinking and create a more predictable environment for business investment and household planning.
Taking Control of Britain’s Economic Destiny
Addressing Root Causes Rather Than Symptoms
The current approach to cost-of-living pressures focuses primarily on income-based solutions through benefits and tax adjustments. A more sustainable strategy would tackle structural inflation drivers through supply-side reforms in housing, energy, and regulation that directly lower costs rather than merely redistributing them.
Restoring Democratic Accountability to Economic Policy
Ultimately, the solution lies in re-establishing clear lines of political responsibility for economic outcomes. By focusing on policy levers within direct government control—rather than forecast technicalities—we can create a system where voters can clearly judge their representatives on tangible economic results.
Business Risk Analysis: The Perils of OBR-Led Fiscal Policy
This critique highlights a fundamental risk for businesses and consumers in the UK: the subordination of long-term fiscal policy to specific, short-term economic forecasts produced by a non-elected body, the Office for Budget Responsibility (OBR). From a risk management perspective, this creates a system plagued by volatility, a lack of accountability, and strategic misalignment.
Core Risk Assessment
The current framework introduces several critical risks to the business environment:
Forecast Reliance Risk: Basing binding fiscal rules on precise 5-year forecasts is to build a strategy on inherently unstable ground. The OBR itself is transparent about the immense uncertainty in its projections. For instance, its own fan charts show that a forecast for borrowing in 2028-29 has a near-zero probability of being correct. For a business, this is akin to making a 5-year investment decision based entirely on a single, highly speculative market prediction. The risk is that government policy—and therefore the business environment—is constantly adjusting to what are essentially “best guesses.”
Political Accountability Risk: The “accountability gap.” When fiscal policy is presented as a necessary response to the OBR’s forecast, elected politicians can abdicate responsibility for tough choices. They can claim their hands are tied by the numbers, effectively shielding themselves from direct voter accountability for tax and spending decisions. This undermines democratic oversight and makes it difficult for the electorate to “hold politicians to account,” as you state.
Policy Volatility Risk: The bi-annual forecast cycle (Spring Statement, Autumn Budget) creates a “stop-start” policy environment. Businesses face the risk of sudden tax changes or spending announcements designed to manipulate a specific forecast metric for the next 5-year window. This prevents the long-term stability and predictability that businesses need to invest, hire, and grow with confidence.
A Better Way: A More Resilient and Accountable Framework
A superior risk management approach would shift the system away from its dependence on precise forecasts and toward a more transparent, stable, and outcome-oriented model. Here are the key components of a better way:
1. Shift from Point Forecasts to Scenario Planning
Instead of tethering fiscal rules to a single, inevitably incorrect number, the government should be required to present its fiscal plans against a range of plausible economic scenarios. This would include:
A downside scenario (e.g., recession, higher inflation).
A central scenario (the current forecast).
An upside scenario (stronger growth, lower borrowing costs).
Policies would then be designed to be resilient across these ranges. This forces a conversation about contingency plans and buffers, much like a prudent business would do, rather than betting the entire national strategy on one outcome.
2. Reform the Budgetary Process for Stability
A significant step would be to move to a single, comprehensive annual budget. This would end the disruptive cycle of two major fiscal events per year and discourage the short-term tinkering designed to “game” the OBR’s forecasts. This change has been recommended by bodies like the Institute for Government and would provide a more stable platform for business planning.
3. Focus on Controlling the Cost of Living, Not Just Incomes
Currently, the government’s primary tool for managing the cost of living is “income-based”—using benefits, tax credits, and subsidies to top up household incomes. This often leads to higher government spending and debt.
A more sustainable, “cost-based” approach would empower people to “set our own destiny” by tackling the root causes of high prices through supply-side reforms. This includes:
Housing: Radical reform of the planning system to significantly increase the supply of housing, which would directly lower the single biggest cost for most households.
Energy: Streamlining regulations to encourage investment in diverse and secure energy sources.
Childcare and Social Care: Reforming regulations to increase supply and competition in these sectors.
The success of these policies is measurable in tangible outcomes—more houses built, lower energy bills, more affordable childcare—that voters can clearly see and for which they can hold their elected representatives directly responsible.
Conclusion
The current over-reliance on OBR forecasts creates a brittle and unaccountable fiscal policy framework. It transfers significant business risk from the government’s balance sheet to the private sector in the form of volatility and uncertainty.
A better path involves embracing uncertainty through scenario-based planning, stabilising the policy cycle, and shifting political focus to supply-side reforms that directly lower the cost of living. This would create a more resilient economy, a more predictable business environment, and a system where voters can truly judge their politicians on the tangible outcomes they deliver, restoring a direct line of democratic accountability.
The OBR Problem: How Flawed Forecasts Dictate UK Cost of Living and Business Risk
This risk analysis decodes the Ukraine conflict through the lens of the Monroe Doctrine, arguing Russia views NATO expansion and “defensive” missiles in Eastern Europe as an existential threat akin to the Cuban Missile Crisis. We assess the tangible pathways for escalation to a wider war and the critical need for strategic de-escalation to manage this global business risk.
Business Risk Management Analysis: The Ukrainian Conflict and Escalation to a Wider War
This analysis assesses the high-level strategic risks in the Ukraine conflict, framing them through historical parallels, core security doctrines, and the potential for catastrophic escalation. The central thesis is that the deployment of advanced Western missile systems near Russia’s borders is perceived by Moscow as a direct, existential threat akin to the 1962 Cuban Missile Crisis, creating a volatile environment where miscalculation could lead to a third world war.
1. The Core Threat: “Decapitating” Missiles and the Russian Perception
From a risk management perspective, the primary threat driver is not the conventional war in Ukraine itself, but the strategic weapons systems being deployed around Russia’s periphery.
The Nature of the Threat: Systems like the Aegis Ashore sites in Poland and Romania, while officially labelled as defencive “missile shields,” are perceived by Russia as possessing offensive potential. The launchers used for SM-3 interceptor missiles are functionally similar to those used for land-attack cruise missiles. This ambiguity allows Russia to frame them as a “decapitating” strike threat—a first-strike weapon capable of neutralising Russia’s nuclear command-and-control and retaliatory capabilities, thereby crippling its ultimate deterrent.
The Historical Parallel: The Cuban Missile Crisis: This is not a superficial comparison in Moscow’s view. In 1962, the United States considered the deployment of Soviet nuclear missiles in Cuba—a small, neighbouring country—an intolerable, existential threat and was prepared to go to war to have them removed. Russia applies the same logic in reverse. It views NATO’s eastward expansion and the placement of advanced missile systems in its former sphere of influence as a modern-day equivalent of the Cuban Missile Crisis. The potential future deployment of such systems to a country like Venezuela would only reinforce this narrative and mirror the 1962 scenario exactly.
2. The Doctrinal Framework: The “Monroe Principle” Applied to Ukraine
The Original Doctrine: The U.S. Monroe Doctrine (1823) declared the Western Hemisphere its sphere of influence, deeming it off-limits to further European colonisation or political interference.
The Russian Interpretation: Russia has effectively declared a similar doctrine for its “near abroad,” particularly Ukraine. From the Kremlin’s perspective, a neutral or buffer Ukraine is a fundamental security requirement. A Ukraine integrated into NATO—a military alliance historically opposed to Russia—is as unacceptable to Moscow as a Mexico or Canada in a military alliance with China or Russia would be to Washington. This principle explains the intensity of Russia’s response; it is fighting what it sees as a defensive war to prevent a hostile power from consolidating on its doorstep.
3. The Ultimate Risk: Escalation to a Third World War
The convergence of the missile threat and the Monroe-style doctrine creates a high-probability, high-impact risk scenario for a wider conflict. The pathways to escalation are multiple:
Direct Engagement: An accidental or intentional strike on NATO territory (e.g., in Poland or Romania) by a Russian missile, or vice-versa, could trigger NATO’s Article 5 collective defense clause, leading directly to a Russia-NATO war.
Hybrid Warfare Blowback: Acts of sabotage attributed to Russia (e.g., against undersea infrastructure) or provocative actions like the repeated violations of NATO airspace could spiral out of control. A single miscalculation in this “gray zone” could be misread as an act of war, demanding a conventional military response.
Inadvertent Escalation: The fog of war creates immense risk. An errant missile, the misidentification of an aircraft, or a miscommunication during a high-alert period could trigger a cycle of retaliation that neither side initially intended.
4. Analysis of the “Forever War” Driver Claim
The assertion that intelligence services like MI6 (UK), BND (Germany), and DGSE (France) are deliberately driving a “forever war” is a significant claim. A risk analysis must distinguish between stated policy and verifiable evidence.
The Official Policy Stance: The publicly stated goal of the UK, France, and Germany is to support Ukraine’s sovereignty and prevent a Russian victory that would undermine European security and the international order. Their actions—providing weapons, intelligence, and training—are consistent with this stated goal of enabling Ukraine to defend itself.
The “Forever War” Narrative: The claim that these agencies are actively sabotaging peace to prolong the conflict is primarily propagated by the Russian government and commentators who align with that viewpoint. While individual politicians or analysts in the West may argue that prolonged conflict serves to weaken Russia strategically, there is a lack of publicly available, verified intelligence or official documentation proving a coordinated policy by MI6, BND, and the DGSE to deliberately instigate a “forever war.” From a risk management standpoint, this narrative remains an unverified, high-severity contingent liability rather than a confirmed fact upon which to base a strategic assessment. The driving objective of Western powers appears to be achieving a favorable outcome for Ukraine, not perpetuating a war for its own sake, though the effect of their support is indeed a prolonged conflict.
Conclusion and Risk Mitigation
The highest-priority risk is the potential for direct conflict between Russia and NATO. To defuse the situation, risk mitigation must address the core perceived threats:
Strategic Arms Control: A renewed and urgent dialogue on strategic stability and missile defense is critical. Clarifying the capabilities and intent of systems in Eastern Europe, potentially with verification measures, could reduce the “decapitation strike” fear that drives Russian escalation.
Addressing the Sphere of Influence: While morally problematic, any durable settlement will likely need to implicitly acknowledge Russia’s Monroe-style security concerns regarding Ukraine’s alliance status, finding a formula for Ukrainian security that does not involve NATO membership.
De-escalation Channels: Maintaining and strengthening direct military-to-military communication lines between Russia and NATO is essential to manage incidents and prevent inadvertent escalation.
Failure to manage these core risks creates a business environment for the world where the threat of a great power conflict remains unacceptably high.
Here are 6 actionable risk management steps business leaders should take today to protect their operations from the geopolitical risks outlined in the analysis.
Action: Move beyond ad-hoc news reading. Establish a formal process, assigning a team or using a dedicated service to monitor geopolitical intelligence with a specific focus on:
NATO-Russia rhetoric and military posturing.
Incidents in border regions of Poland, Romania, and the Baltic states.
Developments in potential flashpoints like Kaliningrad or the Black Sea.
Rationale: Early warning of escalating tensions provides crucial lead time to activate contingency plans before markets or supply chains are paralysed.
2. Stress-Test Supply Chains for “Choke Point” Failure
Action: Identify single points of failure, especially those dependent on routes or regions exposed to the conflict zone (e.g., air corridors over Eastern Europe, key ports on the Black Sea, rail lines through Poland). Model scenarios involving the closure of these channels and pre-qualify alternative suppliers and logistics routes.
Rationale: A direct NATO-Russia incident would immediately disrupt transport and logistics across Eastern Europe, severing critical arteries for business.
3. Develop a Tiered “Escalation” Response Plan
Action: Create a dynamic response plan with clear triggers for different levels of escalation, not just a binary “crisis/no-crisis” switch. For example:
Level 1 (Heightened Tension): Review and communicate travel security protocols.
Level 2 (Direct Incident): Activate remote work mandates for staff in affected regions, freeze new investments.
Level 3 (Open Conflict): Execute evacuation plans, implement full business continuity protocols.
Rationale: A phased approach prevents panic and ensures a measured, appropriate response as a situation deteriorates.
4. Fortify Cybersecurity Posture Immediately
Action: Assume that a wider geopolitical conflict will involve significant cyber warfare. Mandate multi-factor authentication across all systems, ensure backups are air-gapped and immutable, and conduct fresh table-top exercises for scenarios like ransomware attacks on critical infrastructure or wiper malware targeting corporate networks.
Rationale: Businesses are considered legitimate targets in state-level cyber conflicts. Proactive defence is no longer optional.
5. Model Financial Shock Scenarios
Action: Work with finance to model the impact of a sudden energy price spike, a freeze in capital markets, rapid currency devaluation, or the collapse of trade with a broader set of countries. Stress-test liquidity and credit lines under these conditions.
Rationale: The financial contagion from a great-power conflict would be immediate and severe, potentially locking companies out of vital capital.
6. Conduct a Critical Talent and Operations Review
Action: Audit your workforce and key operations to identify critical dependencies on personnel, facilities, or partners located in NATO member states bordering Russia and Ukraine. Develop plans for remote work, relocation, or knowledge transfer to mitigate the risk of these assets becoming inaccessible or unsafe.
Rationale: Protecting human capital is the first priority. Furthermore, the loss of a key team or facility in a frontline state could cripple business units.
Get help to protect and grow your business faster with less uncertainty impacting on your business objectives
Weather modification and geoengineering are no longer science fiction—they are emerging enterprise risks. With U.S. Congressional investigations and state-level bans on the rise, business leaders must act now. Discover the 6 essential risk management tips to protect your global operations from this new frontier of threats.
Is your business prepared for the risks of climate engineering? 🌍 Our latest article breaks down why the U.S. Congress is investigating and provides 6 actionable risk management tips you need to adopt now.
While research into climate-altering technologies is advancing, the evolving legal landscape and potential for unintended consequences mean business leaders can no longer afford to treat geoengineering as a distant speculation. It is a developing enterprise risk that demands immediate attention.
What Are Weather Modification and Geoengineering?
These terms refer to deliberate, large-scale interventions in Earth’s systems:
Weather Modification aims for short-term, local changes to weather patterns. The most common technique is cloud seeding, which involves dispersing substances like silver iodide into clouds to enhance precipitation or snowpack . It is practiced in several U.S. states, primarily to combat drought. Geoengineering (or climate intervention) seeks to counteract climate change on a regional or global scale. The two main approaches are:
Solar Radiation Management (SRM): Techniques like stratospheric aerosol injection, which aims to cool the planet by reflecting sunlight away from Earth, similar to the effect of a large volcanic eruption .
Carbon Dioxide Removal (CDR): Methods that extract CO₂ from the atmosphere or ocean .
A key distinction is that weather modification is intended for local, short-term effects, while geoengineering is designed for larger, longer-lasting impacts .
The Shifting Regulatory and Oversight Landscape
The governance of these technologies is in flux, moving from scientific debate into the political and legal arena, which directly impacts business risk.
Growing Political Scrutiny: The U.S. Congress is showing increased interest. A subcommittee in the House of Representatives has held hearings demanding transparency on government weather and climate engineering activities . This political focus highlights the issue’s rising profile and the potential for future regulations.
Emerging State-Level Bans: In the absence of comprehensive federal law, states are taking action. Florida recently passed a law prohibiting the intentional release of substances to alter weather, temperature, or sunlight, making it a felony . Similar bills have been introduced in states like Texas, Pennsylvania, and North Carolina . This creates a complex patchwork of regulations for companies operating across state lines.
Lack of International Framework: There is no binding international treaty governing solar geoengineering research or deployment . This legal vacuum creates uncertainty for global businesses and raises the risk of international disputes if one country’s actions are perceived to cause harm in another .
Why This Matters for Global Businesses
For business leaders, this is not a theoretical environmental issue but a tangible source of strategic risk.
New Physical and Operational Risks: Geoengineering could create novel and unpredictable climate conditions. A company’s risk management must now consider scenarios like “termination shock”—a rapid and dangerous temperature increase if a sustained solar geoengineering program were to suddenly stop . This could threaten supply chains, agricultural production, and infrastructure in ways that existing climate models do not capture.
Perception and Geopolitical Risks: Even the perception of geoengineering can be destabilizing. In a world of geopolitical competition, a natural disaster could be wrongly or rightly attributed to a rival’s weather modification program, leading to political tensions that disrupt global trade and markets . Businesses could be caught in the crossfire of such disputes.
Legal and Reputational Exposure: As seen with the state-level bans, companies involved in or perceived to be supporting these technologies could face legal liability, hefty fines, and reputational damage . The lack of a clear regulatory framework makes it difficult to assess and mitigate these risks.
Risk Management Tips for Business Leaders
Enterprises should take proactive, low-regret actions now to build resilience against these emerging threats .
Integrate Climate Intervention into Enterprise Risk Management (ERM): ERM teams should formally assess how geoengineering could impact the organization. This involves interviewing key stakeholders to evaluate visibility (awareness of risks), agility (ability to adapt plans), and resilience (capacity to recover from disruptions).
Develop Specific Key Risk Indicators (KRIs): Move beyond general climate metrics. Create KRIs that directly tie to geoengineering and extreme weather, such as the value of assets in regions proposing geoengineering bans or the percentage of supply chain partners located in high-risk weather modification zones.
Model Multiple Financial Scenarios: Use climate-risk financial modeling tools to estimate the potential financial impact of both the physical effects of geoengineering and the transition risks from new regulations. These calculations help quantify the value at risk.
Strengthen Supply Chain Redundancy and Diversification: Geoengineering could alter regional weather patterns, benefiting some areas and harming others. Diversify suppliers and logistics routes to avoid over-concentration in any single geographic region that might be disproportionately affected.
Invest in Data Gathering and Digital Resilience: The ability to monitor and model these new risks depends on data. Invest in cloud-based risk management software to process complex climate and regulatory data streams. Ensure digital operations are resilient to adapt quickly to new information.
Conduct a Regulatory Horizon Scan: Proactively monitor the evolving regulatory landscape at state, federal, and international levels. This is crucial for anticipating new compliance requirements and avoiding costly legal surprises .
The decisions made by governments and scientists about geoengineering will have profound implications for the stability of the global climate and, by extension, the global economy . By understanding these technologies and implementing a robust risk management strategy now, business leaders can protect their assets and build a more resilient enterprise for an uncertain future.
Get help to protect and grow your business faster with less uncertainty
Bill Gates urges a strategic pivot from climate-only focus to integrated poverty and economic growth risk management. Discover why this redefines corporate risk and explore 6 essential business risk management strategies for leaders. Learn how to build resilience in a complex new era of global development.
Bill Gates on Climate and Poverty: 6 Business Risk Management Strategies for a New Priority
In a significant shift of perspective, Bill Gates is advocating for a “strategic pivot” in global priorities, urging leaders to balance climate goals with immediate human welfare needs like poverty and disease . He argues that a “doomsday view” of climate change is diverting resources from the most cost-effective ways to improve lives and build resilience in the world’s poorest countries . For business leaders, this evolution in the climate debate introduces a new layer of strategic risk. It signals a more complex operating environment where a singular focus on emissions reduction may need to be integrated with a renewed emphasis on economic development and poverty alleviation . Companies must now re-evaluate their risk management frameworks to navigate a potential fragmentation of global regulations and align their strategies with a growing focus on holistic human welfare to ensure long-term resilience and legitimacy.
Navigating the Shift: From Climate-Centric to Integrated Risk Management
This shift in perspective is vital for business leaders for several key reasons:
Evolving Policy and Investment Landscapes: Government policies and development funding in emerging economies may increasingly prioritise energy access, job creation, and economic development. Companies aligned solely with a strict decarbonisation agenda may find themselves misaligned with the growth strategies of these key markets.
Reputational and Social License to Operate: In regions where poverty is the immediate crisis, a company’s social license to operate will depend increasingly on its contribution to local economic development, not just its global environmental credentials. Ignoring the “poverty risk” can become a direct business risk.
Supply Chain and Operational Resilience: A focus on economic growth in developing nations could alter the cost and stability of supply chains. It presents opportunities for new manufacturing hubs but also risks like inflationary pressures and increased competition for resources.
In essence, the core business risk is failing to adapt to a world where economic resilience and human welfare are increasingly seen as inseparable from—and sometimes a prerequisite for—long-term environmental sustainability.
Move beyond climate-only scenarios. Develop and stress-test business models against a set of integrated scenarios that simultaneously consider variables like regional economic growth, energy policy shifts, poverty rates, and geopolitical stability alongside climate projections. This will reveal how a focus on poverty reduction in certain markets could create both vulnerabilities and opportunities for your operations.
2. Diversify Energy and Supply Chain Portfolios for Resilience
Acknowledge the potential for a prolonged transition where natural gas plays a key role in economic development. Ensure your energy portfolio is resilient and can adapt to regional differences. Simultaneously, build supply chain resilience by diversifying sources and exploring “friendshoring” to mitigate the risks of a more fragmented global trade environment driven by differing national priorities.
3. Develop Data-Driven Social Impact Metrics
To authentically engage with the “poverty risk management” theme, companies must measure their impact. Develop and monitor Key Risk Indicators (KRIs) and performance metrics related to economic development. This includes tracking job creation within your supply chains, local community investment, and the affordability of your products or services in developing markets.
4. Accelerate AI Adoption for Operational Excellence
In a world of finite resources, efficiency is paramount. aggressively leverage AI and generative AI to optimise logistics, predict maintenance, reduce energy consumption, and streamline administrative tasks. The resulting cost savings and productivity gains free up capital that can be strategically reinvested into both growth initiatives and social impact programs, creating a virtuous cycle.
5. Cultivate Regulatory Agility and Adaptive Governance
The global regulatory environment will become more complex and less uniform. Establish a robust, continuous regulatory monitoring function. Empower your leadership with flexible governance structures that can quickly adapt compliance strategies, capital allocation, and market approaches to different regional realities, whether a region is easing rules for growth or tightening them for climate goals.
6. Apply a Dual Lens to Long-Term Capital Allocation
When evaluating major investments and projects, assess them through two parallel lenses: their environmental footprint and their contribution to economic development. This means weighing a project’s potential for job creation, technology transfer, and improving energy access alongside its carbon emissions. This dual lens will identify strategic opportunities that are both financially sound and socially aligned in the new context.
Putting the Strategy into Practice
Successfully implementing these strategies requires a shift in governance. Foster cross-functional ownership of risk, involving senior leadership, finance, operations, HR, and legal teams in developing these integrated plans. Most importantly, treat this as a continuous process of review and adaptation, not a one-time exercise, to stay ahead in a rapidly evolving global landscape.
By adopting this integrated approach, business leaders can effectively navigate the complex interplay between climate change and poverty, turning new risks into strategic advantages and building more resilient, adaptable, and responsible enterprises.
Learn how to create a safe harbour at work to empower employees to identify business failures and poor practices. Our guide reveals how psychological safety and anonymous reporting boost productivity and drive business improvement.
How to Create Safe Harbour at Work to Identify Business Failures and Improve Performance
Introduction: The Power of Psychological Safety in Business
In today’s competitive business environment, organisational resilience and continuous improvement separate thriving companies from those struggling to adapt. Yet many businesses overlook their most valuable resource for identifying problems and opportunities: their employees. Creating a safe harbour at work where staff can freely report failures, mistakes, and poor practices without fear of reprisal represents a critical competitive advantage. Research consistently shows that organisations with strong psychological safety and transparent reporting mechanisms significantly outperform their peers in risk management and strategic decision-making.
When employees feel safe to speak up, organisations gain access to early warning systems for potential risks, identify inefficiencies that impact productivity, and unlock innovative solutions to persistent problems. This article provides a comprehensive roadmap for building a culture and infrastructure that encourages transparent reporting of organisational failures for remedial action, ultimately driving business performance and productivity to new heights.
Understanding Psychological Safety: The Foundation of Safe Harbour
Psychological safety describes a shared belief that team members will not face punishment or humiliation for speaking up with ideas, questions, concerns, or mistakes. This environment creates the foundation for effective safe harbour protections where employees feel secure in identifying organisational failures.
The Business Case for Psychological Safety
Enhanced risk identification: Employees in psychologically safe environments are more likely to report potential risks, compliance issues, and operational failures early, allowing for proactive intervention before problems escalate.
Improved innovation and problem-solving: When team members feel safe expressing unconventional ideas or questioning existing processes, organisations benefit from diverse perspectives and creative solutions to business challenges.
Reduced operational costs: Early identification of failures and inefficiencies prevents minor issues from developing into costly crises. Companies with mature reporting capabilities experience fewer operational disruptions and compliance failures.
Stronger employee engagement: Organisations that demonstrate respect for employee input through actionable response systems experience higher retention rates and increased productivity.
Establishing Anonymous Reporting Mechanisms
Anonymous reporting channels provide a critical safe harbour mechanism that enables employees to report concerns without fear of identification or retaliation. These systems are particularly important for members of marginalised groups who may historically be less likely to report issues through standard channels.
Choosing Effective Anonymous Reporting Channels
Third-party hotlines: External hotlines managed by specialised providers offer maximum anonymity and are available 24/7, encouraging reporting without concerns about internal tracking or identification.
Secure digital platforms: Web-based reporting systems with encryption and secure data storage allow employees to submit detailed reports, documents, and even multimedia evidence while maintaining confidentiality.
Multi-channel approach: Offering various reporting options (phone, web, mobile app, physical drop box) ensures all employees have access to a comfortable reporting method, increasing participation across different roles and technological comfort levels.
Implementing Anonymous Reporting Systems
Clear scope communication: Explicitly define what types of issues employees can report through these channels—including fraud, safety violations, discrimination, ethical concerns, and process failures.
Robust response protocols: Establish systematic procedures for acknowledging, investigating, and acting on reports, with clear timelines and communication mechanisms to keep reporters informed of progress.
Legal compliance alignment: Work with legal and compliance teams to ensure reporting systems meet regulatory requirements such as the EU Whistleblower Directive and other regional legislation.
Leadership’s Critical Role in Fostering Safe Harbour
Tone from the top represents one of the most significant factors in establishing effective safe harbour protections. Organisations where senior leadership actively champions transparent reporting and risk awareness report significantly higher maturity in identifying and addressing business failures.
Demonstrating Genuine Commitment
Executive vulnerability: Leaders who openly acknowledge their own mistakes and what they’ve learned from them model the behaviour they want to see throughout the organisation, making it safer for others to admit failures.
Resource allocation: Dedicate appropriate staffing and budget to risk and compliance functions. Companies that properly fund these areas report significantly higher capabilities in addressing identified issues.
Direct reporting lines: Ensure heads of risk and compliance have direct access to the board and CEO, rather than being buried multiple levels down in the organisation.
Structural Support for Safe Harbour
Board oversight: Active board engagement in risk oversight and compliance functions signals the importance of identifying and addressing organisational failures at the highest levels.
C-level representation: Organisations with dedicated chief risk officers or chief compliance officers report more mature capabilities in addressing identified issues and improving business processes.
Frameworks for Analysing and Addressing Reported Issues
Creating safe harbour mechanisms represents only half the equation. Organisations must also implement structured processes for analysing reported issues and implementing corrective actions.
Failure Mode and Effects Analysis (FMEA)
Originally developed by the U.S. military, FMEA provides a systematic approach for identifying and mitigating potential points of failure in business processes. The methodology involves forming cross-functional teams to map processes, identify potential failure points, analyse their effects, determine root causes, and plan mitigations. This structured approach ensures that reported issues receive comprehensive analysis rather than superficial fixes.
Continuous Improvement Methodologies
PDCA Cycle (Plan-Do-Check-Act): This iterative four-stage model provides a framework for testing improvements on a small scale before full implementation, reducing the risk of large-scale failures when addressing identified issues.
DMAIC Process (Define, Measure, Analyse, Improve, Control): Part of the Six Sigma methodology, this structured approach helps organisations systematically define problems, measure current performance, analyse root causes, improve processes, and control future performance.
5 Whys Analysis: A simple but powerful technique for drilling down to the root cause of a problem by repeatedly asking “why” until the fundamental underlying issue is revealed.
Recognising and Rewarding Transparency
To sustain a culture of psychological safety, organisations must acknowledge and value employees who identify failures and poor practices.
Effective Recognition Approaches
Non-punitive response to failure: Separate performance management from well-intentioned mistakes or identified process failures, focusing instead on learning and improvement.
Incentive structures: Incorporate ethical behaviour and contributions to process improvement into performance evaluations and compensation decisions.
Success storytelling: Publicly celebrate examples where identified failures led to significant improvements, highlighting the employee’s role in the positive outcome while maintaining confidentiality when needed.
Building Your Safe Harbour: Implementation Roadmap
Creating an effective safe harbour system requires a structured, phased approach that integrates culture, processes, and technology.
Phase 1: Foundation (Months 1-3)
Leadership alignment: Secure executive commitment and define the business case for safe harbour mechanisms.
Initial assessment: Evaluate current state of psychological safety and reporting mechanisms through employee surveys and process analysis.
Channel selection: Choose appropriate anonymous reporting channels based on organisational size, structure, and employee preferences.
Phase 2: Implementation (Months 4-6)
System rollout: Deploy anonymous reporting channels with clear guidelines and protocols.
Policy development: Establish formal non-retaliation policies and investigation procedures.
Process integration: Connect reporting systems with improvement methodologies.
Cross-functional teams: Establish dedicated groups to analyse reports and implement solutions.
Measurement system: Define and track metrics for system effectiveness and cultural impact.
Phase 4: Optimisation (Ongoing)
Continuous feedback: Regularly solicit employee input on safe harbour effectiveness.
System refinement: Enhance processes based on performance data and changing organisational needs.
Cultural reinforcement: Maintain leadership emphasis and recognise success stories.
Conclusion: Transforming Failures into Opportunities
Building effective safe harbour protections represents more than a compliance exercise—it’s a strategic imperative that transforms how organisations identify and address weaknesses. By creating multiple channels for transparent reporting, implementing structured methodologies for analysing failures, and fostering leadership commitment to psychological safety, companies can convert potential threats into powerful opportunities for improvement.
Organisations that excel in this area don’t just avoid problems; they build lasting competitive advantage through enhanced innovation, stronger employee engagement, and systematic continuous improvement. The journey requires sustained commitment, but as leading companies demonstrate, the rewards in business performance, productivity, and resilience make it an investment that pays continuous dividends.
Discover why critical thinking beats collective stupidity in business. Learn how to avoid groupthink pitfalls and make better decisions with BusinessRiskTV.com’s risk management resources.
Critical Thinking vs Collective Stupidity: Rise Above Groupthink in Business Decision-Making
The Thinking Crisis in Modern Business
In today’s complex business environment, we face a critical crossroads: apply disciplined critical thinking or succumb to the comfortable confines of collective groupthink. The pain of uncertainty often pushes business leaders toward the seeming safety of consensus opinions and mainstream solutions. However, this avoidance of independent thinking comes at a steep price—surrendering your competitive edge, innovation, and ultimately, your business success to the “collective stupidity” that occurs when groups prioritise harmony over accurate analysis.
When critical thinking is no longer deployed, it is replaced by this collective stupidity. Most people are more comfortable agreeing with the crowd instead of questioning the common narrative. Yet as the saying goes, “when everyone is thinking the same thing, no one is thinking properly.” This article explores how business leaders can cultivate genuine critical thinking, avoid the pitfalls of groupthink, and how BusinessRiskTV.com provides tools and communities to support this vital leadership capability.
What is Critical Thinking in Business? Beyond Judgement and Assumption
Defining Critical Thinking
Critical thinking is far more than just being critical; it is a disciplined process of actively analysing, synthesising, and evaluating information to guide decision-making. In its exemplary form, it is based on universal intellectual values including clarity, accuracy, precision, consistency, relevance, sound evidence, good reasons, depth, breadth, and fairness.
The Foundation for Critical Thinking defines it as “that mode of thinking—about any subject, content, or problem—in which the thinker improves the quality of his or her thinking by skillfully taking charge of the structures inherent in thinking and imposing intellectual standards upon them.” For business leaders, this means consistently questioning assumptions, analysing data from multiple sources, and considering decisions from various perspectives before reaching conclusions.
The Critical Thinking Framework in Practice
Understanding the components of critical thinking helps business leaders implement this approach systematically. Critical thinking combines both skills and mindset across several dimensions:
Analytical Thinking involves breaking down complex business problems into manageable components, examining ideas, identifying arguments, and understanding root causes. In practice, this means systematically evaluating market research, financial reports, and operational data rather than accepting surface-level explanations.
Evaluative Thinking requires assessing the credibility of claims and strength of arguments. Business leaders must judge vendor proposals, investment opportunities, or strategic initiatives based on evidence and logical reasoning rather than popularity or tradition.
Synthetic Thinking connects information from multiple sources to form new insights and conclusions. This enables developing innovative business strategies by combining customer feedback, competitive intelligence, and operational capabilities in novel ways.
Self-Disciplined Thinking means consistently applying intellectual standards to one’s own thinking processes. Successful leaders create decision-making frameworks that force examination of personal biases and assumptions before reaching conclusions.
Fair-Minded Thinking involves considering opposing viewpoints and challenging one’s own preconceptions. Organizations that excel at critical thinking actively seek out dissenting opinions in leadership meetings and establish “devil’s advocate” roles to ensure all perspectives are considered.
The Cost of Collective Stupidity: Groupthink in Business
Understanding Groupthink Dynamics
Groupthink is a term developed by social psychologist Irving Janis in 1972 to describe suboptimal decisions made by a group due to social pressures that lead to flawed outcomes. It occurs when the drive for consensus within a group becomes so powerful that it overrides realistic appraisal of alternatives and critical thinking.
This “collective stupidity” represents a form of structural rigidity where organisations continue failing approaches simply because “that’s how we’ve always done it.” As one business innovator noted, “We’d rather be stupid than different”—highlighting the perplexing preference for known failure over the perceived risk of change.
Symptoms and Impact of Groupthink
Irving Janis identified eight symptoms of groupthink that remain relevant to modern businesses:
The Illusion of Invulnerability creates excessive optimism and encourages unnecessary risk-taking while Collective Rationalisation causes members to discount warnings and not reconsider assumptions. The Belief in Inherent Morality leads groups to ignore ethical consequences of decisions while Stereotyped Views of Out-groups fosters negative or dismissive views of competitors or critics.
Direct Pressure on Dissenters emerges when members are pressured not to express arguments against group consensus, reinforced by Self-Censorship where doubts and deviations from perceived group consensus are not expressed. The Illusion of Unanimity falsely assumes the majority view is unanimous while Self-Appointed “Mindguards” protect the group from information that might problematize the consensus.
The impact on businesses can be devastating, resulting in poor decisions due to lack of opposition or critical evaluation, stifled creativity and innovation, overconfidence in flawed strategies, overlooking optimal solutions to business challenges, and building failure into budgets and operations rather than seeking better approaches.
Real-World Examples of Groupthink in Business
Multiple case studies demonstrate how groupthink prevails over evidence-based success:
Boston Scientific experienced a 53% increase in closed sales after piloting an innovative sales method, yet rejected adoption because the model was deemed “too controversial for easy adoption.”
Kaiser Permanente saw sales efficiency jump from 110 visits/18 closed sales to 27 visits/25 closed sales using a new approach, but maintained their existing compensation structure based on visit volume rather than success.
Proctor & Gamble rejected a dramatically more effective sales method because it would require adapting manufacturing and support systems—essentially refusing success due to anticipated implementation challenges.
These cases illustrate the powerful hold of “the way we’ve always done it” even when evidence clearly demonstrates superior alternatives.
How BusinessRiskTV.com Fosters Critical Thinking and Mitigates Business Risks
Breaking Free from Collective Hypnosis
BusinessRiskTV.com positions itself as an antidote to conventional business thinking, urging leaders to “break free from the collective hypnosis often presented as certain risk information.” Their approach emphasises that “playing it safe is the biggest risk of all” in today’s rapidly changing business environment.
Rather than offering standardised solutions, BusinessRiskTV.com provides diverse perspectives and critical analysis tools to help business leaders develop their independent thinking capacity. Their platform acknowledges that “if you do not think for yourself, someone else will think and act for you, but they may not have your best interests at heart”—highlighting the vital importance of independent critical thinking in business protection and growth.
The Risk Management Think Tank provides access to diverse perspectives beyond mainstream business thinking while the Enterprise Risk Management Magazine delivers practical insights for applying critical thinking to risk management. Business Risk Watch offers ongoing monitoring of emerging threats and opportunities complemented by Live Online Workshops featuring interactive sessions for developing critical thinking skills.
Networking Opportunities facilitate connections with leaders globally across multiple industries while Expert Briefings deliver unfiltered intelligence on global business risks. Their approach is built on the premise that “without innovation, without the risk of disruption in the name of success, continued failure is the only option”—directly challenging the groupthink mentality that maintains failing approaches.
What To Do Now: Join BusinessRiskTV.com Business Risk Management Club
Membership Options Explained
BusinessRiskTV.com offers three membership tiers to suit different organisational and individual needs:
The Basic Risk Manager plan is free and includes alerts to business risk management news, access to some Member Only business intelligence, and entry to selected deals and Flash Sales.
The Pro Risk Manager plan requires an annual fee but provides full service features including discounted products, ability to submit articles and advertorials, listing in sponsors directory, and access to comprehensive risk management tools.
The Corporate Member plan is free and includes alerts to business risk management content, access to corporate business intelligence, and entry to selected deals and Flash Sales.
Developing Your Critical Thinking Capacity
Beyond membership, BusinessRiskTV.com encourages developing personal critical thinking skills through these approaches:
Question Your Sources by regularly evaluating the credibility, accuracy, and potential biases of your information sources. Analyse Arguments Systematically by breaking down problems, identifying underlying assumptions, and examining evidence from multiple angles.
Encourage Dissenting Views by actively seeking out and rewarding alternative perspectives in your organisation. Apply Structured Evaluation Frameworks using established critical thinking frameworks for important business decisions. Embrace Intellectual Humility by recognizing that “no one is a critical thinker through-and-through” and remaining open to revising your thinking.
Choose Thinking Over Conformity
The discomfort of uncertainty is not a reason to accept someone else’s certainty. Just because the pain of your uncertainty is uncomfortable does not mean you should accept someone else’s certainty just to feel better. In business leadership, the easy path of following consensus and mainstream thinking often leads to mediocre results at best, and catastrophic failures at worst.
Critical thinking is difficult—which is precisely why most people judge rather than analyse, follow rather than lead. But this difficulty represents a competitive opportunity for those willing to develop this crucial skill. As the search results emphasize, “when everyone is thinking the same thing, no one is thinking properly.”
Business success in our complex, rapidly changing environment requires breaking free from collective stupidity and developing the courage to think independently. Are you ready to “step away from the crowd exhibiting collective stupidity and instead critically think about what is best for your business”? The first step is recognising that true leadership requires not just thinking, but thinking critically.
The collapses of First Brands and Tricolor are more than just isolated failures—they’re a stark warning for the global financial system. Are we repeating the mistakes of 2008? Our latest analysis for business leaders reveals the systemic risks lurking in the $1.5 trillion private credit market and provides 6 essential risk mitigation strategies.
The Looming Avalanche: How Private Credit and Sovereign Debt Could Trigger the Next Financial Crisis
The collapses of First Brands and Tricolor are not mere isolated events. In the words of Jamie Dimon, they are the “cockroaches” that signal a deeper infestation of risk within the private credit market . This article for business decision-makers conducts a crucial risk analysis, building on the warning from the IMF’s Global Financial Stability Report about the close connections between private credit and mainstream banks .
We explore the fundamental vulnerabilities of high leverage, opacity, and weak underwriting, drawing parallels to the pre-2008 subprime mortgage crisis. A special focus is given to the dangerous rise of Payment-in-Kind (PIK) bonds, which allow companies to mask a liquidity crisis by paying interest with more debt, creating a hidden mountain of obligations .
The core of our analysis provides actionable business risk management tips. We outline a clear strategy for leaders to mitigate this threat, emphasising the need for unprecedented transparency, active covenant monitoring, and rigorous stress-testing against a liquidity shock. The time for vigilance is now. Proactive risk management is not just about protection; it’s a competitive advantage in a volatile world.
Beyond Idiosyncratic Failures: A Systemic View of Recent Scandals
A war-gaming exercise of the private credit market would likely reveal that the recent failures of First Brands and Tricolor are not isolated incidents, but rather symptoms of broader, systemic vulnerabilities. The parallels to the pre-2008 environment are striking: high leverage, opacity, and complex interconnections are creating a latent risk within the financial system .
The core of the problem lies in the explosive growth of the private credit market, which has ballooned to a $1.5 trillion asset class . This rapid expansion, occurring largely outside the regulated banking sector, has been fueled by a search for yield in a prolonged low-interest-rate environment. The inherent lack of transparency and regulatory oversight in private credit means that risks are often poorly understood and priced . The IMF has explicitly highlighted the “close connections between private credit markets and mainstream banks” as a primary concern, indicating that stress could rapidly transmit to the core of the financial system .
The collapses of First Brands and Tricolor should be treated as critical data points. Jamie Dimon’s “cockroach” analogy suggests that where there are two public failures, more are likely lurking in the shadows . A deeper analysis points to several interconnected vulnerabilities:
Excessive Leverage and Weak Underwriting: The fundamental driver of risk is the high level of debt placed on companies, often accompanied by weakening lending standards. This is reminiscent of the pre-2008 subprime mortgage frenzy, where the quality of the underlying asset was compromised.
Opacity and Complexity: Unlike public markets, private credit instruments are illiquid and lack standardised reporting . This opacity is compounded by the resurgence of complex structuring, such as the “slicing and dicing” of loan structures, which obscures the true location and concentration of risk.
Linkages to the Broader System: The IMF’s concern underscores that private credit is no longer a niche segment. Mainstream banks provide funding and credit lines to non-bank lenders, and a wave of defaults in private credit could trigger a liquidity crunch that spills over into the banking sector.
The PIK Debt Delusion: A specific and dangerous trend is the increasing use of Payment-in-Kind (PIK) bonds and PIK toggles . These instruments allow companies to pay interest with more debt instead of cash, creating a “financial time bomb” where corporate debt loads balloon silently until they become unsustainable .
Business Risk Management Tips for Decision-Makers
To mitigate these threats, businesses must move beyond complacency and adopt a proactive, rigorous risk management stance.
Demand Unprecedented Transparency in Counterparty Risk: Do not accept surface-level financials. Insist on transparent, defensible credit scores and rigorous due diligence for any entity exposed to private credit markets, whether as an investment, lender, or key partner. Use standardised scorecards that combine quantitative and qualitative factors to assess risk consistently .
Implement Active, Not Passive, Portfolio Surveillance: Move beyond static annual reviews. Establish active monitoring systems that track covenant cushions in real-time and proactively identify deteriorations in credit quality. Advanced covenant monitoring is pivotal for early detection of potential breaches.
War-Game Your Exposure to a Liquidity Shock: Conduct stress tests that model a scenario where the private credit market seizes up. How would a simultaneous default of several major borrowers impact your liquidity, collateral requirements, and access to capital? Map your direct and indirect exposures to banks with heavy private credit ties.
Scrutinise Debt Structures for PIK and Toggle Features: Treat any exposure to PIK bonds and PIK toggle notes with extreme caution. These instruments are a major red flag for underlying cash-flow problems and significantly increase ultimate loss severity.
Strengthen Focus on Operational Risk: The rapid growth and complexity of private credit can outstrip internal administrative controls. Ensure your recordkeeping, data aggregation, and portfolio administration systems are robust to avoid operational failures that can amplify financial losses.
Recalibrate Risk Models for a New Reality: The assumption that private credit is a stable, low-default asset class is outdated. Recalibrate your internal risk models annually to reflect the current high-leverage, high-interest-rate environment, incorporating leading benchmarks and forward-looking climate and ESG risk factors.
Get help to protect and grow your business faster with BusinessRiskTV
The alternative asset management sector—comprising private equity (PE) funds and shadow banks (non-bank financial intermediaries)—is experiencing a structural liquidity crunch. The recent decision by Apollo Global Management to cap redemptions in its $70 billion Apollo Diversified Credit Fund (ADCR) serves as a critical canary in the coal mine. For business leaders and private investors, this signals a shift from an era of abundant private capital to one of “liquidity illusion,” where assets perceived as liquid are becoming trapped, posing systemic solvency risks to portfolios.
1. The Nature of the Crisis
The current stress is rooted in a fundamental mismatch between asset liquidity and liability structures.
Asset Illiquidity: Private credit funds and shadow banks have deployed capital into assets that are not publicly traded (direct loans, real estate, infrastructure). These assets lack a clearing price and cannot be sold quickly without steep discounts (fire sales).
Liability “Liquidity”: To attract capital, many firms offered investors enhanced liquidity features (quarterly or monthly redemptions) typically reserved for mutual funds, but they invested in illiquid assets.
The Interest Rate Shock: The rapid rise in interest rates over the past 24 months has depressed the underlying value of fixed-income private assets. Simultaneously, it has increased the cost of leverage (debt) that these funds use to juice returns.
2. The Apollo Signal: Why It Matters
Apollo’s decision to gate (cap) withdrawals in its ADCR is not an isolated operational issue; it is a systemic indicator.
The Mechanism: Apollo invoked a “hard close,” limiting redemptions to roughly 20-30% of investor requests.
The Implication: It reveals that even a top-tier asset manager with a pristine balance sheet cannot match investor outflows with cash on hand. If Apollo—one of the largest and most sophisticated players—is facing a liquidity squeeze, smaller private credit firms are likely under severe, unreported stress.
Contagion Risk: This event validates the “first mover advantage” in redemptions. Investors who attempted to exit early may get some capital back; those who wait risk being trapped for years during the fund’s wind-down period.
—
3. Key Risks for Business Leaders & Private Investors
A. Capital Lock-Up & Illiquidity Risk
The most immediate risk is the inability to access capital. Businesses relying on distributions from PE investments for operational cash flow, or investors relying on these funds for retirement or reinvestment, may find their capital frozen for 2 to 5 years beyond the original term.
B. Valuation Shock (The NAV Deception)
Private funds report Net Asset Value (NAV) quarterly, often using subjective models rather than market transactions.
The Risk: As redemptions are capped, the actual value of the underlying assets declines due to forced selling pressure elsewhere in the sector. Investors face “stale pricing”—their statements show stable or positive returns, but the actual liquidation value is significantly lower (10–30% haircuts).
C. Margin Call & Leverage Amplification
Many shadow banks and PE funds utilise subscription lines or asset-backed leverage.
The Risk: If lenders (traditional banks) lose confidence in the collateral due to falling asset prices or redemption gating, they can issue margin calls. This forces funds to sell assets at distressed prices, eroding capital for all investors, including those who did not request redemptions.
D. Operational & Reputational Contagion
For business leaders acting as general partners (GPs) or corporate borrowers:
Risk: If your primary source of debt financing is a shadow bank facing redemption pressures, that lender may cease issuing new loans or may demand early repayment (acceleration) to preserve their own liquidity, jeopardising your business operations.
—
4. Six Risk Management Measures to Protect Capital Today
In response to this growing crisis, business leaders and private investors must shift from a “return-maximisation” mindset to a “capital-preservation-and-liquidity” framework.
1. Implement a “Liquidity Waterfall” Analysis
Do not rely on contractual redemption terms (e.g., quarterly liquidity) alone.
Action: Review the fund’s governing documents for “gating” clauses, side pockets, and suspension of redemption rights. Assume that if a fund’s liquid assets (cash/Treasuries) fall below 10-15% of AUM, gates will be triggered.
For Businesses: Map out your cash flow runway assuming zero distributions from PE holdings for 24 months. Adjust operating budgets to eliminate reliance on this uncertain capital.
2. Prioritise Secondary Market Sales
If you hold interests in private funds (PE, private credit, real estate), waiting for the fund to liquidate is increasingly risky.
Action: Engage secondary market brokers (e.g., SecondMarket, Jefferies) to sell LP interests now. While pricing may be at a discount (85-95 cents on the dollar), this secures liquidity. Waiting for a forced fund restructuring later could result in 50-70 cents on the dollar.
3. De-risk Counterparty Exposure (Shadow Banking)
For business leaders utilising private credit for corporate financing, treat shadow banks as counterparties with higher risk than traditional banks.
Action: Diversify lending relationships. If you have a single private credit facility, secure a backup revolving credit facility (RCF) with a traditional commercial bank. Review loan covenants to ensure that a lender’s internal liquidity crisis does not trigger a subjective acceleration clause.
4. Stress Test Leverage and Subscriptions
Many private investors use subscription lines (leverage against their uncalled capital commitments).
Action: Model a scenario where the fund calls 100% of remaining capital immediately (a “capital call”) while simultaneously distributions drop to zero. Ensure you have sufficient liquid reserves to meet these calls. Failure to do so could result in default and forfeiture of existing equity.
5. Demand Granular Transparency
Standard quarterly reports are insufficient in a liquidity crisis.
Action: Request a “liquidity report” from fund managers detailing:
Percentage of AUM held in cash and government securities.
Current leverage ratios (debt-to-equity).
Concentration of assets facing potential default.
If managers refuse to provide this, treat it as a red flag and accelerate exit plans.
6. Rotate to True Liquidity & Seniority
Reduce allocation to “private” structures and rotate into assets where the liquidity transformation risk is not present.
Action: Shift capital to publicly traded Business Development Companies (BDCs) or listed private equity vehicles rather than closed-end funds. While their share prices may be volatile, they offer daily liquidity.
For Business Treasury: Move excess cash from money market funds that invest in private credit (a growing trend) into Treasury-only money market funds or FDIC-insured sweep accounts. The yield may be slightly lower, but the principal security and liquidity are absolute.
—
Conclusion
The Apollo redemption cap is a definitive signal that the shadow banking system is reaching the limits of its liquidity transformation model. For sophisticated investors and business leaders, the next 12 to 24 months will not be defined by which assets generate the highest IRR, but by which entities survive the liquidity squeeze. Liquidity is no longer a convenience; it is the primary risk management metric. Proactive measures—exiting through secondaries, demanding transparency, and de-risking counterparty exposure—are essential to avoid being trapped in a fund structure that prioritises the manager’s stability over the investor’s access to capital.
The Ukraine conflict represents a catastrophic failure of Western policy, not just Russian aggression. Leaders in the UK, Germany, and France are accountable for a series of critical errors—from pre-war NATO provocation and the Minsk Agreement debacle to slow-walking military aid and sabotaging peace talks. These decisions have prolonged a devastating war, resulting in needless loss of life and squandering billions in public funds. This analysis details the 9 reasons why these policies constitute a profound strategic failure and why citizens must now demand a resolution focused on diplomacy and economic stability over prolonged conflict.
Key Critiques of UK, German, and French Policy on Ukraine
A critical analysis of how leaders in the UK, Germany, and France bear responsibility for prolonging the Ukraine conflict. Explore the 9 key policy failures—from failed diplomacy and economic mismanagement to escalation risks—that have cost hundreds of thousands of lives and billions in taxpayer funds. Learn why citizens must demand accountability and a new path toward peace.
Critics, who come from both the political left and right, often point to a series of pre-war and ongoing policy failures.
1. Pre-War Provocation and Failed Diplomacy (The “Sleepwalking” Critique)
Critique: For years, despite warnings from Russia, the US and key European powers like the UK, France, and Germany expanded NATO eastward. While sovereign nations have the right to choose their alliances, critics argue this was strategically reckless, needlessly threatening Russia’s core security interests and creating a predictable confrontation. This is seen as a failure of statesmanship that boxed all parties into a corner.
Accountability: Leaders are accused of prioritising a hawkish, ideological expansion of Western influence over a pragmatic, security-based diplomacy that could have averted war.
2. The Minsk Agreement Debacle
Critique: The Minsk Agreements (2014-2015), brokered by France and Germany, were meant to bring peace to Donbas. However, recent admissions from figures like former German Chancellor Angela Merkel suggested the agreements were primarily a tool to “give Ukraine time” to build its military. Critics argue this reveals profound bad faith, proving to Russia that diplomatic agreements with the West are not trustworthy, thereby destroying a potential path to peace and making the 2022 invasion seem inevitable from Moscow’s perspective.
3. Slow-Walking Military Aid & “Waging a Slow War”
Critique: Especially in the early stages (and periodically since), Germany, France, and the UK have been accused of “drip-feeding” military aid. They provided just enough to keep Ukraine from collapsing, but not enough to achieve a decisive victory. This is criticized as a strategy that prolongs the war, maximizing Ukrainian casualties and destruction while minimizing direct risk to NATO, effectively “fighting to the last Ukrainian.”
Example: The long, drawn-out debates over delivering tanks, long-range missiles, and aircraft are cited as key examples where hesitation cost lives and strategic advantage.
4. Undermining and Delaying Peace Talks
Critique: In the spring of 2022, peace talks between Ukraine and Russia showed promise. Critics allege that Western powers, particularly the UK under then-PM Boris Johnson, advised Ukraine to break off negotiations, promising full-scale Western support to win back all territory. By taking a maximalist “no negotiation” stance, they are seen as having sabotaged a potential, if imperfect, peace deal that could have saved hundreds of thousands of lives.
5. Economic Mismanagement and the Cost to Citizens
Critique: The billions in aid sent to Ukraine are framed not as noble support, but as a massive transfer of wealth from Western citizens during a cost-of-living crisis. Critics argue this spending fuels inflation, diverts funds from domestic healthcare, education, and infrastructure, and primarily benefits the military-industrial complex, all while the financial burden is borne by the taxpayers of the UK, Germany, and France.
6. Lack of a Clear Strategic Endgame
Critique: Two years into the conflict, there is no publicly defined strategic goal for the war. Is the aim to return to 1991 borders? 2014 borders? Merely weaken Russia? This lack of a clear, achievable political objective is a massive strategic failure. It commits these nations to an open-ended conflict with no exit strategy, guaranteeing further waste of lives and money without a defined concept of “victory.”
7. Escalation Risks and Brinksmanship
Critique: By continuously pushing the boundaries of military aid—from artillery to tanks to long-range missiles—these leaders are playing a dangerous game of brinksmanship. Critics argue they are ignoring the real and existential risk of a direct NATO-Russia war, which could escalate to nuclear conflict. The responsibility for managing this risk lies with the major Western powers, and their current policies are seen as recklessly increasing it.
8. The “Double Standard” on International Law
Critique: This argument, often from the left, states that the UK, France, and Germany apply international law selectively. They rightly condemn Russia’s invasion but have historically ignored or participated in violations (e.g., Iraq, Libya, Yemen). This hypocrisy, critics argue, undermines the moral high ground and the very rules-based order they claim to be defending, making their stance seem more about geopolitical power than principle.
9. Neglecting Diplomacy as a Tool
Critique: The current policy is almost entirely militaristic. Critics argue that leaders in Berlin, Paris, and London have a responsibility to pair military support with aggressive, creative diplomacy. By refusing to seriously explore diplomatic channels, ceasefires, or potential compromises, they are choosing a path of endless attrition over statecraft, ensuring the continued loss of life and economic damage.
Why Citizens of These Countries Should Act
Based on these critiques, the argument for citizen action is clear:
Sovereignty and Consent: The governments of the UK, Germany, and France are acting in the name of their citizens. Therefore, citizens have a democratic right and responsibility to scrutinize these policies and their costs.
Direct Impact: The citizens of these nations are directly paying the price through higher taxes, inflated living costs, and diverted public funds. Their security is also being put at risk through escalation.
Correcting a Failed Policy: If the current path is seen as a “policy mistake” that is wasting lives and treasure without a realistic chance of a satisfactory outcome, then public pressure is the primary democratic mechanism to force a change in course towards a strategy that prioritises peace and diplomacy.
Get help to protect and grow your business faster with BusinessRiskTV
China’s near-monopoly on rare earth processing is the new battleground in the US-China trade war, threatening global supply chains for EVs, wind turbines, and high-tech defense. Learn why this chokepoint is critical and the 6 essential business risk management steps to protect your enterprise from crippling mineral shortages and price volatility.
Rare Earth Minerals: The Critical Chokepoint Fuelling the US-China Trade War
The global supply chain for Rare Earth Elements (REEs) is a major point of economic and geopolitical vulnerability, now intensifying the trade war between the US and China. These 17 elements are not actually rare in the Earth’s crust, but finding them in economically viable, concentrated deposits is unusual, and the processing expertise is highly consolidated. The world’s dependency on a single source for these materials—vital for high-tech industries and national security—has made them a powerful geopolitical leverage tool.
China’s Dominance: The Supply Chain Chokepoint
Rare earth minerals are indispensable in modern technology. They form the basis of powerful permanent magnets used in Electric Vehicles (EVs), wind turbines, smartphones, advanced military equipment (like missiles and fighter jets), and numerous other high-tech consumer electronics.
Predominant Sources and Control
The problem isn’t the physical mining of the minerals, but the complex and often environmentally taxing separation and processing into usable elements and magnets.
Stage of Supply Chain China’s Estimated Global Control
China Mining ∼70%
China Separation & Processing ∼90%
China Magnet Manufacturing ∼93%
China has held indisputable dominance over the rare earth supply chain since the 1990s, making it the primary global source of refined REEs. The US, which was once the leading global producer, now imports a significant portion of its rare earth oxides, much of it directly or indirectly sourced from China. This dominance provides Beijing with a potent economic leverage tool.
Rare Earths as a Weapon in the Trade War
The US-China trade war, initially focused on tariffs and intellectual property, has now fundamentally shifted to control over critical raw materials.
Geopolitical Leverage
China has weaponised its dominance by implementing export controls on rare earths and related processing technology. These actions directly target the US industrial and defense base, which relies on these materials.
Export Restrictions: China has expanded restrictions to include magnets containing even trace amounts of Chinese-sourced REEs, or products manufactured using Chinese refining technology. These new controls effectively grant China veto power over key global supply chains, including advanced semiconductors and EVs.
National Security Focus: Beijing justifies the moves by citing the need to “protect its national security and interests” and prevent the “misuse of rare earth materials in military and other sensitive sectors.” These controls force foreign companies, including those in India’s auto industry, to provide end-use certifications to ensure the materials aren’t re-exported to the US for military applications.
US Response: The US has retaliated with threats of steep tariffs on Chinese goods and is aggressively pursuing domestic production and ‘friend-shoring’ initiatives with allies like Australia, Canada, and Vietnam to diversify its supply chain away from China. This intense back-and-forth confirms that rare earths are not just a trade issue but a core strategic and national security concern.
6 Business Risk Management Tips for Supply Chain Resilience
Businesses reliant on products that use rare earths (like EV manufacturers, electronics firms, and defense contractors) must take proactive steps to mitigate this escalating supply chain crisis.
Supply Diversification: Actively seek and activate alternative sources of REE ores, refining capacity, and finished components from politically stable regions (e.g., Australia, US domestic production, or other allied nations).
Multi-Tier Risk Assessment: Go beyond direct suppliers (Tier 1) to map and assess risks across all tiers of your supply chain (Tiers 2 and 3) to identify where reliance on China’s REE processing truly lies.
Strategic Stockpiling: Maintain a buffer stock of critical rare earth materials or high-value components to hedge against short-term disruptions, price spikes, and abrupt export license changes.
Invest in Recycling/Circular Economy: Prioritise R&D and investment in RE-free substitutes and urban mining (recycling of rare earths from end-of-life products like batteries and magnets) to create a sustainable, non-China-dependent source.
Conduct Scenario Planning: Run ‘what-if’ exercises based on geopolitical events (e.g., complete Chinese export ban, 100% US tariffs) to understand potential financial and operational implications and prepare rapid response plans.
Continuous Monitoring & Traceability: Implement a robust supply chain risk management system to continuously monitor geopolitical, regulatory, and financial risks for all key suppliers and raw material sources.
Get help to protect and grow your business faster with BusinessRiskTV
Don’t just survive—thrive. In today’s volatile UK market, being resilient isn’t enough. Discover the anti-fragility mentality, a powerful concept that helps businesses grow stronger from shocks and uncertainty. Our guide reveals the dangers of feeling too scared to grow, explains why positively fighting back against business fears works better, and provides 9 practical risk management strategies to build a more robust, adaptable, and profitable business. Learn how to transform every crisis into a competitive advantage.
Discover how an anti-fragility mentality can help your UK business thrive on stress and volatility. Learn why fear of growth is dangerous and get 9 practical risk management strategies to build a more robust, adaptable, and profitable company.
Anti-Fragility Mentality: The UK Business Guide to Thriving on Volatility 🇬🇧
In the complex and unpredictable world of business, it’s not enough to be resilient or robust; you must be anti-fragile. This is a concept, popularised by author Nassim Nicholas Taleb, that suggests some systems, like a business, don’t just withstand shocks—they actually get stronger because of them. While a resilient company recovers from a crisis, an anti-fragile one learns, adapts, and improves. Instead of just surviving, an anti-fragile business uses volatility, uncertainty, and stress as fuel for growth. This is especially relevant for UK businesses navigating a post-Brexit, globalised, and tech-driven market.
The Dangers of Business Fear and Over-Cautiousness
When leaders are too scared to grow, their business becomes fragile. Fear of failure or even fear of success can lead to a state of paralysis. Instead of embracing opportunities, a business with a risk-averse culture will hesitate, self-sabotage, and miss out on potential gains. This mindset can:
Stifle innovation: You avoid new technologies, markets, or product lines, leaving you vulnerable to competitors who are bolder.
Prevent scalability: Your business systems, processes, and team structures become too rigid to handle growth, leading to spiralling costs and poor service if demand increases.
Create dependency: Over-reliance on a single client, supplier, or revenue stream makes the business incredibly fragile.
Damage morale: A culture of fear can demotivate employees and discourage them from taking initiative.
Expose you to a slow decline: While you might avoid a sudden crisis, a cautious approach often leads to a gradual loss of market share and relevance.
Why Positively Fighting Back Against Crisis Works Better
An anti-fragile business doesn’t just react to a crisis; it uses the crisis to its advantage. Instead of a defensive mindset, it adopts an offensive one, turning problems into opportunities. This approach works better because:
It forces innovation: A crisis can be a powerful catalyst for change, forcing you to find creative solutions you wouldn’t have considered otherwise.
It builds stronger systems: A crisis reveals weaknesses. By addressing these weak points, you build more robust, efficient, and reliable systems for the future.
It strengthens relationships: Transparent communication and proactive problem-solving during a crisis builds trust with employees, customers, and partners.
It creates a competitive advantage: While your competitors are busy recovering, you’re using the disruption to pull ahead, secure new markets, or attract talent.
Who Can Help You Take More Calculated Risks
Taking calculated risks is a team sport. While the final decision rests with the leadership, a smart leader leverages the entire business to inform their choices. Key roles that can help you become more anti-fragile include:
The Finance Team: Your finance department is crucial. They provide the data and analysis needed to understand the potential financial impact of a risk.
Embrace Optionality: Have multiple, low-risk options available. For example, explore several new markets with a small investment rather than committing to one with a large one.
Redundancy is a Virtue: Don’t rely on a single supplier or a single server. Create backups and redundancies to prevent single points of failure.
Conduct “Pre-Mortems”: Instead of a post-mortem after failure, imagine a project has failed and work backwards to identify the reasons. This helps anticipate risks before they occur.
Decentralise Authority: Empower smaller teams to make decisions. This allows for faster responses to local challenges and opportunities.
Maintain a Cash Buffer: Keep enough cash on hand to cover a significant period of low revenue. This financial buffer is the bedrock of anti-fragility.
Gamify Risk Management: Use internal games or simulations to train your team on how to respond to unexpected events, building both muscle memory and a proactive mindset.
Diversify Your Team’s Skillset: Hire for versatility and adaptability. A team with diverse skills is more likely to find creative solutions during a crisis.
Build Strong Stakeholder Relationships: Foster trust with your customers, suppliers, and investors. Strong relationships provide a support network that is invaluable in a downturn.
Get help to protect and grow your business faster with BusinessRiskTV
The Bank of England’s recent record £87.15 billion repo allotment, a tool used to provide liquidity to banks as the central bank reduces its bond holdings, could signal underlying stress in the UK banking sector. This growing reliance on the central bank for funds raises a red flag for the financial stability and economic safety of the UK. Discover what this means for the wider economy and learn six crucial risk management strategies every business leader should implement now to protect and grow their enterprise more resiliently in an uncertain economic climate.
Bank of England Allots Record £87.15 Billion in Repo Operation: What It Means for UK Business Risk
The Bank of England’s Record Repo Allotment: A Warning for UK Business? 🚨
The Bank of England recently allotted a record £87.15 billion in a short-term repo operation, a move that provides a substantial injection of liquidity into the UK’s banking system. While this may seem like a routine technical adjustment by the central bank, the increasing reliance on these operations could be a significant red flag for the safety of the UK’s financial system and wider economy.
What Is a Repo Operation and Why Is This a Red Flag?
A repo (repurchase agreement) is essentially a short-term loan. The Bank of England lends money to commercial banks and in return, the banks provide high-quality assets (like government bonds) as collateral. The Bank’s increasing use of this tool is directly linked to its Quantitative Tightening (QT) programme, which involves selling off the government bonds it bought during the era of Quantitative Easing (QE). The purpose of these repo operations is to prevent a potential liquidity squeeze in the financial system as the central bank reduces its balance sheet.
The record allotment is a red flag for a few key reasons:
Growing Illiquidity: The fact that banks are demanding a record amount of funds from the central bank suggests they may be struggling to find liquidity elsewhere in the market. This could indicate underlying stress in the banking sector and a reluctance among banks to lend to each other.
Systemic Risk: This reliance on the Bank of England for funding could be a sign of increased systemic risk. If a major bank were to face a sudden liquidity crisis, the central bank would be its lender of last resort. The increasing size of these operations shows the potential scale of that reliance.
Uncertainty and Instability: A record-breaking allotment, particularly one that exceeds a recent record, creates a narrative of growing instability. This can erode confidence in the banking system and the wider economy, making businesses and investors more hesitant to spend and invest. This uncertainty trickles down to businesses and consumers, affecting everything from investment decisions to household spending.
6 Risk Management Measures for Businesses
In an environment of economic uncertainty, business leaders must be proactive to protect their organisations. Here are six essential risk management measures to enhance resilience:
Strengthen Cash Flow and Liquidity:Cash is king, especially in a downturn. Focus on optimising your working capital by accelerating accounts receivable, negotiating longer payment terms with suppliers, and maintaining a healthy cash reserve. Create detailed cash flow forecasts to anticipate potential shortfalls and manage expenses.
Diversify Revenue Streams and Supply Chains:Over-reliance on a single product, service, customer, or supplier is a major vulnerability. Actively seek new markets, customer segments, and partnerships. For your supply chain, identify alternative vendors and consider strategies like near-shoring or holding a small buffer of critical inventory to mitigate potential disruptions.
Manage Debt and Capital Expenditure Wisely: During uncertain times, it is crucial to avoid taking on excessive debt. Evaluate all major capital expenditure projects. Postpone or cancel non-essential investments that don’t directly contribute to immediate revenue or operational efficiency.
Review and Optimise Operational Costs:Take a hard look at all business expenses. Eliminate unnecessary costs without sacrificing the quality of your product or service. This could involve renegotiating contracts, leveraging technology for greater efficiency, or consolidating services. The goal is to create a leaner, more resilient cost structure.
Why the Bank of England’s Record Repo Allotment Is a Red Flag
The Bank of England’s record-breaking repo allotment is a significant red flag because it points to potential underlying stress and growing liquidity issues within the UK banking system. While repo operations are a standard tool for central banks to manage monetary policy, the increasing size of these allotments, especially in the context of the central bank’s quantitative tightening (QT) programme, reveals a deeper problem.
Growing Illiquidity and Inter-bank Distrust: The primary role of a central bank’s repo operation is to provide liquidity. A record amount being requested by commercial banks suggests they are struggling to secure the funds they need from each other. In a healthy banking system, banks would lend to one another in the inter-bank market. The fact that they are turning to the Bank of England in such high volumes could indicate a breakdown of trust between financial institutions, which is a classic symptom of a stressed system.
Systemic Risk: The increasing reliance on the central bank for funding raises concerns about systemic risk. Systemic risk is the risk of a collapse of an entire financial system due to the failure of one or more institutions. If a significant portion of the banking sector is dependent on the Bank of England for liquidity, a sudden shock or disruption could have a cascading effect across the entire system. This over-reliance makes the financial system less resilient and more vulnerable to unforeseen events.
Uncertainty and Economic Instability: A record repo allotment creates a sense of uncertainty and instability in the market. The public and investors may interpret this as a signal that the banking system is not as robust as it appears. This loss of confidence can have a tangible impact on the wider economy. It can lead to a tightening of lending standards, making it harder for businesses and households to access credit, and it can also deter investment, ultimately slowing down economic growth. The large allotment, therefore, isn’t just a technical exercise; it’s a barometer of growing financial vulnerability in the UK.
Read more free business risk management articles and view videos
6 Essential Business Risk Management Measures for UK Business Leaders
In today’s complex and uncertain economic environment, proactive business risk management is no longer an option—it’s a necessity. UK business leaders must move beyond a reactive approach and build genuine resilience into the core of their operations. Here are six essential measures to take action on now.
Optimise working capital: Focus on accelerating accounts receivable by offering incentives for early payment or enforcing stricter payment terms. At the same time, negotiate more favourable payment terms with your suppliers to extend your accounts payable.
Create robust cash flow forecasts: Use financial modelling and scenario planning to predict potential cash shortfalls. This will help you anticipate problems and give you time to secure financing or make cost adjustments before a crisis hits.
Maintain a cash reserve: Aim to build a buffer of cash sufficient to cover at least three to six months of operating expenses. This reserve acts as a critical safety net against unexpected disruptions.
2. Diversify Revenue Streams and Supply Chains
Over-reliance on a single customer, product, or supplier is a major vulnerability. Diversification builds a more robust and flexible business model.
Review and diversify your supply chain: Identify and vet alternative suppliers, especially for critical raw materials or components. Consider a dual-sourcing model or incorporating local suppliers to mitigate risks from global transport issues or geopolitical events.
3. Conduct Scenario Planning and Stress Testing
Don’t wait for a crisis to expose your weaknesses. Proactive scenario planning allows you to test your business model against a range of potential threats.
Identify key risks: Create a comprehensive risk register that outlines potential risks (e.g., economic downturn, supply chain disruption, cyber-attack) and their potential impact.
High levels of debt can become a significant burden in a tightening credit environment.
Limit new borrowing: Be cautious about taking on new debt, particularly for non-essential projects. Evaluate every borrowing decision based on its potential return on investment and its impact on your balance sheet.
Re-evaluate capital projects: Postpone or cancel major capital expenditures that are not critical for business operations or do not have a clear and immediate path to profitability. Prioritize investments that enhance operational efficiency and resilience.
5. Review and OPTIMISE Operational Costs
A lean and efficient cost structure improves profitability and allows you to better weather economic storms.
The UK Office for Budget Responsibility (OBR) has been widely criticised for its consistently inaccurate economic forecasts over the past decade, particularly its overly optimistic predictions for productivity growth. This inaccuracy is a significant business risk because UK economic policy is heavily reliant on the OBR’s projections, which can lead to abrupt and disruptive policy changes. Businesses can’t change the OBR, but they can improve their risk management by focusing on scenario planning, diversifying operations, strengthening financial controls, and investing in organisational agility to better withstand external shocks and policy shifts.
UK OBR Forecasts: A Decade of Inaccuracy and the Risk for UK Businesses
The UK Office for Budget Responsibility (OBR) has been criticised for its economic forecasts over the last 10 years, which have often been inaccurate. While it has performed better than the Treasury did before its creation, it has persistently overestimated productivity growth, a key factor in its forecasts. This inaccuracy is a significant concern because UK economic policy, particularly the government’s fiscal rules, is heavily tied to the OBR’s projections.
Accuracy of OBR Forecasts
The OBR was established in 2010 to provide independent and credible economic and fiscal forecasts, preventing the political manipulation that was common when the Treasury produced its own projections. While the OBR has been praised by institutions like the International Monetary Fund (IMF) and is considered a successful innovation, its forecasts have been far from perfect. The OBR itself acknowledges that the difference between its forecasts and actual economic outcomes can be significant, especially during periods of economic turbulence.
A major and consistent issue is the OBR’s over-optimistic forecast for productivity growth. This persistent overestimation has a cascading effect on other economic projections. Lower-than-expected productivity means slower wage growth, reduced tax revenues from income and corporation tax, and weaker household spending, which in turn reduces VAT receipts. These factors make it harder for the government to meet its fiscal targets without raising taxes or cutting spending.
The OBR’s Influence on UK Economic Policy
UK economic policy is heavily tied to OBR projections for a few key reasons:
Fiscal Rules: The government sets fiscal rules, such as targets for debt and borrowing, which are judged against the OBR’s forecasts. The OBR’s verdict on whether these rules are being met becomes the primary driver of the Chancellor’s Budget and fiscal decisions. This creates a system where a small change in the OBR’s forecast, often called “fiscal headroom,” can lead to significant and often rushed policy adjustments.
Credibility: The OBR’s independence is crucial for maintaining the UK’s financial credibility in the eyes of international investors and markets. The infamous “mini-budget” of 2022, which was not accompanied by an OBR forecast, led to a sharp drop in the pound and a rise in government borrowing costs. This event underscored the importance of the OBR’s role in providing market reassurance and preventing politically motivated “wishful thinking” from undermining economic stability.
Alternatives to the OBR’s Dominance
Ditching the OBR’s power over UK economic policy would be a high-risk move, but alternatives could include a more flexible or multi-faceted approach to fiscal policy.
Diverse Forecasting Sources: The government could rely on a broader range of economic forecasts from institutions like the Bank of England (BoE), the Institute for Fiscal Studies (IFS), and private sector consultancies. This would provide a more balanced view and reduce the over-reliance on a single body’s projections.
Reform of Fiscal Rules: A more desirable alternative might be to reform the fiscal framework itself. The current system, which focuses on a narrow “fiscal space” against a single forecast, leads to frequent and disruptive policy changes. A new framework could focus on a longer-term strategy, such as a medium-term program for fiscal consolidation, rather than a narrow-minded adherence to a specific debt target at a single point in time.
Business Risk Management Strategies
Business leaders in the UK can’t control the OBR’s forecasts, but they can adapt their risk management strategies to mitigate the impact of inaccurate projections and subsequent policy volatility.
Embrace Scenario Planning: Don’t rely on a single economic forecast. Develop and analyse a range of best-case, worst-case, and most-likely scenarios for economic growth, inflation, and interest rates. This allows for a more resilient strategy that can adapt to different economic realities.
Focus on Internal Data:Prioritise your own company’s data and market analysis over public economic forecasts. Monitor your customers, supply chains, and workforce closely. This provides a more accurate picture of the direct risks and opportunities facing your business.
Diversify and Build Resilience: Reduce your reliance on a single market, product, or supplier. A diversified business model, a strong balance sheet, and a resilient supply chain will help you withstand external shocks, regardless of what the OBR is forecasting.
Engage with Policy: Stay informed about potential government policy changes driven by the OBR’s forecasts. Engage with trade associations and professional bodies to have a voice in shaping policy and to anticipate regulatory shifts that could impact your business.
Strengthen Financial Controls: Given the potential for unexpected tax increases or spending cuts, maintain a robust financial management system. This includes managing cash flow, hedging against currency fluctuations, and securing credit lines to provide a buffer against economic volatility.
Invest in Agility: Foster a culture of agility and rapid response within your organisation. This allows you to quickly pivot your strategy, adjust pricing, or change operational models in response to sudden policy changes or economic shifts. This proactive approach minimises the time lag between an external shock and your company’s response.
The Office for Budget Responsibility (OBR) has a track record of being overly optimistic in its economic forecasts, particularly concerning a few key metrics. This persistent overestimation isn’t a minor issue; it has a significant knock-on effect on the government’s fiscal decisions and, by extension, the entire UK economy.
The most glaring and consistent error is the overestimation of productivity growth. Productivity, defined as the output per hour worked, is the fundamental driver of long-term economic growth. When the OBR predicts that productivity will rise faster than it actually does, it creates a cascade of false expectations.
Here’s how this over-optimism creates a problem:
Inflated Tax Revenue Projections: Higher productivity is expected to lead to higher wages and company profits. The OBR’s models, therefore, forecast larger tax receipts from income tax, corporation tax, and National Insurance. When productivity growth falls short, these tax revenues also underperform, creating a fiscal black hole.
Misleading “Fiscal Headroom”: The difference between the government’s borrowing target and the OBR’s forecast for borrowing is known as “fiscal headroom.” When the OBR is overly optimistic, this headroom appears larger than it is in reality. This can tempt Chancellors to make unfunded spending pledges or tax cuts, only to discover later that the money isn’t there, forcing a difficult U-turn or a “mini-budget” style crisis.
Policy Instability: The OBR’s forecasts are a major input for government fiscal rules. When these forecasts prove inaccurate, it leads to a cycle of constant policy adjustments. This creates an unstable and unpredictable economic environment for businesses, making long-term planning difficult and discouraging investment.
Why UK Economic Policy is Trapped by OBR Projections
The OBR was created in 2010 to depoliticise economic forecasting and provide independent, credible analysis for the government. In many ways, it has succeeded, preventing the return to a system where the Treasury could be accused of creating politically convenient, but unrealistic, numbers. However, this success has created an almost unbreakable link between the OBR’s forecasts and the government’s fiscal policy.
This dependency is best understood through the UK’s system of fiscal rules. Governments set themselves targets for debt and borrowing, and these targets are formally judged against the OBR’s forecasts. The OBR’s assessment of whether a government is “on track” to meet its own rules becomes the single most important factor shaping fiscal policy.
Here’s why this creates a trap:
The “Fiscal Headroom” Squeeze: Chancellors of the Exchequer are in a constant battle to meet their fiscal targets, often by a razor-thin margin. The OBR’s forecasts for the economy—especially for productivity and growth—determine how much “fiscal headroom” (the buffer between current policy and the fiscal rules) the government has. A minor downgrade in the OBR’s forecast, often costing just a few billion pounds, can be enough to wipe out this headroom, forcing the Chancellor to scramble for new tax rises or spending cuts to stay compliant.
A Focus on the Short Term: The cycle of semi-annual OBR forecasts encourages a short-term, reactive approach to policymaking. Instead of developing a long-term, strategic vision for the economy, the government’s focus is on making the numbers “add up” for the next OBR report. This can lead to rushed, poorly thought-out decisions that prioritize meeting a forecast over sound long-term economic planning.
The Political Consequences of Defiance: The 2022 “mini-budget” provides a stark example of what happens when a government tries to sidestep the OBR. The lack of an independent forecast to accompany the radical tax-cutting agenda spooked financial markets, leading to a collapse in the pound and a sharp rise in government borrowing costs. This event cemented the OBR’s power, showing that its credibility is crucial for maintaining market confidence.
Ultimately, while the OBR provides a valuable service by preventing political manipulation, its central role in the fiscal framework makes the UK economy highly vulnerable to its forecasts. Businesses and individuals are left to navigate the consequences of a system where a single set of numbers can dictate major policy changes, from tax hikes to cuts in public services.
Alternatives to the OBR: A New Path for UK Fiscal Policy?
The UK’s reliance on the OBR’s single set of forecasts for its fiscal rules has created a system that is brittle and prone to sudden, reactive policy changes. Many economists and think tanks, including the Institute for Government and the New Economics Foundation, argue that a more robust and flexible framework is needed. This would not mean getting rid of the OBR entirely, but rather changing its role and the rules it judges the government against.
Instead of the current system, a new path could include:
A “Strategy-First” Approach: The government would first articulate its long-term fiscal strategy, outlining its objectives for spending, taxation, and debt over a 10- or 20-year horizon. The OBR’s role would then shift from simply validating the numbers to providing an independent assessment of whether the government’s policies are consistent with that stated strategy. This would encourage a focus on the bigger picture rather than short-term compliance.
Multiple Forecasts and Broader Scrutiny: The government could be required to publish its own internal forecasts alongside the OBR’s. Additionally, a new, independent body—perhaps a “Fiscal Policy Committee” similar to the Monetary Policy Committee at the Bank of England—could be introduced. This committee would review both the Treasury’s and the OBR’s forecasts, fostering a more open debate and allowing for a greater degree of professional judgment.
Reforming the Fiscal Rules Themselves: The rules could be made more flexible to account for economic shocks. For example, rather than a rigid target for debt to fall in a specific year, the rules could focus on a rolling, long-term trend. This would give the government more breathing room to respond to a recession or other unexpected events without being forced into immediate, and potentially damaging, tax hikes or spending cuts. Another alternative is to move beyond just targeting debt and borrowing and instead focus on a broader measure of the government’s balance sheet, including public sector assets.
These alternatives aim to replace the current system’s reliance on a single, fallible forecast with a framework that is more resilient, transparent, and focused on genuine long-term fiscal sustainability.
Read more free business risk management articles and view videos
Six Ways to OBR-Proof Your Business Risk Management
The unpredictability of UK economic policy, largely driven by the OBR’s frequently inaccurate forecasts, is a strategic risk that business leaders cannot ignore. While you can’t control the government’s fiscal decisions, you can build a more resilient and adaptable business model that is less vulnerable to these external shocks. Here are six actionable ways to OBR-proof your risk management strategy:
Embrace Scenario Planning, Not Single Forecasts: Ditch the habit of basing your entire business plan on a single, optimistic economic forecast. Instead, develop a range of plausible scenarios. What happens if the OBR cuts its productivity forecast? What if inflation stays stubbornly high, forcing the Bank of England to keep interest rates elevated? Create financial models for best-case, worst-case, and most-likely scenarios, and have clear contingency plans for each. This allows you to react quickly and confidently when the economic winds shift.
Focus on Your Own Data as the “Truth”: Public economic data can be noisy and subject to revision. While it provides context, the most reliable information for your business is your own data. Prioritise your internal metrics: customer buying habits, sales trends, inventory turnover, and supply chain performance. Use this real-time, granular data to make strategic decisions rather than waiting for the next OBR report. This internal focus makes your business more agile and responsive to the realities on the ground.
Build Financial Buffers and Flexible Budgets: In an environment of potential fiscal instability, cash is king. Maintain healthy cash reserves and establish strong relationships with banks to secure flexible lines of credit. Move away from rigid annual budgets towards a system of rolling forecasts that are reviewed and updated on a monthly or quarterly basis. This flexibility allows you to adjust spending, investment, and hiring plans in response to the latest economic signals, rather than being locked into an outdated plan.
Strengthen and Diversify Your Supply Chain: A single, fragile supply chain is a significant vulnerability. OBR-driven policy shifts can lead to unexpected tariffs, regulatory changes, or even a sudden drop in domestic demand that impacts your suppliers. Actively work to diversify your suppliers, both geographically and in terms of the companies you work with. Building multiple supplier relationships and having contingency plans in place can insulate your operations from external shocks.
Invest in Agility and Cross-Training: The ability to pivot your business model is a critical form of resilience. Invest in technology and employee training that allows your workforce to be more flexible and adaptable. Cross-training employees to perform multiple roles, embracing automation for routine tasks, and having a clear communication plan for times of crisis can help your business respond effectively to sudden changes in consumer demand or government regulation.
Actively Engage with Policy and External Expertise: While you can’t control policy, you can be better prepared for it. Stay informed about the government’s fiscal plans and the OBR’s commentary. Join trade associations or professional bodies that have a voice in shaping policy. Consider working with external strategic advisors who can provide an objective, expert perspective on the risks and opportunities presented by the UK’s economic and political landscape. This proactive engagement can help you anticipate regulatory changes and position your business to thrive in a volatile environment
UK OBR Forecasts: A Decade of Inaccuracy and the Risk for UK Businesses
The PIK Debt Delusion: A crisis is hiding in plain sight. Discover why Payment in Kind Bonds and Toggles are creating a dangerous systemic risk, masking a liquidity crisis, and threatening the stability of the Western economy. Your business could be next. #FinancialRisk #PIKBonds #CorporateDebt
The PIK Debt Delusion: A Crisis Hiding in Plain Sight
A financial reckoning is coming, and it’s being masked by a subtle, sinister trend. Western businesses are increasingly reliant on exotic debt instruments known as Payment in Kind (PIK) Bonds and PIK Toggles. Don’t let the complex names fool you; these are financial time bombs ticking beneath the foundations of our economy. If you’re a business leader not paying attention, you’re willfully ignoring the red flags that signal a coming liquidity crisis.
The Financial Opium of PIK Bonds
A Payment in Kind (PIK) Bond is a type of debt security where the issuer can pay interest not with cash, but by issuing more debt. Think of it as paying your credit card bill with a brand-new credit card. The principal amount of the bond, and the debt you owe, simply grows.It’s the ultimate “kick the can down the road” strategy, allowing a company to defer immediate cash outflows and pretend to be financially healthy when it’s not.
A PIK Toggle is even more insidious. It’s a provision in a bond that gives the company a choice (“toggle”) between paying interest in cash or paying it in kind (with more debt).This allows a company to conserve cash during periods of financial stress, such as a downturn or a failed business venture, by simply choosing the PIK option.It’s a short-term fix that compounds a long-term problem.
The problem with both is the same: the interest on the deferred debt compounds, often at a higher rate than a traditional bond.The company’s debt load balloons, and what started as a manageable loan can quickly become an insurmountable mountain of obligation.
The Rising Tide of Deferral
The rising use of these instruments is a direct symptom of a global economy addicted to easy money and low interest rates. For years, companies borrowed at near-zero rates, building fragile, over-leveraged balance sheets. Now, as central banks raise rates, many of those companies can’t afford their cash interest payments.
Rather than facing the music and restructuring or declaring bankruptcy, they’re turning to PIK debt.It’s a Hail Mary pass for cash-strapped businesses, particularly in sectors like private equity and leveraged buyouts, where massive debt loads are common. The recent increase in PIK deals and the overall percentage of PIK income in private credit portfolios are alarming indicators of widespread financial stress that is being conveniently swept under the rug.
Why You Should Be Worried
Business leaders in Western economies should be gravely concerned by this trend for several reasons.
1. The Shadow Default Rate
The rising use of PIK debt is masking a hidden default rate. A company making PIK payments isn’t technically defaulting on its loan, so it’s not counted in official default statistics. But it’s a default in everything but name. The company can’t pay its interest in cash, which is a classic sign of financial distress. The real, underlying health of a company or an entire sector is being obscured, creating a dangerous mirage of stability.
2. The Illusion of Liquidity
PIK debt creates a false sense of liquidity. A company might have enough cash on its balance sheet to operate day-to-day, but that cash isn’t going toward its debt obligations. This can lead to reckless behaviour, such as over-investment or the avoidance of necessary layoffs or operational cuts. It’s a classic case of borrowing from the future to survive today, and that bill will come due.
3. The Unseen Avalanche of Debt
The compounding nature of PIK debt means that a company’s total obligation can skyrocket unexpectedly.As the principal amount grows with each deferred payment, the final repayment at maturity becomes colossal. If a business hasn’t achieved a massive increase in cash flow by then, it will be faced with a refinancing crisis or an outright default on a scale far larger than its original loan. The longer a company relies on PIK, the harder the eventual fall.
4. Systemic Risk
The widespread adoption of PIK debt creates systemic risk. If a significant number of over-leveraged companies, all using PIK, face maturity dates at the same time, it could trigger a wave of defaults that cascades through the financial system.Lenders, from private credit funds to business development companies (BDCs), could face a liquidity crunch as their promised cash returns evaporate.
In short, the rise of PIK bonds and toggles is not a sign of financial innovation; it’s a sign of financial desperation. It’s a warning shot that the post-pandemic, high-interest-rate environment is a reckoning for businesses that gorged on cheap debt. If you’re a business leader, you need to look past the rosy, short-term cash flow statements and see the mountain of deferred debt for what it is: a clear and present danger to your business and the broader economy.
Read more :
The Dangerous Allure of “Paying with More Debt”
In the corporate world, the phrase “out of sight, out of mind” has become a dangerous business strategy, and Payment in Kind (PIK) Bonds are its most potent tool. These aren’t just financial instruments; they’re the embodiment of a company’s ability to defer its day of reckoning. A traditional bond requires a company to pay interest in cash, a constant, tangible reminder of its financial obligations. This discipline forces leaders to be prudent, to manage cash flow tightly, and to make tough decisions.
PIK bonds, on the other hand, offer a seductive escape. Instead of paying with cash, a company can simply increase the principal of the loan. It’s like a credit card that, instead of a minimum payment, just adds the interest you owe to your total debt. The immediate pressure is gone. The company’s balance sheet appears flush with cash, and its leaders can continue their operations as if nothing is wrong. This is the PIK Toggle in action, a switch that allows a company to conserve cash during a downturn or a period of poor performance.
But this is a delusion. The interest doesn’t just disappear; it compounds, often at a higher rate than the original debt. What begins as a manageable loan can quickly balloon into an insurmountable mountain of debt. The company is, in effect, borrowing from its future to pay for its present, creating a precarious financial structure that is fundamentally unsustainable. This practice isn’t a sign of financial innovation; it’s a desperate measure, a symptom of a company’s inability to generate the cash required to meet its obligations.
Why This Financial Smokescreen Masks a Liquidity Crisis
The rise of PIK debt is not just a problem for over-leveraged companies; it’s a systemic risk that creates a dangerous illusion for the entire market. This financial smokescreen hides a fundamental truth: a growing number of businesses are cash-flow negative when it comes to servicing their debt. By deferring cash interest payments, they can project a picture of short-term stability that simply doesn’t exist.
This is the very essence of a liquidity crisis in the making. Liquidity is the ability to meet short-term financial obligations. A company that has to pay its interest in kind is, by definition, unable to meet that obligation with cash. Yet, because a PIK payment isn’t technically a default, it doesn’t show up in traditional default rates. The market and investors, relying on these flawed metrics, can be lulled into a false sense of security. They might see a company with a manageable cash balance and no declared defaults, unaware that this company is hemorrhaging cash from its core operations and can’t even afford to pay its creditors.
This opacity creates a domino effect. Lenders, from private credit funds to institutional investors, may be holding assets that are effectively non-performing but are still being classified as sound. When these PIK bonds finally mature, the combined principal and accrued interest will create a colossal repayment obligation. If the company still can’t generate the necessary cash, a wave of real, hard defaults could erupt, threatening the stability of the entire financial ecosystem. This is a hidden insolvency crisis, lurking just beneath the surface of what appears to be a healthy and resilient market.
The Looming Avalanche: How PIK Debt Creates Unseen Systemic Risk
The greatest danger of the PIK trend isn’t what it does to a single company, but its insidious effect on the broader financial system. It’s a classic case of systemic risk, where the failure of one institution can trigger a cascade of failures throughout the market. The widespread use of PIK debt is creating a house of cards, built on a foundation of deferred obligations and inflated valuations.
Think of the financial system as a series of interconnected pipes. In a healthy system, cash—the lifeblood of the economy—flows from one point to another in the form of interest payments. PIK debt, however, is a clog in the system. It allows a company to conserve cash, but that cash-flow problem is simply transferred to the lenders. As more and more companies rely on PIK, a significant portion of the financial system’s promised returns become nothing more than a swelling number on a spreadsheet.
This is particularly dangerous in the private credit market, which has grown exponentially in recent years. Many private credit funds, business development companies (BDCs), and institutional investors like pension funds and insurers are heavily exposed to PIK debt. These investors are often required to value their assets regularly, but with PIK debt, the value is based on the assumption that the company will one day be able to pay off a much larger, compounded debt. If a macroeconomic shock or sector-wide downturn hits, that assumption will be shattered. The resulting wave of defaults on these ballooning debts could cause a liquidity crisis for the lenders themselves, forcing them to sell other assets at a loss and spreading the financial contagion. The next financial crisis may not be triggered by a housing bubble, but by a hidden mountain of corporate debt that was quietly growing in plain sight.
A Call to Action for Business Leaders: Don’t Be a Victim of Financial Deception
The ticking clock on PIK debt isn’t just a concern for Wall Street; it’s a direct threat to your business. As a leader, you must look beyond the glossy presentations and understand the underlying risks. This isn’t a time for complacency; it’s a time for strategic vigilance.
First, demand transparency. If your business operates in a leveraged environment, or if you’re considering a merger or acquisition, scrutinize the target’s debt structure. Ask tough questions about their ability to generate cash and whether they are making interest payments with cash or with more debt. Don’t be fooled by low default rates; the true health of a company lies in its cash flow, not in its ability to defer payments.
Second, fortify your own balance sheet. In an era of increasing interest rates and economic uncertainty, holding a strong cash position is a competitive advantage. Avoid the temptation to take on excessive debt, particularly if it comes with the “easy out” of a PIK clause. Focus on operational efficiency and building a business model that can withstand shocks, rather than one that relies on financial engineering to survive.
Finally, educate your team and your board. The danger of PIK debt is its subtlety. Many may not understand the long-term consequences of compounding debt. By raising awareness, you can ensure that your organisation makes prudent decisions that prioritise long-term sustainability over short-term financial gymnastics. The storm is coming, and only those who prepare will be able to weather it.
UK reverse marketplace for risk-managed B2B procurement
How to Post Secure RFPs in the UK and Attract Only Prequalified Suppliers
Powered by BusinessRiskTV Reverse Marketplace UK
In the age of rapid procurement and digital disruption, UK buyers face increasing risks when sourcing suppliers. Whether it’s supply chain instability, ESG non-compliance, or cyber vulnerabilities, making the wrong procurement decision can cost your business dearly. That’s why a new model of buying is emerging — one that puts risk criteria first and filters out unqualified suppliers.
Welcome to BusinessRiskTV’s Reverse Marketplace UK, the smartest way to post secure Requests for Proposals (RFPs) and connect only with prequalified sellers who meet your exacting risk standards.
What Is a Secure RFP – and Why Does It Matter?
A secure RFP isn’t just about keeping your data safe — it’s about making sure the entire supplier engagement process is protected against reputational, financial, regulatory, and operational risk.
When you post a traditional RFP, you often get:
Dozens of irrelevant proposals
Vendors who can’t meet your compliance needs
Wasted time vetting unreliable suppliers
Exposure to poor performance or even fraud
With secure RFPs, you flip the power back into the hands of the buyer — by making risk reduction the foundation of supplier selection.
How BusinessRiskTV Makes RFPs Secure
At BusinessRiskTV Reverse Marketplace UK, we offer a unique, risk-led approach to procurement. Here’s how we ensure your RFP is secure:
1. Buyer Risk Criteria Are Front and Centre
You tell us what you need — and what risks you need to avoid. We help you define these upfront in your RFP.
Examples of buyer-defined risk criteria:
✅ £10M minimum public liability insurance
✅ ISO 27001 certification
✅ Cyber Essentials Plus compliance
✅ 2+ years of industry experience
✅ ESG and modern slavery policy statements
✅ GDPR compliance for data processors
2. Only Prequalified Sellers Can Respond
Once your RFP goes live, only sellers who meet our strict prequalification standards can see and respond to it. That includes passing checks for:
Financial stability
Legal and regulatory compliance
Risk profile assessment
Reputation and track record
No cold callers. No dodgy dealers. No time-wasters.
3. Your RFP Is Professionally Structured by Our Experts
We don’t leave you to write your RFP alone. You pay us a small fee to:
Draft your RFP in a format that gets responses
Embed risk filters into the requirements
Showcase it to our vetted marketplace
Manage seller queries
Shortlist the best, most compliant proposals
Why Risk Matters More Than Price
Traditional procurement systems tend to reward low bids rather than low-risk suppliers. The cheapest offer isn’t always the best — especially when that vendor folds mid-project or lands you in court for non-compliance.
By contrast, BusinessRiskTV helps you choose vendors based on fitness for purpose AND risk profile.
🔍 “We’re not just helping you spend money. We’re helping you spend it wisely — without exposing your business to unacceptable risk.”
🧩 Example RFP Use Case
BUYER: A UK-based financial consultancy is looking for a data analytics firm to process client transaction data. Their risk criteria include:
GDPR and data security compliance
ISO 27001 and ISO 9001 certifications
Evidence of working with at least one FCA-regulated firm
PI insurance of £5M minimum
SELLERS: Only analytics firms on the BusinessRiskTV marketplace that have passed prequalification and match the above criteria are invited to bid.
RESULT:
The buyer receives four strong, compliant proposals. No irrelevant pitches. No post-contract compliance issues.
Why Buyers Pay To Post RFPs on BusinessRiskTV
You might wonder — why should buyers pay to post an RFP?
Because it eliminates the flood of garbage proposals, time-wasting pitches, and risky vendors. Our paid RFP showcase model ensures:
You’re treated as a serious buyer by serious sellers
Your RFP is crafted and positioned to attract high-quality responses
You get expert support to embed risk requirements
You save days or even weeks of screening unfit vendors
Think of it as an investment in procurement peace of mind.
Why Sellers Love This Model Too
You might think prequalifying sellers and blocking unfit bidders would scare off vendors. It doesn’t — it attracts the right ones.
Sellers love the BusinessRiskTV Reverse Marketplace because:
They only pitch when they’re a good match
They waste less time on dead-end RFPs
They compete with fewer, better-qualified peers
They build trust from the very first interaction
What’s Included in Your Secure RFP Posting Package?
Here’s what you get when you post an RFP on BusinessRiskTV Reverse Marketplace UK:
How does China’s near-monopoly on rare earth processing threaten your business and wallet? Discover the hidden costs for Western manufacturing, from EVs to smartphones, and learn urgent risk management strategies for industry leaders and consumers alike.
The Raw Nerve: Why China’s Grip on Rare Earths Threatens Western Prosperity
Western industry’s 90% reliance on China for rare earth processing is a catastrophic vulnerability. This article unmasks the threat to car manufacturing, consumer goods, and our very future, offering actionable strategies for business leaders to reclaim control and protect profitability.
“If China ever decided to turn off the tap, the lights would go out in boardrooms across the West. We’re not just talking about iPhones and Tesla, we’re talking about the very bedrock of our industrial future. This isn’t a theoretical exercise; it’s a present and growing danger. And frankly, we’ve been utterly complacent.” That’s the stark reality, isn’t it? For too long, Western business leaders have operated under the illusion of an open global market, blissful in their pursuit of short-term cost efficiencies. But what if that efficiency comes at the price of existential vulnerability? The sheer scale of China’s dominance in rare earth mineral processing isn’t just a challenge; it’s an economic weapon poised at our collective throat. This isn’t some abstract geopolitical squabble. This directly impacts your company’s bottom line, your nation’s security, and every consumer’s daily life. It’s time we faced the uncomfortable truth: our industrial future, indeed our very technological sovereignty, is hanging by a thread, and that thread leads directly to Beijing. This isn’t about protectionism; it’s about survival.
The Uncomfortable Truth: China’s Rare Earth Monopoly and Its Perilous Implications
Let’s not mince words. China doesn’t just have a significant share of rare earth mineral processing; it holds a near-monopoly, a stranglehold that few outside the industry truly comprehend. Reports indicate that China controls approximately 90% of the world’s rare earth processing capacity. Let that sink in. Ninety percent. While China may account for around 69% of global rare earth production from its mines, the critical bottleneck, the true leverage point, lies in its unparalleled ability to process these raw materials into usable forms.This isn’t just about digging rocks out of the ground; it’s about the complex, environmentally intensive, and technically demanding process of separation, refining, and alloy production. For decades, Western nations, driven by lower labour costs and less stringent environmental regulations in China, offshored these vital but dirty processes. We outsourced our dirty laundry, and in doing so, we handed over the keys to our industrial kingdom.
This overwhelming dependency on China for rare earth processing presents a colossal problem for Western manufacturing, particularly for high-tech sectors and, critically, the automotive industry.Rare earth elements (REEs) are not, despite their name, inherently rare in the Earth’s crust.However, they are rarely found in concentrated, easily extractable deposits, and their extraction and processing are notoriously complex and environmentally damaging. But their unique magnetic, luminescent, and electrical properties make them indispensable.
Consider the automotive sector. The transition to electric vehicles (EVs) is predicated on the availability of powerful, efficient electric motors. Guess what powers those motors? Neodymium-iron-boron (NdFeB) permanent magnets, which contain critical rare earth elements like neodymium and praseodymium, often enhanced with dysprosium and terbium for high-temperature performance. Without these magnets, EVs become less efficient, heavier, and significantly more expensive. China produces nearly 90% of the world’s rare earth magnets. A sudden restriction or even a significant delay in the supply of processed rare earths from China could, quite literally, grind Western EV production to a halt. We’ve seen this play out in recent months: when China introduced new export restrictions in 2025, Western auto plants faced immediate bottlenecks, even production halts.The ripple effect isn’t confined to EVs; conventional vehicles still use rare earths in catalytic converters, alternators, and various sensors. Imagine the disruption: assembly lines idled, product launches delayed, and billions in revenue evaporated, all because of a single point of failure in our supply chain.
Beyond the automotive industry, the implications cascade across virtually every advanced manufacturing sector. Wind turbines, central to our renewable energy ambitions, rely heavily on rare earth magnets for their generators.Modern defense systems – from precision-guided missiles and fighter jets to radar systems and advanced sensors – are critically dependent on these materials.Consumer electronics like smartphones, laptops, and flat-screen displays incorporate multiple rare earth elements. Medical devices, industrial robotics, and even the catalysts used in petroleum refining all demand a steady, reliable supply of processed rare earths. If China decides to weaponise this dominance – as it has demonstrated a willingness to do in past trade disputes – Western industries will face unprecedented supply shocks, escalating costs, and a debilitating loss of competitive edge. This isn’t merely about higher prices; it’s about the fundamental ability to produce cutting-edge technology and maintain a viable industrial base.
The Consumer Conundrum: The Hidden Cost of Our Dependency
For Western consumers, the problem of rare earth processing dependency on China manifests in several tangible and uncomfortable ways. Firstly, and most immediately, expect higher prices.When the supply of critical components becomes constrained, manufacturers face increased costs for raw materials and processing. These costs, inevitably, are passed on to the consumer. That new electric vehicle you’ve been eyeing? Its price tag will likely climb. The latest smartphone? Expect it to be more expensive. This isn’t just a minor fluctuation; it’s a structural increase driven by geopolitical risk.
Secondly, prepare for reduced availability and choice. If manufacturing lines in the West cannot secure the necessary rare earth elements, product shortages will become commonplace. Waiting lists for popular EV models could stretch indefinitely. The newest, most innovative electronic gadgets might simply not reach store shelves in sufficient quantities. This translates into a frustrating consumer experience, where demand outstrips supply, and innovation is stifled not by a lack of ideas, but by a lack of fundamental materials.
Thirdly, and perhaps most insidiously, this dependency impacts the very pace of technological advancement and the green transition. Our ambitious climate goals, heavily reliant on renewable energy technologies like wind turbines and EVs, are vulnerable. If the materials needed to build these technologies are controlled by a single, potentially adversarial power, the transition to a sustainable future could be significantly delayed or derailed entirely. Consumers might find that access to cleaner energy and transport options is curtailed, not by a lack of desire or investment, but by a strategic bottleneck. We talk about energy independence, but what about mineral independence? Without it, our energy transition dreams remain just that: dreams.
Finally, there’s the less tangible but equally important aspect of national security and economic stability. When a nation’s core industries and defence capabilities are reliant on a foreign power for critical components, it introduces an inherent vulnerability. This can lead to compromises in design, limitations in military readiness, and a chilling effect on innovation as companies become wary of investing in products that could be suddenly cut off from their vital inputs. Consumers ultimately pay the price for this instability through higher taxes to fund strategic stockpiles, increased national debt, and a general erosion of economic resilience.
A Call to Action: Managing the Risk and Reclaiming Our Future
So, what should Western countries and their industries be doing about this precarious situation? Passivity is no longer an option; it is an act of economic self-sabotage. We need a multi-pronged, aggressive strategy that acknowledges the severity of the threat and prioritises long-term resilience over short-term cost savings. This is an enterprise risk management challenge of the highest order, and it demands decisive action from business leaders.
For Western Industries: A Blueprint for Resilience
Diversify Sourcing – Immediately and Aggressively: This is non-negotiable. Companies must move beyond a “China-first” mentality. Identify and develop relationships with new mining and processing facilities in allied nations. Countries like Australia, Canada, the United States, and even parts of Africa and South America hold significant rare earth reserves. Invest in these operations! Don’t just wait for the market to deliver; actively participate in building these alternative supply chains. This means long-term purchase agreements, direct investments in promising ventures, and forming strategic alliances that span the entire value chain, from mine to magnet. Yes, it will be more expensive in the short term. But the cost of disruption, of industrial paralysis, far outweighs any perceived savings from relying solely on China. Business leaders must educate their boards and shareholders: security of supply is a competitive advantage, not an optional expense.
Invest in Domestic Processing Capabilities: This is the elephant in the room. We extracted ourselves from the dirty work, and now we must embrace it again, but this time with a commitment to sustainable practices. Governments must provide incentives, certainly, but private industry cannot wait. Forge public-private partnerships. Build the refineries, the separation plants, the alloy production facilities on Western soil. Develop clean processing technologies that minimise environmental impact – this can be a new source of competitive advantage, a way to differentiate our supply chains. This won’t happen overnight; it requires significant capital expenditure and a long-term vision, but it is absolutely essential. We cannot be reliant on any single nation for the critical processing step.
Drive Innovation in Substitution and Recycling: This is where engineering brilliance meets strategic imperative.
Substitution: Can we develop alternative materials or designs that reduce or eliminate the need for specific rare earth elements? BMW, for instance, has explored EV motor designs that use fewer or no rare earth magnets, albeit with some trade-offs in efficiency.Toyota has developed heat-resistant magnets with less neodymium and no terbium or dysprosium. This needs to become a widespread R&D priority. Fund your R&D teams to aggressively pursue rare-earth-free alternatives. Challenge them, empower them, and reward them for breakthroughs.
Recycling (“Urban Mining”): The vast quantities of rare earths already embedded in discarded electronics, EVs, and wind turbines represent a valuable, untapped resource. Invest in advanced recycling technologies that can efficiently and economically recover these elements from end-of-life products. Develop closed-loop systems within your manufacturing processes. This not only reduces reliance on virgin materials but also aligns with broader sustainability goals. Governments should incentivise collection and recycling infrastructure, but industries must lead the charge in developing the technical solutions.
Strategic Stockpiling: While not a long-term solution, maintaining strategic reserves of critical rare earth elements and even finished magnets can provide a vital buffer against short-term supply disruptions. This is an insurance policy. It buys time for alternative supply chains to mature or for new technologies to come online. It’s a pragmatic recognition of current vulnerabilities. Work with national governments to ensure these stockpiles are sufficient and regularly rotated.
Supply Chain Transparency and Visibility: You can’t manage what you can’t see. Companies must implement robust supply chain tracking systems that provide granular visibility into the origin and processing of rare earth components. Understand your exposure at every tier. Demand this information from your suppliers, and if they cannot provide it, find suppliers who can. This isn’t just about compliance; it’s about existential risk management.
For Western Consumers: Empowering Your Choices
Consumers might feel powerless in the face of such a colossal geopolitical challenge, but that’s simply not true. Your purchasing decisions and your voice carry significant weight.
Demand Supply Chain Transparency: Ask brands where their materials come from. As a consumer, you have the right to know if your new EV, your smartphone, or even your home appliances are built with materials sourced from resilient, ethical, and diversified supply chains. Vote with your wallet. Support companies that are actively demonstrating a commitment to responsible sourcing and reducing their reliance on single-point-of-failure suppliers. Make it clear that you are willing to pay a fair price for products that contribute to a secure and sustainable future, not just a cheap one.
Embrace Longevity and Repairability: The faster we consume and discard electronic devices, the greater the demand for new rare earth materials. Choose products designed for durability and repairability. Support the “right to repair” movement. By extending the lifespan of your devices, you are directly reducing the pressure on new rare earth mining and processing. This is a direct, actionable step you can take.
Support Recycling Initiatives: Participate actively in electronic waste recycling programs. While the recycling infrastructure for rare earths is still developing, your participation helps build the critical mass needed for these systems to scale. Don’t let your old phone sit in a drawer; ensure it enters the recycling stream. Advocate for better recycling facilities in your local community.
Educate Yourself and Others: Understand the issue. Talk about it. The more public awareness there is, the greater the pressure on businesses and governments to act decisively. This isn’t just an obscure industrial issue; it’s fundamental to our technological future and national security.
The era of cheap, easy access to critical materials, particularly rare earths, from a single dominant source is over. Western industries and consumers alike face a reckoning. We have outsourced our vulnerabilities, and now we must pay the price – either through proactive, strategic investment and difficult choices, or through economic stagnation and a chilling surrender of our technological future. The choice, for once, is clear. It’s time to act. It’s time to build a future where our prosperity is not dictated by the whims of a single foreign power, but by our own ingenuity, resilience, and strategic foresight.
Get help to protect and grow your business faster with BusinessRiskTV
Read more business risk management articles and view videos for free
Protect your company’s future: China’s rare earth processing dominance poses an unprecedented risk to Western manufacturing. This deep dive provides business leaders with vital insights and a roadmap for diversifying supply chains, investing in domestic capabilities, and securing profitability.
The West’s dangerous rare earth dependency on China is a ticking time bomb for industry and consumers. This article offers blunt truths and essential strategies for business leaders to navigate this critical supply chain risk.
Introduction: Why Understanding Real Risks is the Key to Business Success
The Problem: Why UK Business Leaders Struggle with Risk Management
The Consequences of Ignoring Real Business Risks
Internal vs. External Risks: What’s Really Threatening Your Business?
Overcoming Fear of Failure — and Success
Why Settling for the Status Quo is the Biggest Risk of All
How to Identify the Real Risks to Your Business Survival and Growth
Assessing Risks: Tools and Strategies for Better Decision-Making
Controlling Risks: Turning Threats into Opportunities
The Role of Innovation in Reducing Risk and Accelerating Growth
Expanding Sales More Profitably in the UK Market
The Power of Networking: Leveraging BusinessRiskTV.com’s Business Experts Hub
Connecting Buyers and Sellers More Effectively Online
Case Studies: Businesses That Mastered Risk and Dominated Their Markets
Action Plan: Stop Waiting, Start Executing
Conclusion: Elevate Your Business Above Uncertainty
—
Introduction: Why Understanding Real Risks is the Key to Business Success
In today’s volatile business environment, only those who truly understand the real risks will manage them better. Many business leaders in the UK are operating with blind spots—unaware of the threats that could derail their growth or the opportunities they’re missing.
This book is not just about risk avoidance; it’s about risk mastery. It’s about preparing for the most valuable opportunities and dominating your marketplace. You already have what it takes to be greater than you’ve been so far — but you must overcome fear, stop waiting, and act now.
Whether you’re afraid of failure — or even success — this guide will help you break through barriers, identify the real risks, and turn them into advantages.
—
The Problem: Why UK Business Leaders Struggle with Risk Management
Many UK business leaders:
Lack deep knowledge of the risks affecting their industry.
Don’t know which risks to take to grow faster.
Don’t have the right experts to help them assess and control risks.
Underestimate internal risks (like leadership gaps or cash flow issues).
Overestimate external risks (like economic downturns or competition).
This knowledge gap leads to missed opportunities, slower growth, and unnecessary vulnerabilities.
—
Expanding the Problem: The Need for Innovation and Profitable Growth
Why should UK business leaders innovate? Because standing still is riskier than evolving. Companies that fail to adapt:
Lose market share to competitors.
Become irrelevant in changing industries.
Miss profitable expansion opportunities.
The solution? Strategic risk-taking. This book will show you how to expand sales more profitably by focusing on high-reward, low-risk strategies.
—
The Risk Management Solutions with BusinessRiskTV.com
You don’t have to navigate risks alone. BusinessRiskTV.com offers:
✅ Business Experts Hub – Network with risk management professionals.
✅ Risk Assessment Tools – Make smarter decisions.
✅ Online Marketplace – Connect buyers and sellers more cost-effectively.
By leveraging these resources, you can gain clarity, reduce uncertainty, and seize opportunities faster.
Targets decision-makers searching for the financial impact of weak risk practices
THE HIDDEN TAX OF POOR RISK MANAGEMENT
Your business is leaking money. Not in the obvious ways — like overspending or inefficiency — but in silent, insidious drains you might not even see. Poor risk management isn’t just about avoiding disasters; it’s a profit killer, a growth stifler, and, in the worst cases, an executioner of businesses that could have thrived.
Consider this: 30% of bankruptcies are due to operational failures that could have been mitigated with better risk practices (OECD). That’s not bad luck—it’s self-inflicted. And if you think your company is immune, think again.
This isn’t theoretical. Every day, businesses hemorrhage cash through:
Employee disengagement —teams that don’t see risk as their problem, costing you in errors, delays, and lost innovation.
The result? Lower profitability. Stunted growth. And, in extreme cases, extinction.
But here’s the good news: this is entirely optional and fixable.
In this e-book, we’ll expose the 12 most damaging costs of poor risk management —many of which you’re likely paying right now — and deliver 12 actionable solutions to turn risk from a liability into a competitive advantage. You’ll learn how to:
Engage every employee in risk ownership (not just compliance, but profit protection).
Stop financial bleed from preventable failures.
Turn risk-aware decision-making into a growth engine.
This isn’t another dry risk management manual. This is a survival guide for profitable, resilient business leadership.
Ready to plug the leaks? Let’s begin.
🚨 YOUR BUSINESS IS LEAKING £££ – FIND THE HOLES! 🚨
83% of UK SMEs lose £50k+ yearly from hidden risks they don’t even measure:
❌ Operational failures burning cash ❌Supply chain disasters killing margins
❌ Cyberattacks costing millions
BusinessRiskTV’s NEW eBook reveals:
✅ 12 PROVEN FIXES to stop profit leaks
✅ Real case studies from UK businesses
✅ Simple checklists to act TODAY
Chapter 1: The Hidden Costs of Poor Risk Management – How Ignoring Risk Erodes Your Profits and Threatens Survival
Introduction: The Silent Profit Killer
Every business faces risks—some obvious, others invisible. But when risk management is an afterthought, those risks don’t just linger; they multiply costs, shrink margins, and sabotage growth. This chapter exposes the real financial and operational toll of poor risk management—and why most businesses underestimate it.
—
1. The Direct Financial Costs: Where the Money Leaks
A. Unexpected Losses from Operational Failures
Example: A manufacturing firm ignores equipment maintenance, leading to a breakdown that halts production for 48 hours. The result? £250,000 in lost revenue + £50,000 in emergency repairs.
Stat: Companies with weak operational risk management see 30% higher unexpected costs (Deloitte).
B. Regulatory Fines & Legal Penalties
Case Study: A UK SME in financial services fails to comply with GDPR, resulting in a £180,000 fine —plus reputational damage.
Stat: 60% of small UK businesses aren’t fully compliant with key regulations (FSB).
Key Takeaway: Poor risk management isn’t just about avoiding disasters — it’s a tax on profitability, growth, and survival.
—
Actionable Insight: Audit one high-cost risk in your business this week (e.g., late payments, compliance gaps). What’s it really costing you?*
—
Chapter 2: The True Cost of Operational Failures – How Inefficient Risk Management Cripples Your Business
Introduction: The Domino Effect of Poor Operational Risk Controls
Operational risks don’t just cause one-off incidents—they trigger chain reactions that drain cash, demoralise teams, and erode customer trust. This chapter exposes the hidden, cascading costs of mismanaged operational risks and why most businesses only see the tip of the iceberg.
—
1. The Obvious Costs: What You Can’t Ignore
A. Downtime & Lost Production
Manufacturing Example: A single machine failure halts a production line for 8 hours → £25,000 in lost output + overtime costs to catch up.
Hospitality Example: A restaurant’s refrigeration breakdown spoils £3,000 of stock overnight — plus angry customers.
Stat: UK manufacturers lose £180 billion/year to unplanned downtime (EEF).
B. Emergency Repairs & Rush Orders
Reactive spending costs 3–5X more than planned maintenance.
Case Study: A logistics firm ignores fleet maintenance → two vans fail MOTs simultaneously → £8k in last-minute rentals + delayed deliveries.
C. Waste & Rework
Construction Example: Poor quality control leads to £50,000 of defective materials — then doubles labour costs to fix errors.
Stat: 20–30% of project budgets are wasted on rework (KPMG).
—
2. The Hidden Costs: What You’re Not Tracking (But Should Be)
A. Employee Productivity Drain
Scenario: A retail store’s outdated inventory system causes daily stock discrepancies. Staff waste 4 hours/day manually reconciling data instead of selling.
Stat: UK workers spend 15% of their time fixing preventable issues (PwC).
B. Management Distraction & Burnout
Small Business Reality: The owner spends 60% of their week putting out fires (supplier delays, IT crashes) instead of growing the business.
Psychological Cost: Chronic stress → poor decisions → more risks.
C. Customer Churn & Reputation Erosion
E-commerce Example: A fulfilment centre’s picking errors lead to 10% of orders arriving wrong → 15% of customers never return.
Stat: 70% of customers switch brands after just 2–3 bad experiences (Salesforce).
—
3. The Strategic Costs: How Operational Risks Stunt Growth
A. Lost Competitive Advantage
Case Study: A UK bakery’s unreliable oven delays a product launch by 3 months —competitors dominate supermarket shelves first.
B. Innovation Paralysis
Teams stuck in “firefighting mode” never test new ideas.
Example: A tech firm’s IT team spends 80% of time fixing outages → zero R&D progress.
C. Investor & Partner Distrust
Supply Chain Example: A fashion brand’s repeated delivery failures lead to two major retailers dropping them —£500k annual revenue gone.
—
4. The Survival Threat: When Operational Risks Become Fatal
A. Cash Flow Death Spiral
Construction Firm Case Study:
1. Poor contract risk assessment → unpaid invoices pile up
2. Equipment breakdown → project delays
3. Penalties for late delivery → bank calls in loan Result: Administration within 6 months.
B. The Carillion Effect
How ignoring operational risks (contract mismanagement, cash flow gaps) led to the UK’s biggest corporate collapse.
—
5. The Bottom Line: Quantifying Operational Risk Costs
Key Insight: Operational risks don’t just cost money—they steal time, talent, and future opportunities.
—
More From BusinessRiskTV Business Experts Hub : How to Fix It
We explore how to turn operational risk management into a profit centre, including:
The 5-minute daily habit that prevents 80% of failures
How to engage frontline teams in risk reduction (with real-world examples)
Actionable Task: Map one critical operational process (e.g., order fulfilment). Where could a single failure cost you £10k+?
—
Chapter 3: Strategic Risks – How Blind Spots in Planning Can Bankrupt Even Profitable Businesses
Introduction: The Silent Assassin of Business Growth
Strategic risks don’t announce themselves with alarms — they creep in unnoticed while leadership is distracted by day-to-day operations. By the time the damage is visible, it’s often too late to pivot. This chapter exposes how poor strategic risk management destroys market position, erodes competitive edge, and turns industry leaders into cautionary tales.
—
1. What Are Strategic Risks? (And Why They’re Different)
Key Takeaway: Strategic risks don’t just hurt profits — they erase entire business models.
—
More from BusinessRiskTV Business Experts Hub : How to Anticipate & Outmanoeuvre Strategic Risks
We explore practical frameworks to:
Spot industry shifts early (using weak signals)
Stress-test your strategy against disruption
Turn risks into opportunities (like Amazon’s pivot from books to cloud)
Actionable Task: List one strategic assumption your business relies on (e.g., “Customers will always prefer X”). How would you survive if it’s wrong?
—
Chapter 4: Financial Risks – How Poor Cash Flow & Debt Management Can Sink Your Business Overnight
Introduction: The Silent Killer of Healthy Businesses
Profit doesn’t equal survival. Thousands of UK businesses post record revenues—right before going bust. Why? Because financial risk management isn’t about counting pennies — it’s about anticipating traps that strangle cash flow, trigger defaults, and collapse supply chains.
This chapter exposes the lethal financial risks hiding in plain sight — and why even profitable companies run out of money.
—
1. The Obvious (But Ignored) Financial Risks
A. Cash Flow Crises – The #1 Business Killer
Reality: 82% of UK business failures cite cash flow problems as the primary cause (UK Insolvency Service).
Example: A £5M-turnover construction firm collapses because:
– Client pays invoices 90 days late
– Supplier demands upfront payments due to past delays
– Bank rejects emergency loan Result: Liquidation despite £1.2M in “paper profits.”
B. Debt Avalanches – When Borrowing Backfires
Case Study: A fast-growing e-commerce firm takes on high-interest debt to fund inventory. Sales dip, interest compounds, and suddenly 60% of revenue services debt.
– Stat: 40% of UK SMEs struggle with unmanageable debt (Bank of England).
C. Currency & Commodity Swings
Example: A UK bakery’s flour costs jump 30% after a wheat shortage. Contracts lock in prices — margins vanish overnight.
—
2. The Hidden Financial Risks That Compound Quietly
A. Customer Concentration Risk
Scenario: A B2B software firm gets 70% of revenue from one client. When that client leaves, payroll can’t be met.
Rule of Thumb: No single client should exceed 15–20% of revenue.
B. Supplier Dependency & Price Shocks
Case Study: A car manufacturer relies on one battery supplier. When shortages hit, production stalls for 3 months → £9M loss.
C. Fraud & Financial Mismanagement
Stat: UK businesses lose £137B yearly to fraud, waste, and accounting errors (PwC).
Example: A finance director “cooks the books” — investors pull out when the truth surfaces.
—
3. The Strategic Fallout: When Financial Risks Spiral
A. Credit Downgrades & Banking Nightmares
Example: A once-stable firm misses a loan covenant — interest rates spike 5%, lines of credit freeze.
B. Investor Panic & Equity Crashes
Case Study: A tech startup’s burn rate exceeds projections — VCs demand emergency restructuring, slashing valuation by 50%.
C. Employee Exodus (When Paychecks Bounce)
Stat: 78% of employees leave within 6 months of payroll issues (CIPD).
—
4. The Ultimate Cost: Bankruptcy Dominoes
A. The “Profitable But Insolvent” Paradox
How It Happens:
1. Big contracts signed → revenue looks strong
2. Clients pay late → cash dries up
3. Suppliers demand payment → no money for salaries/tax
4. HMRC forces liquidation despite “growth.”
B. The Carillion Effect (Again)
£7B collapse triggered by:
– Aggressive accounting
– Reliance on unsustainable contracts
– No cash buffer for delays
Key Insight: Financial risks don’t just reduce profits — they erase businesses in weeks.
—
More from BusinessRiskTV Business Experts Hub : How to Fix It
We explore real-world financial risk strategies, including:
The 13-week cash flow rule (used by turnaround experts)
How to renegotiate debt before it’s too late
Building a “war chest” for crises
Actionable Task: Run a “stress test” on your cash flow: What if 2 clients pay 60 days late?
—
Chapter 5: Cyber Risks – The Invisible Threat That Could Bankrupt Your Business by Breakfast
Introduction: The Digital Time Bomb Ticking in Your Business
Imagine arriving at work to find:
Your customer database on the dark web
Fraudsters draining £250,000 from your account
Ransomware locking every file until you pay Bitcoin
This isn’t a movie plot — it’s Monday morning for thousands of UK businesses. Cyber risks don’t just steal data; they extort cash, destroy reputations, and trigger regulatory hell. And here’s the worst part: Most victims never see it coming until the damage is done.
—
1. The Direct Costs: What Happens When Cybercrime Hits
A. Ransomware: The Digital Kidnapping Epidemic
2023 Reality: A UK construction firm’s blueprints, invoices, and payroll systems encrypted. Hackers demand £120,000 to unlock files.
Stat: 73% of UK businesses hit by ransomware in 2023 (NCSC).
Brutal Truth: Paying doesn’t guarantee recovery — 32% never get full data back (Sophos).
B. Data Breaches: When Your Customers Become Victims
Case Study: A mid-sized retailer’s poorly secured e-commerce platform leaks 380,000 credit cards.
£500,000 GDPR fine
£1.2M in fraud reimbursements
22% customer churn
Stat: Average UK data breach cost: £3.4 million (IBM).
C. Business Email Compromise (BEC): The Silent Heist
How It Works: A hacker impersonates your CEO, emails finance: “Urgent: Transfer £80k to new supplier.”
UK Losses: £1.3 billion stolen via BEC in 2023 (UK Finance).
—
2. The Hidden Costs That Cripple You Later
A. Reputation Freefall & Customer Exodus
After a breach:
– 58% of customers avoid breached brands (Verizon)
– Recovery Cost: 3–5X more on marketing to rebuild trust
B. Operational Paralysis
Example: A law firm’s servers go down for 72 hours post-attack. £350k in billable hours lost + client lawsuits.
C. Insurance Nightmares
Post-Claim Realities:
– Premiums triple
– Mandatory audits drain management time
– Some policies simply won’t renew
—
3. The Strategic Fallout: Long-Term Business Damage
A. Lost Contracts & Blacklisting
Government/Corporate Tenders Now Demand:
– Cyber Essentials Certification (missing? Disqualified automatically)
– Proof of incident response plans
B. Investor Flight
Startup Killer: A fintech’s pre-IPO breach scares off VCs, slashing valuation by 60%.
C. Director Liability (Yes, You Can Go to Jail)
UK Law: Under GDPR & NIS Directive, negligent executives face fines up to £17.5M or 4% of global revenue — plus disqualification.
—
4. Why Cyber Risks Are Worse Than You Think
A. It’s Not Just “Big Targets”
61% of UK attacks hit SMEs (Verizon) — hackers bet they’re unprepared.
B. Remote Work = 300% More Attack Surfaces
Example: An employee’s compromised home laptop gives hackers access to your entire CRM.
C. AI-Powered Attacks Are Here
New Threat: Deepfake audio of your CFO “calling” finance to wire funds.
Key Insight: Cyber risks aren’t an “IT problem” — they’re an existential business threat.
—
More from BusinessRiskTV Business Experts Hub : How to Fight Back
We will explore real-world cyber defenses, including:
The 5-step SME ransomware shield (costs <£5k/year)
– How to trick hackers into avoiding you (attackers prefer easy targets)
– Turning employees into human firewalls
Actionable Task: Run this free test now: [Have I Been Pwned](https://haveibeenpwned.com/) to check if your work emails are already in hacker databases.
—
Chapter 6: Human Risks – When Your Greatest Asset Becomes Your Biggest Liability
Introduction: The Enemy Inside Your Walls
Your employees can either be your strongest defence — or your weakest link. Negligence, disengagement, and malicious actions cost UK businesses £30 billion annually (ACAS). This chapter exposes how poor people risk management leads to:
– Catastrophic errors
– Culture collapse
– Regulatory disasters
– Fraud epidemics
And why traditional HR policies fail to prevent 89% of these risks (PwC).
—
1. The Obvious (But Ignored) Human Risks
A. The High Cost of Disengagement
Example: A retail chain’s apathetic staff miss 40% of shoplifting incidents —costing £220,000/year in stolen stock.
Stat: Disengaged employees are 450% more likely to cause operational errors (Gallup).
B. Turnover Tsunamis
Case Study: A tech firm’s toxic culture drives out 7 senior engineers in 6 months — delaying a £2M product launch by 11 months.
Replacement Cost: Up to 2X annual salary per lost employee (Oxford Economics).
C. Training Gaps That Become Legal Nightmares
Reality Check: A warehouse worker badly operates a forklift, causing £80k in damages + HSE fines—because “training was just a 10-minute video.”
—
2. The Hidden (But More Dangerous) Human Risks
A. Insider Threats: When Employees Attack
Shocking Stat: 58% of data breaches involve insiders (Verizon).
Methods:
– The Malicious: IT admin sells customer data (£50k on dark web)
– The Careless: Accountant emails payroll files to personal Gmail
B. Culture Risks: How Toxicity Spreads
Example: A sales team’s “win at all costs” mentality leads to fraudulent client promises — £600k in lawsuits + FCA investigation.
C. Leadership Blind Spots
CEO Overconfidence: Ignoring team warnings about a flawed expansion → £3M write-off.
Stat: 82% of business failures trace back to poor leadership decisions (KPMG).
—
3. The Strategic Fallout: When People Risks Sink Companies
A. The Volkswagen Emissions Scandal
Root Cause: A culture where “nobody dared question” fraudulent engineering.
– Cost: €32 billion in fines/losses + permanent brand damage.
B. The Barclays CEO Scandal
How It Happened: Leadership’s obsession with “star hires” led to unchecked bullying — triggering £1M fines + investor revolt.
C. The Everyday SME Killer
Scenario: Your “trusted” bookkeeper embezzles £150k over 3 years — exposed only during a tax audit.
—
4. Why Traditional Approaches Fail
Annual compliance training?86% of employees forget it within 30 days (MIT).
“Hotline whistleblowing”?62% of staff fear retaliation (EY).
Top-down policies? Frontline teams see them as “head office nonsense.”
Key Insight: Your employees create or destroy value daily — often without realising it.
—
More from BusinessRiskTV Business Experts Hub : How to Transform Human Risk into Advantage
We explore battle-tested solutions, including:
The “Psychological Safety” hack
How to spot insider threats before they strike
Turning compliance into competitive edge
Actionable Task: Run a 5-minute “risk culture pulse check” with your team this week: “What’s one process you think could fail catastrophically?”
—
Chapter 7: Supply Chain Risks – The Fragile Web That Could Strangle Your Business Overnight
Introduction: Your Business Is Only as Strong as Its Weakest Supplier
A single delayed shipment. One insolvent vendor. A geopolitical shockwave. Suddenly, your production line stops, customers revolt, and cash flow evaporates.
Key Insight: Supply chains have become the ultimate leverage point — for your competitors or your downfall.
—
More from BusinessRiskTV Business Experts Hub : How to Build an Unbreakable Supply Chain
We explore wartime-tested strategies, including:
The “3D Supplier Mapping” trick (used by Special Forces logisticians)
How to turn suppliers into partners (not adversaries)
When to nearshore/onshore without bankrupting yourself
Actionable Task: Identify one “critical” supplier you couldn’t operate without. How would you survive if they vanished tomorrow?
—
Chapter 8: Reputational Risks – When Trust Collapses Faster Than Your Share Price
Introduction: The 24-Hour Business Execution
A single tweet. One viral video. A disgruntled employee’s LinkedIn post. In today’s digital wildfire, your hard-earned reputation can evaporate before your crisis team finishes their first coffee.
The brutal reality:
87% of consumers will abandon a brand after a reputation crisis (YouGov)
It takes 4-7 years to build trust but just 4 bad days to destroy it (Edelman Trust Barometer)
65% of a company’s market value is tied to intangible assets like reputation (Ocean Tomo)
This isn’t about PR spin – it’s about preventing the preventable and surviving the unpredictable.
—
1. The Obvious Reputation Killers
A. Social Media Firestorms
Case Study: A restaurant manager’s racist comment caught on video → 300,000 angry tweets in 48 hours → permanent 40% revenue drop
Stat: Viral crises spread 20x faster than management can respond (MIT Sloan)
B. Executive Scandals
The P&G CEO Effect: A $375 billion company lost $40B in market cap in days after CEO’s inappropriate relationship surfaced
“No comment” = “We’re guilty” in public perception
Corporate-speak increases distrust by 41% (Edelman)
Legal-first responses often worsen the crisis
—
5. The Survival Playbook (Preview)
More from BusinessRiskTV Business Experts Hub we will explore modern reputation armour, including:
The “Dark Web Early Warning” system (catch crises before they explode)
Turning employees into reputation ambassadors
When to apologise vs. when to fight back
Actionable Task: Google “[Your Brand] + scandal” right now. What autocomplete suggestions appear?
—
Chapter 9: Climate Risks – The Existential Threat That’s Already Costing Your Business
Introduction: Your Business Is on the Frontlines of the Climate Crisis
Climate change isn’t a distant threat — it’s eroding profits, disrupting supply chains, and rewriting industry rules rightnow. In 2024 alone, climate disasters caused $2 trillion in global losses, with businesses absorbing the brunt through:
Operational shutdowns (e.g., factories flooded, data centres overheated
Soaring insurance premiums (up 300% in high-risk zones)
Regulatory penalties (e.g., non-compliance with carbon disclosure rules)
This chapter exposes the hidden costs of climate risks — and why most companies are dangerously unprepared.
—
1. The Two Faces of Climate Risk
A. Physical Risks: When Nature Attacks
1. Acute Disasters:
– Example: Hurricane Helene (2024) caused $225B in damages, disrupting microchip supplies by destroying a key quartz supplier .
– Stat: Severe weather events now cost businesses $560–610B yearly in asset losses .
2. Chronic Pressures:
– Heatwaves reduce worker productivity by 15–20% in sectors like construction and agriculture .
– Droughts forced a UK beverage company to halt production for 6 weeks due to water shortages .
B. Transition Risks: The Legal and Market Backlash
1. Policy Shocks:
– Carbon taxes could erase 20% of profits for high-emission firms by 2030 .
– Example: EU’s Carbon Border Tax added 10–20% costs for non-compliant imports .
2. Reputation Fallout:
– 75% of consumers boycott brands with poor sustainability records .
– Investor Flight: ESG-backlash aside, 90% of Fortune 500 firms now face shareholder climate lawsuits .
—
2. The Hidden Costs You’re Not Tracking
A. Supply Chain Domino Effects
Case Study: Floods in Thailand (2023) disrupted 40% of global hard drive production → tech firms lost $20B+
Stat: 73% of companies admit their supply chains are “highly vulnerable” to climate shocks .
B. Workforce Crises
Heat Stress: UK warehouses saw 30% more sick days during 2024’s record summer .
Talent Drain: 67% of Gen Z employees reject jobs at firms with weak climate policies .
C. Stranded Assets
Example: Oil companies wrote off $300B in reserves as “unburnable” due to net-zero policies.
Projection: 20% of commercial real estate will be uninsurable by 2030 .
Key Insight: Climate risks are profit killers — not just “ESG checkboxes.”
—
More from BusinessRiskTV Business Experts Hub : How to Fight Back
We will explore actionable climate resilience strategies, including:
The “3D Supply Chain Mapping” tactic (used by Special Forces logisticians)
How to turn carbon cuts into tax savings
AI-powered climate forecasting tools
Actionable Task: Run a 5-minute vulnerability scan: Which single climate threat (e.g., flood, heatwave) couldshut down your operations for 48 hours?
—
*Sources: World Economic Forum , Allianz , Beazley , Optera , EPA *
Chapter 10: 12 Actionable Solutions to Transform Risk into Competitive Advantage
Introduction: Risk Management Isn’t About Survival—It’s About Dominance
The most profitable companies don’t just avoid risks — they weaponise them. Toyota’s supply chain resilience made it the #1 automaker during the chip shortage. Amazon turned cybersecurity into a $35B AWS profit centre.
This chapter delivers 12 battle-tested solutions to stop losing money and start outpacing competitors.
—
Solution 1: The “Risk Ownership” Culture Hack
Problem: Employees see risk as “management’s problem.”
Fix:
– Tie 10-15% of bonuses to risk KPIs (e.g., near-miss reports, compliance audits)
– Example: A logistics firm reduced warehouse injuries by 62% after adding safety metrics to performance reviews
Action Step: This week, have each department identify one preventable risk they’ll now “own.”
—
Solution 2: The 5-Minute Daily Risk Radar
Problem: Monthly reports miss emerging threats.
Fix:
– Daily 5-minute standups on:
Top 3 operational vulnerabilities (e.g., server capacity, inventory levels)
Weak signals (e.g., supplier payment delays, social media complaints)
Case Study: A manufacturer caught a critical component shortage 3 weeks early by tracking supplier lead times daily
**Template:**
“`
[ ] Key risk #1 status
[ ] New threat detected
[ ] Mitigation action
“`
—
Solution 3: Cyber “Human Firewall” Training That Works
Problem: Boring compliance training fails.
Fix:
Monthly simulated phishing with “hacked” employees retaking interactive VR training
Result: One law firm reduced click-through rates from 28% to 3% in 6 months
Free Tool: Use CanIPhish for automated simulations
—
Solution 4: The 13-Week Cash Flow War Chest
Problem: Companies die from cash flow gaps, not lack of profit.
Fix:
1. Map all cash inflows/outflows week-by-week
2. Identify 3 survival levers (e.g., delayed payables, early collections)
3. Stress test with:
– 30% sales drop
– 60-day client payment delays
Example: A restaurant chain survived COVID by pre-negotiating 90-day rent deferrals before lockdowns
—
Solution 5: Supplier “X-Ray” Audits
Problem: 4th-tier suppliers can bankrupt you.
Fix:
– Demand blockchain-tracked materials for critical inputs
– Red Team Test: Randomly delay payments to check supplier liquidity
– Stat: Firms with mapped supply chains recover 9x faster from disruptions
—
Solution 6: AI-Powered Risk Forecasting
Toolkit:
Climate: Cervest (predict asset flooding)
Cyber: Darktrace (autonomous threat detection)
Financial: Simudyne (stress test scenarios)
ROI Example: A insurer cut claims by 22% using flood prediction AI
—
Solution 7: The “Pre-Mortem” Strategy Session
Problem: Executives ignore failure scenarios.
Fix: Before decisions:
1. Imagine the project has failed catastrophically
2. Brainstorm exactly why
3. Build safeguards
Case Study: Boeing’s 737 Max crashes could’ve been prevented by this method
—
Solution 8: Embedded Risk Officers
Innovation: Place risk champions in:
– R&D teams (kill flawed prototypes early)
– Sales (flag unrealistic client promises)
– Result: A pharma firm avoided $200M in FDA fines by catching compliance gaps during drug development
—
Solution 9: Dynamic Risk Scoring
Tool: Custom risk dashboards weighting:
– Probability (1–10)
– Impact (£)
– Velocity (how fast threat is growing)
– Example: A bank auto-prioritises risks scoring >£500k impact
—
Solution 10: The “Unthinkable” Drill
Annual Exercise: Simulate:
– CEO arrested
– HQ destroyed
– Key Result: BrewDog survived a ransomware attack because they’d practiced IT failovers quarterly
—
Solution 11: Turn Risk Into Revenue
Examples:
– Tesla sells carbon credits ($1.8B in 2023)
– Maersk’s green shipping premiums command 20% price hikes
Dubai Freelancer Visa for the purpose of operating an online business
Escape the Ordinary, Embrace Dubai: Your Blueprint for UK Residents to Launch an Online Empire and Secure Residency Through the Freelancer Visa!
Feeling the squeeze of the UK economy? Tired of the same old routine? What if I told you there’s a vibrant, opportunity-rich landscape beckoning, where you can not only build a thriving online business but also secure residency? That’s the allure of Dubai’s Freelancer Visa, a golden ticket for ambitious UK residents looking to redefine their professional and personal lives in 2025! Imagine waking up to sunshine, operating your global online venture from a dynamic hub, and benefiting from a pro-business environment. Sounds enticing, right?
For savvy UK entrepreneurs and freelancers, this isn’t just a pipe dream; it’s an increasingly viable pathway. Dubai has strategically positioned itself as a global nexus for innovation and commerce, actively attracting international talent and investment.One of the key instruments in this strategy is its dedicated Freelancer Visa programme, specifically designed to empower independent professionals and online business owners. This isn’t about escaping your responsibilities; it’s about strategically positioning yourself for greater success and a higher quality of life. Think about it: a burgeoning digital economy, attractive tax policies within designated free zones, and a cosmopolitan lifestyle – all within reach.
This comprehensive guide will navigate you through the intricacies of leveraging Dubai’s Freelancer Visa to establish and scale your online business while securing residency. We’ll delve into the “why,” the “what,” the “where,” the “when,” and the “how” of this exciting opportunity. Get ready to unlock a world of possibilities and take control of your future!
Why Dubai’s Freelancer Visa is a Smart Move for UK Residents in 2025
Several compelling factors make Dubai’s Freelancer Visa an increasingly attractive option for UK residents looking to establish or grow their online businesses and gain residency:
1. Thriving Digital Economy and Business-Friendly Environment:Dubai has made significant strides in fostering a robust digital infrastructure and a pro-business ecosystem.The government actively supports innovation, technology adoption, and entrepreneurship. This creates a fertile ground for online businesses to flourish, offering access to a dynamic market and a global network of professionals. The sheer energy and ambition palpable in Dubai can be incredibly motivating for entrepreneurs seeking growth.
2. Strategic Location and Global Connectivity:Situated at the crossroads of East and West, Dubai offers unparalleled access to global markets.Its world-class transportation infrastructure, including a major international airport and efficient logistics networks, facilitates seamless international business operations. For online businesses with a global reach, this strategic positioning can be a significant advantage, allowing for easier interaction with clients and partners across different time zones.
3. Attractive Tax Policies within Free Zones: One of the most significant draws for entrepreneurs is the favourable tax environment within Dubai’s designated free zones.Many of these zones offer 0% corporate and personal income tax, which can substantially boost profitability for your online business. This financial advantage allows for greater reinvestment and faster growth compared to higher-tax jurisdictions. Imagine the impact of zero income tax on your bottom line!
4. High Quality of Life and Cosmopolitan Environment:Dubai offers a high standard of living with modern infrastructure, world-class amenities, and a diverse and vibrant social scene. The city boasts excellent healthcare, education, and recreational facilities. For UK residents seeking a change of pace and a more cosmopolitan environment, Dubai provides a compelling lifestyle proposition. Plus, the year-round sunshine is a definite bonus!
5. Opportunity for Residency and Long-Term Stability:Unlike short-term business visas, the Freelancer Visa in Dubai offers a pathway to long-term residency, providing stability and a sense of belonging. This can be particularly appealing for individuals looking to build a long-term future for themselves and their families in a dynamic and growing international hub. Securing residency opens up numerous personal and professional opportunities.
6. Access to a Diverse Talent Pool: Dubai attracts a highly skilled and diverse international talent pool. This can be a significant advantage for online businesses looking to scale and build a strong team. The multicultural environment fosters innovation and provides access to a wide range of expertise.
7. Government Support for SMEs and Startups: The Dubai government actively supports small and medium-sized enterprises (SMEs) and startups through various initiatives, funding programmes, and incubation centres.This supportive ecosystem can provide valuable resources and networking opportunities for newly established online businesses.
Eligible Online Businesses for the Dubai Freelancer Visa
The Dubai Freelancer Visa is designed to attract a wide range of skilled professionals operating online. While specific regulations may evolve, here are some common categories of online businesses and freelance professions generally eligible for this visa:
Illustration and Animation (Online Commissions/Sales): Creating and selling digital artwork and animations.
Important Note: This list is not exhaustive, and the specific eligibility criteria can be subject to change based on the free zone authority and the prevailing regulations. It is crucial to consult with the relevant free zone authority or a professional consultancy to confirm the eligibility of your specific online business activity.
Navigating Dubai’s Free Business Zones: Your Launchpad for Success
Dubai boasts several designated free zones, each with its own specific focus and regulations. These zones offer attractive incentives, including tax exemptions, full foreign ownership, and streamlined business setup processes. Here are some of the prominent free zones that are particularly relevant for online businesses and freelancers:
1. Dubai Multi Commodities Centre (DMCC):Located in the Jumeirah Lakes Towers (JLT) area, DMCC is one of Dubai’s largest and most diverse free zones. It’s home to a wide range of businesses, including those in technology, trading, and professional services. DMCC offers a dedicated “Freelancer Package” designed to provide cost-effective business setup and licensing options for individual professionals. Their online portal and efficient processes make it a popular choice.
2. Dubai Internet City (DIC):As the name suggests, DIC is a hub for technology and internet-based companies.It hosts a large ecosystem of IT, software, e-commerce, and digital media businesses. While traditionally focused on larger companies, DIC also offers options for freelancers and smaller online ventures within its broader framework. Being part of this vibrant tech community can offer significant networking and collaboration opportunities.
3. Dubai Media City (DMC):DMC is the region’s leading hub for media and creative industries.It’s home to numerous media companies, advertising agencies, production houses, and freelance professionals in content creation, journalism, and digital media. If your online business aligns with these sectors, DMC can provide a supportive and industry-focused environment.
4. Dubai Knowledge Park (DKP):DKP is dedicated to human resource management, training, and professional development. While it might seem less directly relevant to all online businesses, it can be a good option for online educators, trainers, and e-learning content creators.
5. Meydan Free Zone: Located near the Meydan Racecourse, this free zone offers a cost-effective and relatively straightforward business setup process, including options suitable for freelancers and online businesses. It’s known for its competitive pricing and efficient services.
6. IFZA (International Free Zone Authority): IFZA is another popular choice offering competitive setup costs and a wide range of business activities suitable for online operations.They have streamlined processes and cater to international entrepreneurs.
Key Considerations When Choosing a Free Zone:
Business Activity Alignment: Ensure the free zone allows your specific online business activity under its licensing regulations.
Cost of Setup and Renewal: Compare the fees associated with registration, licensing, and annual renewal across different free zones.
Facilities and Support Services: Consider the availability of co-working spaces, business centres, and other support services you might need.
Networking Opportunities:Some free zones have stronger industry-specific communities, which can be beneficial for networking and collaboration.
Visa and Immigration Procedures: Understand the specific visa and immigration processes associated with each free zone.
It is highly recommended to research the specific offerings and regulations of each free zone thoroughly and potentially consult with business setup specialists to determine the best fit for your individual needs and online business model.
Timing Your Application: When to Make the Move
Deciding when to apply for the Dubai Freelancer Visa is a crucial aspect of your planning. Several factors should influence your timeline:
1. Business Readiness: Ideally, you should have a clear business plan, a defined online service or product offering, and ideally, some existing online presence or client base. While you can start the process with a strong concept, being prepared will streamline your application and ensure you can hit the ground running in Dubai.
2. Financial Preparedness:Setting up a business and relocating involves costs. Ensure you have sufficient funds to cover visa application fees, business registration costs, initial living expenses in Dubai, and working capital for your online venture. Research the specific costs associated with your chosen free zone and desired lifestyle.
3. Visa Processing Time: The processing time for the Freelancer Visa can vary depending on the free zone and the volume of applications. It’s prudent to factor in potential delays and allow ample time before your intended relocation date. Generally, the process can take anywhere from a few weeks to a couple of months.
4. Personal Circumstances: Consider your personal commitments, such as existing employment contracts, family arrangements, and any other obligations that might impact your ability to relocate. Plan your move in a way that minimizes disruption to your life.
Can You Apply from the UK or on a Visitor Visa in Dubai?
Applying from the UK: Yes, it is generally possible to initiate the application process for a Dubai Freelancer Visa while you are still in the UK. Most free zones have online portals and allow you to complete the initial documentation and application remotely. However, you will likely need to travel to Dubai at some point to finalise the process, undergo medical examinations, and receive your residency visa.
Applying on a Visitor Visa in Dubai: Yes, it is also possible to apply for a Freelancer Visa while you are in Dubai on a visitor visa. This is a common route for individuals who want to explore the environment and meet with free zone authorities before committing. However, it’s crucial to ensure that your visitor visa allows for a change of status and that you comply with all immigration regulations. You will typically need to undergo the application process through the chosen free zone authority while in Dubai. Be aware of the validity period of your visitor visa and ensure you have enough time to complete the Freelancer Visa process. Overstaying your visitor visa can lead to penalties.
Recommendation: Regardless of whether you apply from the UK or on a visitor visa, it is highly recommended to contact the specific free zone authority you are interested in or consult with a business setup agency to get the most up-to-date information on their application procedures and requirements for non-resident applicants.
Who is Eligible to Apply for the Freelancer Visa?
While specific eligibility criteria can vary slightly between different free zones, the general requirements for a Dubai Freelancer Visa typically include:
Professional Expertise: You must possess demonstrable skills and experience in a profession or business activity that is eligible under the free zone’s regulations (as discussed earlier). You may need to provide a portfolio, client testimonials, or other evidence of your expertise.
Educational Qualifications: Some free zones may require a minimum level of educational qualification relevant to your field. Be prepared to provide copies of your degrees or certifications.
Financial Capacity: You will need to demonstrate that you have sufficient financial resources to support yourself during the initial period of your residency and to fund your business operations. This might involve providing bank statements or a business plan with financial projections.
Clean Criminal Record: You will typically need to provide a police clearance certificate from your home country (the UK in this case) to demonstrate that you have a clean criminal record.
Medical Fitness: You will be required to undergo a medical examination in Dubai to ensure you are medically fit to reside and work in the UAE.
Passport Validity: Your passport must have a sufficient validity period (usually at least six months) at the time of application.
Business License Application: You will need to apply for a freelancer or sole establishment business license within your chosen free zone, outlining your specific business activities.
Visa Application Forms and Supporting Documents: You will need to complete the required application forms and provide various supporting documents, such as passport copies, photographs, and other documents as requested by the free zone authority.
Important Note: The specific requirements and documentation can vary. It is essential to consult the official website of your chosen free zone or contact them directly for the most accurate and up-to-date eligibility criteria. They can provide a detailed list of required documents and guide you through the process.
Your Dubai Opportunity Awaits in 2025!
The Dubai Freelancer Visa presents a compelling opportunity for UK residents to not only establish and grow their online businesses in a dynamic and supportive environment but also to secure long-term residency in a thriving global hub. The combination of a business-friendly ecosystem, attractive tax policies within free zones, a high quality of life, and the potential for global connectivity makes Dubai an increasingly attractive destination for ambitious entrepreneurs and freelancers.
While the process involves careful planning, research, and adherence to specific regulations, the rewards can be significant. Imagine operating your online empire from a sun-drenched location, benefiting from a zero-tax environment, and immersing yourself in a vibrant international culture. This isn’t just about a visa; it’s about unlocking a new chapter of opportunity and growth for your business and your life.
So, if you’re a UK resident with a thriving online business or a compelling freelance offering, 2025 could be your year to take the leap. Explore the possibilities, research the free zones, prepare your application, and embrace the exciting journey of building your online empire and securing your future in Dubai! The time to escape the ordinary and embrace extraordinary opportunities is now!
Users specifically looking for information about the Spanish blackout in the context of renewable energy and inertia
Blackout in Barcelona: A Canary in the Renewable Energy Coal Mine?
The lights flickered. Then died. Across Spain, from bustling Barcelona to the sun-drenched Andalusian coast, an unprecedented electrical outage plunged millions into darkness in late April and early May 2025. Initial reports pointed to technical glitches, but whispers in the energy sector suggest a more fundamental, and frankly, alarming cause: the intricate dance between the science of inertia and the rapid proliferation of renewable energy sources. Could the very technologies lauded as our salvation be, in their current deployment, a significant threat to the stability of our power grids? This isn’t just a Spanish problem; it’s a global wake-up call.
Is your business prepared for the next energy crisis? Get the actionable insights you need now.
This article delves deep into the potential interplay between inertia, renewable energy integration, and the Spanish blackout. We’ll explore why this isn’t an isolated incident but a looming challenge for the world’s ambitious renewable energy strategies. Buckle up, because the implications for your business, and indeed the future of global energy, are profound. We’ll not only dissect the problem but also provide actionable insights and risk control measures you need to implement now to safeguard your operations in this evolving energy landscape. Let’s get started.
Unpacking the Blackout: Inertia, Renewables, and Spain’s Electrical Infrastructure
To understand the potential link between inertia, renewable energy, and the Spanish blackout, we need to grasp some fundamental principles of electrical grid operation. Traditional power grids, heavily reliant on large synchronous generators powered by fossil fuels or nuclear energy, possess a crucial characteristic: inertia. Think of it as the spinning mass of these generators acting like a flywheel. This rotational inertia provides inherent stability to the grid. When demand for electricity suddenly increases or a fault occurs, this stored kinetic energy helps to resist rapid changes in frequency, giving grid operators precious seconds to react and balance supply and demand.
Now, enter renewable energy sources like solar and wind. While undeniably clean and essential for decarbonisation, their integration presents a significant challenge to grid inertia. Unlike those massive spinning generators, inverter-based resources (IBRs) such as solar photovoltaic (PV) systems and wind turbines are decoupled from the grid’s physical rotation through power electronic interfaces. They don’t inherently contribute the same kind of synchronous inertia.
The problem arises when the proportion of IBRs on the grid becomes substantial, as it has in Spain, a nation at the forefront of renewable energy adoption. As older, inertia-rich power plants are decommissioned and replaced by renewables, the overall inertia of the system decreases. This makes the grid more susceptible to frequency fluctuations following disturbances. A sudden loss of a large power source or a surge in demand can lead to a rapid drop in frequency that the system struggles to counteract quickly enough, potentially triggering widespread blackouts as protective mechanisms kick in to prevent damage.
While the official investigation into the Spanish blackout is ongoing, reports suggest a confluence of factors, including a sudden drop in wind power generation coinciding with peak demand and potentially exacerbated by lower system inertia. It’s a complex interplay, and attributing the outage solely to inertia and renewables would be an oversimplification. However, the event has undeniably shone a spotlight on the critical need to address the inertia challenge as we transition to a cleaner energy future.
The Global Renewable Energy Dilemma: A Problem Beyond Spain
Spain’s experience, whether definitively linked to inertia and renewables or not, serves as a stark warning for the rest of the world. Nations across the globe are aggressively pursuing ambitious renewable energy targets to combat climate change. This transition, while vital, carries inherent risks to grid stability if not managed proactively.
Consider countries like Germany, Denmark, and California, all boasting high penetrations of wind and solar power. As they continue to increase their reliance on these variable energy sources, they too will face the challenge of maintaining grid stability with reduced synchronous inertia. The intermittency of wind and solar already necessitates sophisticated forecasting and balancing mechanisms. Lower inertia amplifies the consequences of forecast errors and unexpected fluctuations.
Furthermore, the increasing electrification of transportation and heating will place even greater demands on the grid, requiring even more robust and resilient infrastructure. A grid struggling with low inertia will be less able to handle these new loads and the associated variability.
The implications are far-reaching. Businesses rely on a stable and reliable power supply for their operations. Frequent blackouts, even short-lived ones, can lead to significant economic losses, disrupted supply chains, and reputational damage. Critical infrastructure, such as hospitals, transportation systems, and data centers, are particularly vulnerable. The social and economic costs of widespread and prolonged outages are simply unacceptable in our increasingly interconnected world.
Rethinking Energy Strategies: A Global Imperative
The Spanish blackout, viewed through the lens of potential inertia-related vulnerabilities, underscores the urgent need for a fundamental shift in how countries approach their energy strategies. Simply deploying more renewable generation is not enough. We need a holistic approach that prioritises grid stability alongside decarbonisation. Here’s how energy strategies need to evolve globally:
1. Prioritising Grid Modernisation: Investments in modernising grid infrastructure are paramount. This includes upgrading transmission lines, deploying advanced sensors and control systems, and enhancing grid automation to improve responsiveness and resilience.
2. Integrating Energy Storage Solutions: Large-scale battery storage and other forms of energy storage (like pumped hydro) are crucial for decoupling electricity supply and demand. Storage can absorb excess renewable energy during periods of high generation and release it when needed, providing essential grid services, including synthetic inertia.
3. Developing Synthetic Inertia Capabilities: Inverter technology is rapidly evolving. Grid-forming inverters, unlike conventional grid-following inverters, can actively regulate voltage and frequency, effectively mimicking the behaviour of synchronous generators and providing synthetic inertia to the grid. Mandating and incentivising the deployment of grid-forming inverters for new renewable energy projects is essential.
4. Enhancing Demand-Side Management: Implementing dynamic pricing mechanisms and incentivising consumers to adjust their electricity consumption based on grid conditions can help to smooth out demand peaks and reduce stress on the system. Smart grids and smart appliances will play a key role here.
5. Diversifying Renewable Energy Mix:Relying too heavily on a single renewable energy source can increase vulnerability to weather-related fluctuations. Diversifying the energy mix to include a combination of solar, wind, hydro, geothermal, and biomass can enhance overall system reliability.
6. Strengthening Interconnections: Robust interconnections between regional and national grids allow for the sharing of resources and the mutual support during periods of stress. Investing in and strengthening these interconnections enhances overall system resilience.
7. Implementing Robust Grid Codes and Standards: Grid codes need to be updated to reflect the increasing penetration of IBRs and to mandate the provision of essential grid services, including synthetic inertia and frequency response, from renewable energy generators.
8. Investing in Research and Development: Continuous innovation in grid technologies, energy storage, and advanced control systems is crucial for addressing the evolving challenges of integrating high levels of renewable energy.
9. Fostering Collaboration and Knowledge Sharing:International collaboration and the sharing of best practices are essential for accelerating the transition to a stable and sustainable energy future. Countries that have already achieved high renewable penetration can offer valuable lessons learned.
When Does This Change Need to Happen?
The answer is unequivocally: now! The Spanish blackout serves as a potent reminder that the inertia challenge is not a future problem; it is a present reality. Waiting to address these issues until more significant grid instability occurs would be a catastrophic error with profound economic and social consequences. Proactive measures, implemented urgently, are essential to ensure a smooth and reliable transition to a renewable energy-powered world.
Who Needs to Change and How?
The responsibility for this strategic shift lies with a multitude of actors:
Governments: They need to set clear policy signals, establish supportive regulatory frameworks, provide funding for grid modernisation and research, and mandate the adoption of grid-friendly technologies. They must also foster international collaboration.
Grid Operators (Transmission System Operators – TSOs): TSOs need to adapt their operational procedures, invest in advanced grid management tools, and work closely with renewable energy developers to ensure grid stability. They must also develop and enforce updated grid codes.
Renewable Energy Developers: Developers need to embrace and invest in technologies that can provide essential grid services, such as grid-forming inverters and energy storage. They need to move beyond simply generating energy and become active participants in grid stabilisation.
Technology Providers: Innovation in areas like energy storage, power electronics, and grid management software is crucial. Technology providers need to accelerate the development and deployment of cost-effective and reliable solutions.
Energy Consumers (Businesses and Individuals): Through demand-side management programmes and investments in smart technologies, consumers can play a role in enhancing grid stability and reducing peak demand.
The “how” involves a multi-pronged approach:
Policy and Regulation: Implementing clear targets, incentives, and mandates for grid modernisation, energy storage, and grid-forming technologies.
Investment: Allocating significant public and private capital towards grid upgrades, research and development, and the deployment of enabling technologies.
Collaboration: Fostering communication and coordination between governments, regulators, grid operators, developers, and researchers.
Education and Awareness: Raising awareness among stakeholders and the public about the challenges and opportunities associated with the energy transition.
The Perils of Inaction: Why Delay is Not an Option
Failing to proactively address the inertia challenge and modernise energy strategies will lead to a cascade of problems:
Increased Frequency and Severity of Blackouts: As renewable penetration increases and inertia decreases, the grid will become increasingly vulnerable to disturbances, leading to more frequent and potentially widespread power outages.
Economic Disruption: Blackouts cause significant economic losses due to business interruptions, spoiled goods, and damage to equipment. Frequent outages will undermine investor confidence and hinder economic growth.
Threats to Critical Infrastructure: Unreliable power supply can have devastating consequences for essential services like healthcare, transportation, communication, and water treatment.
Hindered Renewable Energy Deployment: Grid instability concerns could lead to restrictions on the deployment of new renewable energy projects, slowing down the transition to a clean energy future and undermining climate goals.
Increased Costs: Reactive measures taken after significant grid failures are typically far more expensive than proactive investments in grid modernisation and stability solutions.
Erosion of Public Trust: Frequent and prolonged blackouts can erode public trust in the energy system and the ability of governments and utilities to manage the transition effectively.
The Spanish blackout, whether directly caused by inertia issues or not, serves as a stark reminder of the potential vulnerabilities in our rapidly evolving energy landscape. Ignoring the science of inertia and failing to adapt our energy strategies is a gamble we cannot afford to take.
9 Risk Control Actions for Business Leaders: Protecting Your Enterprise Now
The potential for increased grid instability due to the integration of renewable energy and the associated inertia challenges presents significant enterprise risks. Prudent business leaders need to take proactive steps now to mitigate these risks and ensure business continuity. Here are nine crucial risk control actions:
Invest in Uninterruptible Power Supplies (UPS) and Backup Generators: For critical operations, ensure robust UPS systems are in place to bridge short-term outages. Supplement this with backup generators fueled by diverse sources (where feasible) to maintain essential functions during longer disruptions. Regularly test and maintain these systems.
Develop Comprehensive Business Continuity and Disaster Recovery Plans: These plans should explicitly address potential power outages of varying durations. Include detailed procedures for communication, data backup and recovery, alternative work locations, and employee safety.
Implement Energy Monitoring and Management Systems: Understand your energy consumption patterns and identify critical loads. Advanced monitoring systems can provide early warnings of potential grid instability and allow for proactive load shedding if necessary.
Explore On-Site Renewable Energy Generation with Storage: Consider investing in on-site solar PV with battery storage. This can provide a degree of energy independence and resilience, particularly during grid outages. Evaluate the economic feasibility and grid interconnection requirements carefully.
Engage with Your Utility and Industry Associations: Stay informed about grid modernisation plans, potential reliability challenges, and demand response programs in your region. Participate in industry discussions and advocate for policies that enhance grid resilience.
Diversify Your Operational Footprint (Where Feasible): If your business has multiple locations, consider the energy reliability profiles of each region. Diversifying operations can reduce the impact of localised outages.
Review Insurance Coverage: Ensure your business insurance policies adequately cover losses resulting from power outages, including business interruption and damage to equipment. Understand the terms and limitations of your coverage.
Train Employees on Emergency Procedures:Conduct regular training sessions for employees on how to respond safely and effectively during a power outage. This includes procedures for communication, evacuation (if necessary), and the operation of backup systems.
Advocate for Resilient Energy Policies: Engage with policymakers and advocate for investments in grid modernisation, energy storage, and policies that prioritise grid stability alongside renewable energy deployment. Your voice as a business leader can influence critical decisions.
The dangers and potential benefits of nano fabrication
Hold on tight, because the future of your business – and maybe even everything else – is about to get seriously Nano-fied! Forget incremental improvements; we’re talking about a technological leap so massive it makes the internet revolution look like dial-up. I’m talking about nanofabrication, and it’s not some sci-fi pipe dream anymore. It’s knocking on the door, and if you’re not ready, traditional fabricators will be the least of your worries!
Imagine having a machine, right in your factory or even your office, that can build things atom by atom. Anything. From the strongest materials imaginable to personalised medicines designed just for you, to electronics so tiny they’re practically invisible. Sounds like magic, right? Well, that’s the potential of nanofabrication, and it’s closer than you think.
Why should you, a busy business leader, care about something that sounds like it belongs in a science fiction movie? Because this isn’t just about cool gadgets. It’s about a fundamental shift in how we make things, who can make them, and what is even possible. It’s a chance to leapfrog your competition, create entirely new markets, and solve problems we can only dream of tackling today. But it also carries risks so profound they could reshape the very fabric of our economy and society.
Think about it: what happens to traditional manufacturing when anyone can essentially “print” products with superior properties on demand? What happens to the pharmaceutical industry when personalised medicine becomes the norm, created at the nanoscale? What new security threats emerge when materials can be engineered at the atomic level?
This isn’t just a technological trend; it’s a potential industrial and societal earthquake. And you need to be ready to navigate it.
In this article, I’m going to break down what nanofabrication is, why it’s on the cusp of becoming a reality, and the mind-blowing opportunities and terrifying threats it presents. Then, I’ll give you nine concrete, actionable steps you can take right now to understand, prepare for, and even capitalise on this coming revolution in the UK. Forget incremental improvements; we’re talking about a paradigm shift! Let’s dive in before it’s too late!
Nanofabrication: Your Personal Genie’s Lamp is Almost Here!
Okay, let’s get down to brass tacks. What exactly is this “nanofabrication” I keep talking about? Simply put, it’s the science and technology of designing and creating structures, devices, and systems at the nanoscale – that’s one billionth of a metre! To give you some perspective, a nanometer is about the width of a few atoms lined up. At this scale, the properties of materials can change dramatically. Gold, which is typically yellow, can appear red or green at the nanoscale!
Now, how do we even think about building things at this scale? There are two main approaches:
Top-down nanofabrication: This is like taking a block of something and carving away material to create nanoscale features. Think of a sculptor working with incredibly fine tools. Current microfabrication techniques used to make computer chips are a form of top-down processing, but we’re pushing the limits to achieve even smaller dimensions.
Bottom-up nanofabrication: This is where things get really interesting. It’s like building with atomic LEGOs! We’re talking about assembling structures atom by atom or molecule by molecule. This could involve self-assembly, where molecules spontaneously arrange themselves into desired patterns, or using incredibly precise tools to place individual atoms.
While both approaches are being actively researched, bottom-up nanofabrication is often seen as the “holy grail” because it offers the potential to create materials and devices with unprecedented precision and control over their properties. Imagine designing a material with exactly the strength, conductivity, and flexibility you need, atom by atom!
Why is this “nano-magic” within touching distance of being real?
You might be thinking, “Building things atom by atom? That sounds like something out of Star Trek!” And you’re right, it does sound futuristic. But the progress in several key areas is making it increasingly likely that we’ll see practical nanofabrication technologies in the coming decades, perhaps even sooner than you think!
Advancements in Microscopy: We can now see and even manipulate individual atoms using powerful microscopes like Scanning Tunneling Microscopes (STMs) and Atomic Force Microscopes (AFMs). These aren’t just for looking; they can be used as incredibly fine tools to move atoms around.
Self-Assembly Breakthroughs:Scientists are making huge strides in understanding and controlling how molecules self-assemble. Imagine designing molecules that automatically snap together in a specific way to form nanoscale structures! This could revolutionise manufacturing by allowing us to “grow” complex devices.
Progress in Nanomaterials: We’re already seeing the impact of nanomaterials like graphene and carbon nanotubes, which have extraordinary properties. Nanofabrication will allow us to precisely engineer these and other nanomaterials for specific applications.
Convergence with Biotechnology:The ability to work at the nanoscale is crucial for advances in medicine. Nanoparticles are already being used for drug delivery, and nanofabrication could lead to revolutionary diagnostic tools and even the creation of artificial biological systems.
Government and Private Investment:There’s significant investment pouring into nanotechnology research and development worldwide, recognising its potential to drive economic growth and solve global challenges. This funding is accelerating the pace of innovation.
So, while we might not have a fully functional “replicator” from Star Trek just yet, the fundamental science is advancing rapidly. The ability to manipulate matter at the nanoscale is no longer a distant dream; it’s a tangible goal that researchers around the world are actively pursuing.
The Double-Edged Sword: Salvation and Existential Threat
Now, let’s talk about why this nanofabrication revolution is both an incredible opportunity and a potentially terrifying threat for your business and for society as a whole.
The Chance of Salvation: Your Business Transformed
For your business, access to nanofabrication could be a game-changer in ways you can barely imagine:
Unprecedented Product Innovation: Imagine creating materials with properties that are currently impossible – stronger than steel but lighter than aluminum, self-healing surfaces, or materials that can adapt to their environment. This opens the door to entirely new product categories and functionalities.
Personalised and On-Demand Manufacturing: Nanofabrication could enable highly customised products tailored to individual needs, produced on demand with minimal waste. Think personalised medicines created at the point of care or bespoke materials engineered for a specific application. This could revolutionise supply chains and inventory management.
Miniaturisation and Efficiency:Nanoscale manufacturing allows for the creation of incredibly small and efficient devices. Imagine sensors so tiny they can be embedded virtually anywhere, or electronic components with unimaginable processing power in a minuscule space. This has huge implications for industries from electronics to healthcare.
New Materials and Processes: Nanofabrication could unlock the creation of entirely new materials with unique properties, leading to breakthroughs in energy storage, catalysis, and many other fields. It could also enable more sustainable and environmentally friendly manufacturing processes with reduced waste and energy consumption.
Competitive Advantage: Early adopters of nanofabrication technologies will gain a significant competitive edge. They will be able to offer products and services that their competitors simply cannot match, potentially disrupting entire industries and creating new market leaders.
For a UK business, being at the forefront of this technology could revitalise manufacturing, create high-skilled jobs, and position the nation as a global leader in innovation. Access to advanced nanofabrication facilities and expertise could attract investment and drive economic growth.
The Potential Existential Threat: A World Reshaped – For Better or Worse?
However, the power to manipulate matter at the atomic level also comes with significant risks:
Disruption of Traditional Industries: As nanofabrication becomes more widespread, traditional manufacturing industries that rely on economies of scale and established processes could face existential threats. If anyone can “print” high-quality goods on demand, the need for large factories and complex supply chains could diminish.
Economic Inequality: Access to nanofabrication technologies could be unevenly distributed, potentially exacerbating economic inequality. Those who control these powerful tools could gain even more power, while others are left behind.
Security Risks: The ability to create materials and devices with unprecedented properties could also be exploited for malicious purposes. Imagine nanoscale weapons that are virtually undetectable or self-replicating nanobots that could pose a serious threat.
Environmental Concerns: While nanofabrication could lead to more sustainable manufacturing in the long run, the development and use of certain nanomaterials could also pose new environmental and health risks if not managed carefully.
Ethical Dilemmas: The ability to manipulate life at the nanoscale raises profound ethical questions. What are the limits of what we should create or modify? How do we ensure that these technologies are used responsibly and for the benefit of humanity?
The “Traditional Fabricator” Scenario: The initial analogy of “traditional fabricators” highlights a key concern. If competitors gain access to advanced nanofabrication capabilities before you do, they could rapidly erode your market share by producing superior, cheaper, or entirely novel products. This isn’t just about keeping up; it’s about survival.
For the UK, failing to engage with and regulate nanofabrication effectively could lead to economic disadvantage, security vulnerabilities, and missed opportunities for innovation and growth.
Nine Things Business Leaders Should Be Aware Of (Even If You Think This is Too Complicated!)
Okay, I know this might sound like a lot to take in. But trust me, as a business leader in the UK, you need to start thinking about this now. Here are nine crucial things you should be aware of about nanofabrication, even if you feel like your brain is already full:
It’s Not Just Science Fiction Anymore: Stop thinking of nanotechnology as something that will happen in a distant future. The underlying science is advancing rapidly, and we’re seeing real-world applications emerge. Keep an eye on developments in materials science, advanced manufacturing, and biotechnology – these are often leading indicators.
It Will Disrupt Your Industry (Eventually): No matter what business you’re in, nanofabrication has the potential to disrupt it. Think about how your products are made, what materials you use, and how you reach your customers. Could a competitor using nanofabrication create a better, cheaper, or more personalised alternative? Start asking these “what if” questions now.
Ignoring It is Not a Strategy: Pretending this isn’t happening won’t make it go away. In fact, it will put you at a significant disadvantage when your competitors start leveraging these technologies. Proactive engagement, even at a basic level, is crucial.
Talent is Key (Even if You Don’t Understand the Science): You don’t need to become a nanoscientist overnight, but you do need to understand the importance of talent. Start thinking about how you can attract and retain individuals with expertise in related fields like materials science, advanced manufacturing, and data science. Collaborating with universities and research institutions could be a good starting point.
Intellectual Property Will Be More Critical (and More Complex): If you can create anything at the atomic level, protecting your innovations becomes paramount. Existing IP frameworks might not be sufficient to address the unique challenges of nanofabricated products and processes. Start thinking about your IP strategy in this new context.
Regulation Will Be a Moving Target (But You Need to Engage): Governments around the world are grappling with how to regulate nanotechnology. This will likely evolve as the technology matures. Stay informed about potential regulations in the UK and engage in the policy debate to ensure a level playing field and responsible innovation.
Collaboration is Essential (You Can’t Do This Alone): The development and adoption of nanofabrication will require collaboration across disciplines and sectors. Consider forming partnerships with research institutions, other businesses, and government agencies to stay informed and explore potential opportunities.
Sustainability Could Be a Major Driver (and Benefit):Nanofabrication offers the potential for more sustainable manufacturing processes with reduced waste, energy consumption, and the use of scarce resources. Explore how these technologies could align with your sustainability goals and create new value for your business.
The Pace of Change Will Be Faster Than You Think (So Start Now!):Technological advancements are accelerating. What seems like science fiction today could be a reality much sooner than you expect. Don’t wait until it’s too late to start understanding and preparing for the nanofabrication revolution.
Protecting and Growing Your Business with Nanofabrication in the UK: Actionable Steps
So, how can you, as a business leader in the UK, not just survive but thrive in this coming era of nanofabrication? Here are some actionable steps you can take:
Invest in Education and Awareness: Dedicate resources to understanding the potential of nanofabrication for your industry. This could involve attending industry conferences, subscribing to relevant publications, and even bringing in experts for internal workshops. The goal is to build a foundational understanding within your leadership team.
Scan the Horizon for Emerging Applications: Actively monitor research and development in nanofabrication relevant to your sector. Identify potential applications that could create new products, improve existing ones, or streamline your processes. Look at patent filings, scientific publications, and news from innovative startups.
Explore Potential Collaborations: Reach out to universities and research institutions in the UK that are leading in nanotechnology research. Explore opportunities for joint projects, sponsored research, or access to specialised facilities and expertise. Organisations like the Knowledge Transfer Network (KTN) can help facilitate these connections.
Consider Strategic Investments (When the Time is Right): As nanofabrication technologies mature and become more commercially viable, consider making strategic investments in relevant equipment, processes, or startups. This requires careful due diligence and a long-term perspective. Government grants and funding initiatives for advanced manufacturing might be available.
Focus on High-Value, Differentiated Products:Nanofabrication excels at creating products with unique properties and high levels of customisation. Shift your focus towards developing and marketing such products that can command premium prices and are difficult for competitors using traditional methods to replicate.
Build a Future-Ready Workforce: Invest in training and upskilling your workforce to prepare for the skills needed in a nanofabrication-enabled economy. This includes expertise in materials science, data analysis, automation, and potentially even nanoscale engineering. Consider apprenticeships and partnerships with educational institutions.
Strengthen Your Intellectual Property Strategy: Review your current IP strategy and consider how to protect innovations arising from nanofabrication. This might involve exploring new types of patents or developing strong trade secrets. Seek advice from IP specialists with expertise in nanotechnology.
Engage with Policymakers and Regulators: Participate in discussions and consultations related to the regulation of nanotechnology in the UK. Advocate for policies that promote responsible innovation while creating a supportive environment for businesses to adopt these technologies. Industry bodies and trade associations can play a key role here.
Embrace a Culture of Innovation and Experimentation: Nanofabrication opens up a world of possibilities. Foster a culture within your organisation that encourages experimentation, risk-taking, and the exploration of unconventional ideas. Create dedicated teams or initiatives to explore the potential of nanotechnology for your business.
The age of nanofabrication is dawning. It presents both unprecedented opportunities and potentially devastating threats. By understanding the fundamentals, staying informed about developments, and taking proactive steps now, UK business leaders can position themselves not just to survive, but to thrive in this revolutionary new landscape. Don’t wait for the genie to appear; start exploring the lamp today!
Protect and grow your business with BusinessRiskTV
Is M2 money supply in U.S. increasing and if so what does it mean to you?
Yes, the M2 money supply in the U.S. has increased over the last 6 months. The year-over-year increase in January 2025 was reported at 3.9%, and in February 2025 at 3.88%. This indicates that the amount of liquid money in the U.S. economy has been expanding.
Is the increase in M2 money supply significant?
The significance of the recent increase in the U.S. M2 money supply over the last six months is debatable and depends on the context and what you’re comparing it to. Here’s a breakdown of why:
Arguments for it being moderately significant:
Reversal of Contraction: This increase follows a period in 2023 and early 2024 where the M2 money supply actually contracted year-over-year. This period of contraction was the largest drop seen since the Great Depression. Therefore, the current growth represents a significant turnaround from that trend.
Year-over-Year Growth:The year-over-year growth rate in February 2025 was 3.88%. While not exceptionally high historically, it is positive and a considerable shift from the negative growth rates experienced in the previous year. This suggests a move away from monetary tightening.
Consistent Upward Trend: The month-over-month increases over the last six months indicate a sustained period of expansion in the amount of liquid money in the economy.
Potential Inflationary Pressure (with a lag): Historically, rapid increases in money supply have been linked to inflationary pressures, although the relationship isn’t always direct or immediate. Some economists believe that the recent growth could contribute to inflation in the future, although others note that the relationship is “long and variable.”
Arguments for it being less significant or within a moderate range:
Lower than Long-Term Average:The current year-over-year growth rate of 3.88% is still lower than the long-term average M2 growth rate in the U.S., which is around 6.86%. This suggests that while it’s growing, it’s not growing at an exceptionally rapid pace compared to historical norms.
Moderate Month-over-Month Increases: While positive, the month-over-month increases have been relatively moderate, generally under 0.5%. This indicates a gradual rather than a sudden surge in money supply.
Still Below Post-Pandemic Peaks: The M2 money supply reached very high levels during the COVID-19 pandemic. While the recent increase is notable, it hasn’t pushed M2 back to those peak growth rates.
Focus on Broader Economic Context: The significance of M2 growth needs to be considered alongside other economic indicators like GDP growth, inflation, unemployment, and interest rates. A moderate increase in M2 might be seen as supportive of economic growth if inflation remains under control.
The increase in the U.S. M2 money supply over the last six months is moderately significant primarily because it marks a clear end to a period of contraction and indicates a return to positive year-over-year growth. However, its significance is tempered by the fact that the growth rate is still below the historical average and the month-over-month increases have been gradual.
The global economy is a complex and interconnected system, with money supply playing a crucial role in its functioning. The amount of money in circulation, or the money supply, has a significant impact on various aspects of the economy, including inflation, interest rates, and economic growth. In this article, we will explore the benefits of a higher money supply for businesses and consumers, focusing on the effects of M2 money supply on the global economy.
What is M2 Money Supply?
M2 money supply is a broad measure of the money supply that includes all currency in circulation, checking account deposits, and most savings accounts. It is a key indicator of the overall liquidity in the economy and is closely monitored by central banks and economists.
The Benefits of a Higher M2 Money Supply
A higher M2 money supply can have several benefits for businesses and consumers. One of the primary benefits is that it can stimulate economic growth. When there is more money in circulation, people have more money to spend, which can lead to increased demand for goods and services. This increased demand can encourage businesses to invest in new equipment and hire more workers, leading to job creation and economic expansion.
Another benefit of a higher M2 money supply is that it can help to reduce unemployment. When businesses are expanding and hiring more workers, the unemployment rate tends to decline. This can lead to increased consumer confidence and spending, further stimulating the economy.
A higher M2 money supply can also help to reduce interest rates. When there is more money available in the economy, the cost of borrowing money tends to decrease. This can make it easier for businesses to invest in new projects and for consumers to make large purchases, such as homes or cars.
The Relationship Between M2 Money Supply, Cryptocurrencies, and the S&P 500
To better understand the impact of M2 money supply on the global economy, it is important to consider its relationship with other asset classes, such as cryptocurrencies and the S&P 500.
M2 Money Supply and Cryptocurrencies
Cryptocurrencies are a relatively new asset class that has gained significant popularity in recent years. They are digital or virtual currencies that use cryptography for security. Cryptocurrencies are not backed by any government or central bank, and their value is determined by supply and demand.
The relationship between M2 money supply and cryptocurrencies is complex and multifaceted. Some economists argue that a higher M2 money supply can lead to increased investment in cryptocurrencies. This is because investors may seek alternative assets to hedge against inflation, and cryptocurrencies can be seen as a safe haven asset.
However, others argue that the relationship between M2 money supply and cryptocurrencies is not as clear-cut. They point out that cryptocurrencies are still a relatively new and volatile asset class, and their value can be influenced by a variety of factors, including regulatory developments, technological advancements, and market sentiment.
M2 Money Supply and the S&P 500
The S&P 500 is a stock market index that tracks the performance of 500 of the largest companies in the United States. It is widely regarded as a benchmark for the overall health of the U.S. economy.
The relationship between M2 money supply and the S&P 500 is also complex. Historically, there has been a positive correlation between the two. This means that when M2 money supply increases, the S&P 500 tends to also increase. This is because a higher money supply can lead to increased economic growth and corporate profits, which can boost stock prices.
However, the relationship between M2 money supply and the S&P 500 is not always linear. Other factors, such as interest rates, inflation, and geopolitical events, can also influence stock prices.
Does an Increase in M2 Result in Increased Business Activity on the High Street?
The high street is a term used to refer to the main shopping streets in towns and cities. It is home to a variety of businesses, including retail stores, restaurants, and cafes.
The relationship between M2 money supply and business activity on the high street is complex and multifaceted. In theory, a higher M2 money supply should lead to increased consumer spending, which would benefit high street businesses. However, the reality is often more nuanced.
Several factors can influence the impact of M2 money supply on high street businesses. These include the overall economic climate, consumer confidence, and the availability of alternative shopping options, such as online shopping.
In addition, the specific mix of businesses on the high street can also play a role. Businesses that sell essential goods and services, such as groceries and pharmacies, may be less affected by fluctuations in M2 money supply than businesses that sell discretionary items, such as clothing and electronics.
How to Take Advantage of an Increase in M2 Money Supply to Grow Your SME Business
If you are an SME business owner, there are several things you can do to take advantage of an increase in M2 money supply.
Invest in Marketing and Advertising: When consumers have more money to spend, they are more likely to make discretionary purchases. Investing in marketing and advertising can help you reach new customers and increase sales.
Expand Your Product or Service Offerings: If you can identify new products or services that are in demand, you can expand your business and capture a larger share of the market.
Improve Your Customer Service: Providing excellent customer service can help you retain existing customers and attract new ones.
Invest in Technology: Technology can help you improve your efficiency and productivity, which can lead to increased profitability.
Offer Discounts and Promotions: Offering discounts and promotions can attract new customers and encourage existing customers to spend more.
Build Strong Relationships with Your Suppliers: Building strong relationships with your suppliers can help you secure better deals and ensure that you have the inventory you need to meet demand.
Monitor Your Cash Flow: It is important to monitor your cash flow carefully to ensure that you have the financial resources you need to grow your business.
Diversify Your Revenue Streams:Diversifying your revenue streams can help you reduce your risk and ensure that your business is more resilient to economic downturns.
By following these tips, you can take advantage of an increase in M2 money supply to grow your SME business.
The M2 money supply is a complex and important economic indicator. It can have a significant impact on businesses and consumers. By understanding the relationship between M2 money supply and other economic factors, you can make informed decisions about your business and financial planning.
What are implications for the rest of the world of U.S. increased M2 over last 6 months
The increase in the U.S. M2 money supply over the last six months has several potential implications for the rest of the world, though the exact magnitude and direction of these effects are complex and subject to ongoing debate among economists. Here are some key implications:
1. Potential for Increased Global Inflation:
Transmission of Inflation: A larger pool of U.S. dollars could, theoretically, lead to increased demand for goods and services globally. If global supply cannot keep pace with this increased demand, it could contribute to inflationary pressures in other countries. This is particularly relevant for countries with strong trade ties to the U.S. or those whose currencies are closely linked to the dollar.
Import Prices: If the increased M2 in the U.S. eventually leads to higher inflation there, it could translate to higher prices for U.S. exports, impacting import costs for other nations.
Commodity Prices: As the U.S. dollar is the dominant currency for pricing many global commodities, an increase in the dollar supply (even if not immediately inflationary in the U.S.) could, over time, contribute to higher commodity prices in local currencies worldwide.
2. Impact on Exchange Rates:
Dollar Depreciation (Potential): Generally, an increase in the supply of a currency can lead to its depreciation relative to other currencies. If the recent increase in M2 is perceived as inflationary or as a loosening of monetary policy in the long run, it could put downward pressure on the U.S. dollar’s exchange rate.
Impact on Export Competitiveness: A weaker dollar would make U.S. exports cheaper for buyers in other countries, potentially increasing U.S. export volumes and impacting the competitiveness of domestic industries in those countries. Conversely, U.S. imports would become more expensive.
Currency Fluctuations and Volatility: Significant changes in the U.S. M2 and the dollar’s value can contribute to volatility in global currency markets, creating uncertainty for businesses engaged in international trade and investment.
3. Effects on Global Financial Markets:
Capital Flows: An increase in U.S. M2 could influence global capital flows. If investors anticipate higher inflation or lower real returns in the U.S., they might seek investment opportunities in other markets, potentially leading to increased capital inflows in some countries and outflows in others.
Interest Rates: U.S. monetary policy, which can be influenced by M2 levels, has a significant impact on global interest rates. If the increase in M2 signals a more accommodative stance, it could keep U.S. interest rates lower for longer, potentially influencing borrowing costs and asset valuations globally. Conversely, if it’s seen as a precursor to future tightening to combat inflation, it could lead to expectations of higher global interest rates.
Asset Prices: Changes in U.S. liquidity and interest rates can affect asset prices worldwide, including stocks, bonds, and real estate. Increased U.S. M2 could initially support higher asset prices globally due to increased liquidity and investor sentiment, but this could be reversed if inflation concerns rise.
4. Implications for Developing Economies:
Debt Burden: Many developing countries hold debt denominated in U.S. dollars. A depreciation of the dollar could ease their debt burden in local currency terms. However, higher U.S. inflation leading to higher global interest rates could increase their debt servicing costs.
Trade Dependence: Developing economies heavily reliant on exports to the U.S. could see increased demand if the higher M2 translates to stronger U.S. consumer spending. However, they would also face higher import costs if U.S. inflation rises.
Financial Stability: Emerging markets can be particularly vulnerable to capital flow volatility caused by shifts in U.S. monetary policy and liquidity conditions.
5. Influence on Other Central Banks:
Policy Responses: Other central banks will closely monitor the U.S. M2 growth and its impact on inflation and exchange rates. They may need to adjust their own monetary policies in response to maintain price stability and manage their exchange rates. This could involve tightening or loosening monetary policy, intervening in currency markets, or adjusting capital controls.
Coordination Challenges: Divergent monetary policy responses among major central banks due to varying domestic conditions and interpretations of U.S. M2 growth could lead to increased global economic and financial instability.
Important Considerations:
Velocity of Money:The actual impact of increased M2 depends on the velocity of money – how quickly that money circulates through the economy. If the velocity remains low, the inflationary impact might be muted.
Global Economic Conditions: The effects of U.S. M2 growth will also be shaped by the overall state of the global economy, including growth rates, supply chain dynamics, and geopolitical factors.
Federal Reserve Actions: The U.S. Federal Reserve’s response to the increased M2 will be crucial. If the Fed takes steps to manage inflation expectations and potentially tighten monetary policy in the future, it could offset some of the inflationary pressures and exchange rate effects.
The recent increase in the U.S. M2 money supply has the potential to create ripple effects across the global economy, primarily through inflation, exchange rates, and financial market channels. However, the precise nature and magnitude of these implications are uncertain and will depend on a multitude of interacting factors and the responses of policymakers worldwide. Close monitoring of these developments is essential for businesses, investors, and governments globally.
M2 in U.S. is increasing. Increasing M2 is another factor that points to higher inflation in U.S. and worldwide. How central banks and commercial banks react to higher inflation is political as much as economics. Business leaders On The High Street should be reacting now to the change from 2024 where there was an enormous contraction in money supply to a lot more money sloshing around worldwide economy and this fact’s impact on the economy and their business in particular.
Future-Proofing Your Empire: Tokenisation, Blockchain & Crypto – The UK Business Revolution is Here!
Are you ready for a seismic shift? The business landscape is evolving at warp speed, and clinging to old ways is a recipe for obsolescence. Consider this: cybercrime in the UK cost businesses an estimated £17.2 billion in the last year alone! (Source: YouGov Cyber Security Breaches Survey 2024). That’s not just a number; it’s a wake-up call. Ignoring the transformative power of tokenisation, blockchain, and cryptocurrency isn’t just a missed opportunity; it’s an open invitation to disruption, data breaches, and ultimately, business failure.
This isn’t about fleeting trends or tech buzzwords. This is about survival and exponential growth in an increasingly digital and interconnected world. We’re talking about fortifying your business against modern threats while unlocking unprecedented avenues for expansion and customer engagement. I know it sounds like a bold claim, but stick with me, and I’ll show you how these cutting-edge technologies are no longer futuristic fantasies but essential tools for any forward-thinking UK business.
This article dives deep into the critical role of tokenisation, blockchain, and cryptocurrency in safeguarding your business and accelerating its growth trajectory in the UK. We’ll dissect the inherent risks of inaction, explore the tantalising opportunities these technologies unlock, and, crucially, provide nine concrete examples of how UK businesses, just like yours, can implement them today. Forget the jargon; we’re talking practical strategies, actionable insights, and a roadmap to a more secure, efficient, and prosperous future. Let’s get started!
Part 1: The Looming Storm – Risk Analysis: Why These Technologies Are Critical for the Future of UK Businesses
The digital age, while brimming with potential, has also ushered in an era of unprecedented risks for businesses. Ignoring these threats is akin to sailing into a hurricane without checking the forecast. Let’s break down the critical risks that make the adoption of tokenisation, blockchain, and cryptocurrency not just advantageous, but increasingly essential for survival in the UK market.
1.1 The Relentless Rise of Cybercrime: A Clear and Present Danger
The statistic I mentioned earlier – £17.2 billion lost to cybercrime – paints a stark picture. Data breaches are becoming more frequent, sophisticated, and devastating. Think about it: sensitive customer data, intellectual property, financial records – all prime targets for malicious actors. The consequences are catastrophic: reputational damage that can take years to repair, hefty fines under GDPR and other regulations, operational disruptions, and a loss of customer trust that can be fatal.Traditional security measures are often reactive, playing a constant game of catch-up with evolving threats.We need a more proactive and resilient approach, and that’s where blockchain’s inherent security shines.
1.2 The Inefficiencies of Traditional Systems: Dragging Your Business Down
Consider the clunky processes that plague many businesses: manual record-keeping, slow and expensive cross-border payments, opaque supply chains riddled with intermediaries, and outdated loyalty programmes that fail to truly engage customers. These inefficiencies not only drain resources and stifle innovation but also create vulnerabilities. Manual errors can lead to financial discrepancies and security loopholes.Lack of transparency in supply chains can mask unethical practices and expose your business to reputational risks. Antiquated systems simply can’t keep pace with the demands of a rapidly evolving digital marketplace.
1.3 The Growing Demand for Transparency and Trust: Empowering Your Customers
In today’s world, consumers are increasingly savvy and demanding. They want to know where their products come from, how their data is being used, and they expect businesses to operate with integrity and transparency. Opaque systems breed distrust and can alienate customers. Blockchain, with its immutable and auditable nature, offers a powerful solution to build trust and demonstrate transparency across various aspects of your business, from supply chain provenance to data management.
1.4 The Competitive Imperative: Staying Ahead in a Global Marketplace
The UK business landscape is fiercely competitive, not just domestically but also on a global scale. Businesses that fail to adopt innovative technologies risk being left behind by more agile and tech-savvy competitors. Tokenisation can unlock new funding opportunities and customer engagement strategies that traditional methods simply can’t match. Cryptocurrency facilitates faster and cheaper international transactions, opening up new markets and streamlining global operations. Ignoring these advancements means handing a competitive advantage to those who embrace them.
1.5 The Evolving Regulatory Landscape: Preparing for the Future
While the regulatory landscape for blockchain and cryptocurrency is still evolving in the UK, the direction of travel is clear. Governments and regulatory bodies are increasingly recognising the potential of these technologies and are working towards establishing frameworks for their adoption. Businesses that proactively engage with these technologies will be better positioned to adapt to future regulations and potentially even shape them. Waiting until regulations are fully established could mean missing out on early-mover advantages.
In essence, the risks of not adopting tokenisation, blockchain, and cryptocurrency are mounting. Cyber threats are escalating, inefficiencies are hindering growth, customer expectations for transparency are rising, competition is intensifying, and the regulatory landscape is shifting. These technologies offer a powerful arsenal to mitigate these risks and build a more resilient and future-proof business.
Part 2: Unleashing Untapped Potential – Growth Opportunities Through Tokenisation, Blockchain & Cryptocurrency
While the defensive advantages of these technologies are compelling, their potential for accelerating business growth is equally transformative. Let’s explore the exciting opportunities that tokenisation, blockchain, and cryptocurrency can unlock for UK businesses.
2.1 Revolutionising Fundraising and Investment: Accessing New Capital Streams
Traditional fundraising methods can be time-consuming, expensive, and often limited to specific investor pools. Tokenisation allows businesses to fractionalise assets – from equity and debt to real estate and intellectual property – into digital tokens that can be easily traded and accessed by a wider range of investors, both domestically and internationally. This democratises investment, opens up new avenues for capital raising, and can provide greater liquidity for existing shareholders. Imagine a small UK startup being able to access global investors through a compliant token offering – the possibilities are immense!
2.2 Enhancing Customer Engagement and Loyalty: Building Deeper Connections
Traditional loyalty programmes often feel clunky and offer limited value to customers. Tokenisation allows businesses to create bespoke digital tokens as rewards, offering customers tangible benefits that can be traded, used for exclusive perks, or even integrated into a wider ecosystem. This fosters stronger customer loyalty, encourages repeat business, and provides valuable data on customer behaviour. Think about earning tokens for every purchase at your favourite local coffee shop, which you can then use for discounts, exclusive events, or even trade with other customers – that’s true engagement!
2.3 Streamlining Supply Chains and Enhancing Transparency: Building Trust and Efficiency
Complex and opaque supply chains are often plagued by inefficiencies, delays, and a lack of visibility.Blockchain technology provides an immutable and transparent ledger that can track goods and information as they move through the supply chain. This enhances traceability, reduces fraud, improves efficiency, and allows businesses to demonstrate the ethical and sustainable sourcing of their products to increasingly conscious consumers. Imagine a UK food producer using blockchain to allow customers to trace their organic vegetables from farm to table – that’s powerful transparency!
2.4 Facilitating Faster and Cheaper International Transactions: Expanding Global Reach
Traditional cross-border payments can be slow, expensive, and subject to fluctuating exchange rates.Cryptocurrencies offer a faster and often cheaper alternative for international transactions, particularly for businesses dealing with global suppliers or customers.While volatility remains a concern, stablecoins – cryptocurrencies pegged to the value of fiat currencies – can mitigate this risk. This opens up new international markets and streamlines global operations, making it easier for UK businesses to compete on a global stage.
2.5 Creating New Revenue Streams and Business Models: Innovating for the Future
Tokenisation and blockchain can enable entirely new business models. For example, fractional ownership of high-value assets like art or real estate becomes possible through tokenisation, opening up investment opportunities to a wider audience.Decentralised Autonomous Organisations (DAOs) powered by blockchain can create new forms of community-driven businesses. The possibilities for innovation are vast and largely untapped. Think about a UK brewery tokenising a share of its future beer production, allowing early supporters to benefit from its success – that’s a novel revenue stream!
2.6 Enhancing Data Security and Privacy: Building Customer Confidence
Blockchain’s inherent cryptographic security and decentralised nature can significantly enhance data security and privacy.While storing sensitive personal data directly on a public blockchain might not always be appropriate, hybrid solutions and private blockchains can offer a more secure and transparent way to manage certain types of data, giving customers greater control over their information and building trust.
2.7 Automating Processes and Reducing Costs: Driving Operational Efficiency
Smart contracts – self-executing contracts with the terms of the agreement directly written into code and stored on a blockchain – can automate various business processes, from invoice payments to supply chain management. This reduces the need for intermediaries, minimises the risk of human error, and drives significant cost savings. Imagine a UK logistics company using smart contracts to automatically release payments to suppliers upon verified delivery of goods – that’s streamlined efficiency!
2.8 Building Stronger Communities and Network Effects: Fostering Growth Through Collaboration
Tokenisation can be used to incentivise community participation and build strong network effects around a business or product. By rewarding users with tokens for their contributions, businesses can foster a loyal and engaged community that actively promotes their brand and contributes to their growth. Think about a UK online gaming platform rewarding players with tokens for creating content and engaging with the community – that’s building a powerful network!
2.9 Enhancing Intellectual Property Protection: Securing Your Innovations
Blockchain can provide an immutable and timestamped record of intellectual property, making it easier to prove ownership and protect against infringement. This is particularly valuable for businesses in creative industries or those developing innovative technologies. Registering intellectual property on a blockchain provides a secure and auditable trail of creation and ownership.
The growth opportunities presented by tokenisation, blockchain, and cryptocurrency are substantial and far-reaching. From revolutionising fundraising to enhancing customer engagement and streamlining operations, these technologies offer UK businesses a powerful toolkit to not just survive but thrive in the digital age.
Part 3: From Theory to Reality – 9 Examples of UK Businesses Adopting These Technologies for Protection and Growth
Now, let’s move beyond theory and explore concrete examples of how UK businesses can leverage tokenisation, blockchain, and cryptocurrency to protect themselves and accelerate their growth. These are not hypothetical scenarios; they represent tangible applications that forward-thinking businesses can implement today.
Example 1: Enhanced Supply Chain Traceability for a UK Food Producer (Blockchain)
A UK-based organic food producer can use a private blockchain to track its products from farm to consumer. Each stage of the supply chain – from planting and harvesting to processing and distribution – is recorded on the immutable ledger. Consumers can scan a QR code on the product packaging to access detailed information about its origin, ingredients, and journey, enhancing transparency and building trust. This also helps the producer quickly identify and address any issues in the supply chain, protecting their brand reputation.
Example 2: Tokenised Loyalty Programme for a UK Retailer (Tokenisation & Blockchain)
A UK fashion retailer can replace its traditional loyalty points system with its own digital token issued on a blockchain. Customers earn tokens for purchases, referrals, and engagement.These tokens can be redeemed for discounts, exclusive items, early access to sales, or even traded with other customers within the retailer’s ecosystem. This creates a more engaging and rewarding loyalty program, driving customer retention and providing valuable data on customer behaviour. The blockchain ensures transparency and prevents fraud.
Example 3: Cryptocurrency Payments for a UK E-commerce Business (Cryptocurrency)
A UK e-commerce business selling globally can integrate cryptocurrency payments alongside traditional options. This allows them to accept payments from customers worldwide with lower transaction fees and faster processing times, particularly for cross-border transactions. By accepting stablecoins, they can mitigate the risk of price volatility. This expands their potential customer base and streamlines international sales.
Example 4: Fractional Ownership of UK Property via Tokenisation (Tokenisation & Blockchain)
A UK real estate developer can tokenise shares in a new property development. Instead of requiring large upfront investments, individuals can purchase fractions of the property in the form of digital tokens.These tokens can represent ownership rights and potentially entitle holders to a share of rental income or capital appreciation.The blockchain provides a transparent and secure record of ownership, democratising access to the property market and providing the developer with a wider pool of potential investors.
Example 5: Securing Intellectual Property for a UK Design Agency (Blockchain)
A UK design agency can use a blockchain-based platform to register and timestamp their creative work, such as logos, designs, and marketing materials. This creates an immutable record of ownership and the date of creation, providing strong evidence in case of copyright infringement. This protects their intellectual property and strengthens their legal standing.
Example 6: Decentralised Autonomous Organisation (DAO) for a UK Community Project (Blockchain & Tokenisation)
A community-led renewable energy project in the UK can establish a DAO to govern its operations. Members can purchase governance tokens that give them voting rights on key decisions, such as project funding and future developments.Smart contracts on the blockchain automate the execution of these decisions, ensuring transparency and accountability. This fosters community ownership and engagement.
Example 7: Streamlining Cross-Border Payments for a UK Importer/Exporter (Cryptocurrency & Stablecoins)
A UK business that imports goods from Europe can use stablecoins pegged to the Euro for payments. This offers faster transaction times and potentially lower fees compared to traditional bank transfers, while mitigating the risk of exchange rate fluctuations. This streamlines their international procurement process and reduces costs.
Example 8: Tokenised Carbon Credits for a UK Sustainability Initiative (Tokenisation & Blockchain)
A UK environmental organisation can issue tokenised carbon credits representing verified carbon emission reductions. These tokens can be purchased by businesses looking to offset their carbon footprint, providing a transparent and auditable mechanism for carbon offsetting.The blockchain ensures the integrity and traceability of these credits.
Example 9: Enhanced Data Security for a UK Healthcare Provider (Private Blockchain)
A UK healthcare provider can use a private blockchain to securely manage patient records. While sensitive personal data wouldn’t be stored directly on the public blockchain, cryptographic hashes of the data and access permissions can be recorded, providing an auditable and tamper-proof log of who accessed what information and when. This enhances data security and patient privacy, complying with stringent regulations like GDPR.
These examples illustrate the diverse and practical ways in which UK businesses across various sectors can leverage tokenisation, blockchain, and cryptocurrency to enhance security, improve efficiency, unlock new revenue streams, and ultimately achieve faster and more sustainable growth. The key is to identify the specific challenges and opportunities within your business and explore how these technologies can provide tailored solutions.
Conclusion: Embracing the Future, Today!
The message is clear: tokenisation, blockchain, and cryptocurrency are not just futuristic concepts; they are powerful tools that can provide UK businesses with a critical edge in today’s rapidly evolving landscape. The risks of ignoring these technologies are significant, ranging from increased vulnerability to cyber threats and missed opportunities for growth. Conversely, the potential rewards are immense, offering enhanced security, streamlined operations, new revenue streams, and stronger customer engagement.
The nine examples we’ve explored demonstrate the tangible ways in which UK businesses can adopt these technologies across various sectors. From enhancing supply chain transparency to revolutionising fundraising and securing intellectual property, the applications are diverse and impactful.
The time for hesitation is over. The future of business is digital, decentralised, and tokenised. By embracing these transformative technologies, UK businesses can not only protect themselves from the storms ahead but also harness the winds of change to navigate towards a future of accelerated growth and sustainable success. Don’t get left behind – start exploring the potential of tokenisation, blockchain, and cryptocurrency for your business today!
Best sustainable business development practices for uk companies facing economic uncertainty
42%. That’s the percentage of UK businesses that cite ‘uncertainty’ as a major barrier to growth. Uncertainty. It’s a word that echoes through boardrooms and small offices alike. But uncertainty shouldn’t paralyse you. It should galvanise you. I know it’s daunting. I know the feeling of being overwhelmed. But I also know that inaction is the biggest risk of all. We are in a time of rapid change. Businesses that cling to old models are doomed. It is a fact. The market is relentless. It rewards the agile. It punishes the complacent. Business development is no longer a luxury; it’s a survival mechanism. You want to grow? You want to thrive? Then listen up. This isn’t about buzzwords or fleeting trends. This is about real, actionable strategies that can transform your business. We need to cut through the noise. We need to focus on what matters. We need to innovate. We need to do it now. So, let’s dive in. Let’s talk about how you can future-proof your business. Let’s talk about how you can win.
The future belongs to those who adapt
The belongs to those who innovate. It belongs to those who act. Don’t let uncertainty paralyse you. Let it fuel your ambition. Let it drive you to create a business that is not only successful but also sustainable. You have the power to shape your future. You have the power to win. So, what are you waiting for? Take action. Today. Your business depends on it.
Join BusinessRiskTV 360 Business Club with one-off lifetime membership fee
Read more risk management articles and view videos:
How can uk small businesses implement ai driven customer personalisation strategies for growth
Best sustainable business development practices for uk companies facing economic uncertainty
What are the most effective digital transformation strategies for traditional uk businesses to increase market share
How to build strategic partnerships and leverage fintech solutions for financial growth in uk startups
Risk management and talent acquisition strategies for uk businesses to ensure long term resilience and innovation
Time’s Running Out: UK Businesses Face Extinction
In today’s relentless market, stagnation is suicide. This video exposes the harsh reality: UK businesses are failing to innovate and adapt. Discover how to avoid becoming a casualty of complacency.
Economic manipulation and potential consequences of geopolitical tensions
The air crackles. It’s not just geopolitical tension. It’s the subtle, insidious hum of economic machinery gearing up. We’ve seen this before, haven’t we? The post-2008 scramble, the pandemic’s deluge of freshly minted currency. Now, a new spectre looms – Russia. And with it, a narrative that could justify trillions in new debt, a narrative that threatens to further erode the very foundations of our financial stability. We’re talking about inflation, busting the budgets of families, and the silent theft of wealth.
My time here is short, what can I do!?
Let’s cut to the chase. Environmental taxes, have hit a ceiling. Public tolerance is waning. After the financial crisis and the pandemic, the well of excuses for reckless borrowing is dry. So, what’s the next act? A resurgent Russia, a convenient bogeyman. To fuel the military industrial complex, and to pump trillions into stagnant economies. New British Defence Bonds, EU Defence Bonds, they’re being whispered about. I’m telling you, it’s not a coincidence. It’s a calculated move.
The Inflationary Tsunami: Money Printing’s Deadly Toll
The link between excessive money printing and inflation isn’t a theory. It’s a brutal reality. Central banks, in their zeal to stimulate economies, have flooded markets with liquidity. This deluge of new currency dilutes the value of existing money. A simple supply and demand equation. More money chasing the same amount of goods and services? Prices surge. I’ve seen it, you’ve seen it. Your buying power shrinks. Your savings erode. It’s a silent tax, a hidden levy on everyone.
The proposed Defence Bonds? They’re just another twist in this inflationary spiral. Governments will borrow massive sums, further increasing the money supply. This, inevitably, will exacerbate inflationary pressures. The cycle deepens: more debt, less value, higher prices. The average citizen, the small business owner, they’re the ones left to pick up the pieces.
Nine Pillars of the Argument: Why This Rings True
The Exhaustion of Other Narratives:Environmental taxes have reached their limits. Pandemic spending is unsustainable. A new, more potent justification is needed.
Geopolitical Instability as a Convenient Tool: Russia’s actions, however reprehensible, provide a ready-made excuse for increased military spending and economic intervention.
The Military-Industrial Complex’s Appetite: Defence contractors and related industries stand to gain immensely from increased military budgets, creating a powerful lobby for further spending.
The Desire to Stimulate Stagnant Economies: Governments are desperate to kickstart growth, and military spending is seen as a way to inject capital into key sectors.
The Appeal of Sovereign Debt: Defence bonds offer a seemingly safe way for governments to borrow vast sums, with the promise of future returns.
The Erosion of Public Trust: The constant cycle of crises and bailouts has weakened public trust in economic institutions, making it easier to push through controversial policies.
The Normalisation of Extraordinary Measures: The pandemic normalised unprecedented levels of government intervention, paving the way for further economic manipulation.
The Power of Fear: Fear is a potent motivator. The perceived threat from Russia can be used to justify policies that would otherwise be unacceptable.
The Delayed Impact of Inflation: The full effects of excessive money printing are often delayed, allowing governments to push through policies with minimal immediate backlash.
The Theatre of Threat: Manufacturing Consent
How do you convince a skeptical public to support massive military spending and increased debt? You create a sense of urgency, a palpable fear. You stage a theatre of threat. False red flags, carefully crafted narratives, and a compliant media.
Cyberattacks and Disinformation: Fabricated cyberattacks on critical infrastructure can create a sense of vulnerability, justifying increased security spending. Disinformation campaigns can sow fear and distrust, painting Russia as an imminent threat.
Staged Military Exercises: Highly publicised military exercises near borders can create a sense of tension and imminent conflict, driving public support for increased defence spending.
Intelligence Leaks: Carefully timed leaks of “intelligence” about Russian aggression can reinforce the narrative of an imminent threat, justifying drastic measures.
Media Amplification: A compliant media can amplify these narratives, creating a sense of widespread fear and urgency.
Political Rhetoric: Politicians can use inflammatory rhetoric to paint Russia as an existential threat, rallying public support for increased military spending.
Economic Sanctions and Countermeasures: Escalating economic sanctions and retaliatory measures can create a sense of economic warfare, further fuelling the narrative of conflict.
Protecting Your Assets: Navigating the Storm
In this environment of economic uncertainty and potential instability, businesses and consumers must take proactive steps to protect their assets.
Diversify Investments: Don’t put all your eggs in one basket. Diversify your investments across different asset classes, including real estate, commodities, and foreign currencies.
Hedge Against Inflation: Invest in assets that tend to hold their value during inflationary periods, such as gold, silver, cryptocurrency and real estate.
Manage Debt Wisely:Avoid taking on excessive debt, especially variable-rate debt that could become more expensive as interest rates rise.
Build Emergency Funds: Maintain a substantial emergency fund to cover unexpected expenses and economic downturns.
Secure Supply Chains: Businesses should diversify their supply chains to reduce reliance on vulnerable regions and ensure continuity of operations.
Invest in Cybersecurity: Protect your data and systems from cyberattacks, which are likely to increase in frequency and sophistication during periods of geopolitical tension.
The Power of War: A Transfer of Wealth and Control
Wars, despite their devastating human cost, are often a catalyst for significant shifts in power and wealth.Governments, during times of conflict, seize extraordinary powers, often at the expense of individual liberties.
Increased Government Control: Governments expand their control over the economy, industry, and media, often under the guise of national security.
Suspension of Civil Liberties: Civil liberties, such as freedom of speech and assembly, may be curtailed in the name of national security.
Nationalisation of Industries: Key industries may be nationalised to ensure the production of essential goods and services.
Rationing and Price Controls:Governments may impose rationing and price controls to manage scarce resources.
Increased Surveillance: Surveillance of citizens may increase under the guise of counterterrorism and national security.
The Winners and Losers: Following the Money
Wars create winners and losers. The military-industrial complex, defence contractors, and related industries often see their profits soar. Governments, while burdened with debt, gain increased control over their economies and societies.
Defence Contractors: Companies that produce weapons, military equipment, and related services see a surge in demand and profits.
Financial Institutions: Banks and financial institutions that underwrite government debt and manage defence contracts also benefit.
Governments: Governments gain increased control over their economies and societies, often at the expense of individual liberties.
The Average Citizen: The average citizen, burdened with increased taxes, inflation, and potential loss of civil liberties, often bears the brunt of the cost.
In Conclusion:
The spectre of Russian aggression is being weaponised to justify massive economic interventions, further fuelling inflation and eroding the value of hard-earned wealth. This is not a conspiracy theory; it’s a pattern of behaviour, a playbook that has been used throughout history. Businesses and consumers must be vigilant, proactive, and prepared to navigate the turbulent economic waters ahead. Diversification, hedging, and prudent financial management are essential for survival. And always, follow the money.
Get help to protect and grow your business faster with BusinessRiskTV
Read more business risk management articles and view videos :
Economic impact of new British defence bonds on UK inflation rates: the economic consequences of the proposed bonds.
How manufactured Russian threat justifies excessive government borrowing: focusing on the controversial aspect of using geopolitical tension as an economic tool.
Protecting business assets from inflation caused by military spending increases: practical, actionable advice targeting businesses seeking to safeguard their assets.
Analysis of government power expansion during perceived wartime economic conditions: for users interested in the broader implications of increased government control and the erosion of liberties.
Financial strategies to hedge against long term inflation from sovereign debt defence bonds: for those users seeking practical advice on how to protect their wealth from the potential impact of the new bonds.
#UKFutureTech : UK market with future-oriented tech today
Imagine: a world where the constraints of geography, language, and traditional financial structures dissolve. Not a utopian fantasy, but a tangible horizon, constructed from the converging forces of multilingual AI, quantum computing, blockchain, and tokenisation. The antiquated systems of education, the ones that often feel like holding pens for young minds, are no longer the sole gatekeepers to prosperity. I’m talking about a paradigm shift. One where the individual, armed with the right knowledge and tools, can architect their own destiny.
“The future is already here – it’s just not evenly distributed,” William Gibson famously observed. And he was right. Because we see the seeds of this future, a future where traditional barriers crumble, springing up all around us. But how do we harness it? How do we move from passive observer to active architect? This is not a theoretical exercise. This is about building a tangible, actionable framework for wealth, health, and happiness in a world undergoing radical transformation. Busting us out of the limitations of the past, we must first understand the tools at our disposal.
Let’s cut through the noise. Forget the platitudes. Forget the motivational fluff. We’re here for concrete strategies, actionable insights, and a clear roadmap. We’re here to build a lifestyle where the old rules don’t apply. Understanding how to leverage these tools is not just about financial gain. It’s about unlocking a new level of personal freedom. It’s about building a life that is truly aligned with your values. It’s about, quite simply, living better. And we can do it.
Navigating the Future of Wealth, Health, and Happiness
The Linguistic Labyrinth – Breaking Down Language Barriers with AI
Language, historically, has been a barrier, a moat surrounding opportunities. But the rise of sophisticated multilingual AI is changing the game. We’re not talking about clunky translation software. I’m talking about AI that understands nuance, context, and cultural subtleties. Imagine instantly accessing global markets, forming international partnerships, and engaging with diverse communities, all without linguistic limitations. This is the power of multilingual AI.
Actionable Insight 1: Leverage Real-Time Translation and Localisation Tools:
Investigate and integrate AI-powered translation tools like DeepL, Google Translate API, and Microsoft Translator API into your communication workflows.
Explore platforms that offer real-time translation for video conferencing and webinars, facilitating seamless international collaboration.
Utilise localisation services that adapt content for specific cultural contexts, ensuring your message resonates with diverse audiences.
Identify key international markets and create content tailored to their linguistic and cultural preferences.
Use AI-powered tools to analyse language trends and optimise your content for search engines in multiple languages.
Consider creating multilingual versions of your website, blog, and social media content to expand your reach.
Actionable Insight 3: Learn Key Phrases in High-Value Languages:
Even with AI, understanding basic phrases in key languages like Mandarin, Spanish, or Arabic can significantly enhance communication and build rapport.
Use language learning apps like Language Transfer, Duolingo, Babbel, or Memrise to acquire practical language skills.
Focus on phrases related to your industry or area of interest, making your communication more relevant and effective.
The ability to communicate effectively across languages opens up a world of opportunities. It’s about more than just translating words; it’s about bridging cultural gaps and building meaningful connections. And this is vital. Busting us out of the isolation that limited language creates.
The Quantum Leap – Unlocking Computational Power for Innovation
Quantum computing, once a theoretical concept, is now a tangible reality. It promises to revolutionise industries from finance to healthcare, offering unprecedented computational power. This isn’t just about faster computers. It’s about unlocking solutions to problems that were previously considered unsolvable.
Actionable Insight 4: Stay Informed About Quantum Computing Developments:
Follow leading research institutions and companies involved in quantum computing, such as IBM Quantum, Google Quantum AI, and Microsoft Quantum.
Subscribe to industry publications and attend conferences to stay up-to-date on the latest advancements.
Explore online courses and resources to gain a foundational understanding of quantum computing principles.
Actionable Insight 5: Identify Potential Applications in Your Field:
Consider how quantum computing could be used to optimise processes, solve complex problems, or develop new products and services in your industry.
Explore potential applications in areas like financial modelling, drug discovery, materials science, and artificial intelligence.
Actionable Insight 6: Build a Network of Quantum Computing Experts:
Connect with researchers, developers, and entrepreneurs working in the field of quantum computing.
Attend industry events and join online communities to expand your network and learn from others.
Consider collaborating with quantum computing startups or research institutions on joint projects.
The potential of quantum computing is immense. And we are just beginning to scratch the surface. This technology will reshape the world as we know it. We must be prepared. Busting us out of the computational limitations of the classic computer, the quantum computer opens new doors.
The Blockchain Revolution – Decentralising Finance and Trust
Blockchain technology is transforming industries by decentralising data and transactions. It offers transparency, security, and efficiency, disrupting traditional financial systems and creating new opportunities for innovation. This is about more than just cryptocurrencies. It’s about building trust in a decentralised world.
Actionable Insight 7: Understand the Fundamentals of Blockchain Technology:
Learn about the underlying principles of blockchain, including cryptography, consensus mechanisms, and distributed ledgers.
Explore different blockchain platforms, such as Ethereum, Binance Smart Chain, and Solana, and their respective strengths and weaknesses.
Familiarise yourself with key concepts like smart contracts, decentralised applications (dApps), and decentralised finance (DeFi).
Actionable Insight 8: Explore Opportunities in Decentralised Finance (DeFi):
Investigate DeFi platforms that offer lending, borrowing, and yield farming opportunities.
Learn about stablecoins and their role in mitigating volatility in the cryptocurrency market.
Consider participating in decentralised autonomous organisations (DAOs) to contribute to the governance of DeFi projects.
Actionable Insight 9: Utilise Blockchain for Supply Chain Management and Data Security:
Explore how blockchain can be used to track products and ensure transparency in supply chains.
Implement blockchain-based solutions for data security and identity management, protecting sensitive information from unauthorised access.
Consider using blockchain for digital asset management and intellectual property protection.
The blockchain is more than a technology; it’s a paradigm shift. It’s about empowering individuals and creating a more equitable and transparent world. And this is critical. Busting us out of centralised financial systems, the blockchain offers a new level of freedom.
The Tokenisation of Everything – Creating New Asset Classes and Opportunities
Tokenisation is the process of converting real-world assets into digital tokens on a blockchain. This creates new asset classes, increases liquidity, and democratises access to investment opportunities. This is about more than just digital collectibles. It’s about redefining ownership and value.
Actionable Insight 10: Explore the Potential of Non-Fungible Tokens (NFTs):
Learn about the different types of NFTs and their applications in art, music, gaming, and other industries.
Consider creating or investing in NFTs that align with your interests and values.
Explore platforms like OpenSea, Rarible, and SuperRare for buying and selling NFTs.
Actionable Insight 11: Investigate Tokenised Real Estate and Other Asset Classes:
Explore platforms that offer tokenised real estate investments, allowing you to diversify your portfolio with fractional ownership.
Investigate opportunities in tokenised commodities, securities, and other asset classes.
Understand the regulatory landscape surrounding tokenised assets and ensure compliance with relevant laws.
Actionable Insight 12: Develop Tokenisation Strategies for Your Business:
Consider how tokenisation can be used to create new revenue streams, improve customer engagement, or enhance brand loyalty.
Explore the potential of creating loyalty tokens, community tokens, or other digital assets that represent value for your business.
Consult with blockchain experts and legal professionals to develop a comprehensive tokenisation strategy.
Tokenisation is about democratising access to assets and creating new opportunities for wealth creation. It’s about unlocking the value of everything. And we can do it. Busting us out of traditional investment models, tokenisation opens up new possibilities.
Integrating the Technologies – Building a Holistic Ecosystem
The true power lies in integrating these technologies into a holistic ecosystem. Multilingual AI facilitates global communication, quantum computing unlocks computational power, blockchain decentralises finance and tokenisation creates new asset classes. Imagine a world where you can seamlessly communicate with anyone in the world, access unprecedented computational power to solve complex problems, participate in decentralised financial systems, and invest in tokenised assets, all within a single, interconnected ecosystem. This is the future we are building.
Actionable Insight 13: Develop a Personal Ecosystem Strategy:
Identify your key goals and objectives in terms of wealth, health, and happiness.
Determine which technologies are most relevant to your goals and how they can be integrated.
Create a roadmap for implementing your ecosystem strategy, including timelines and milestones.
Actionable Insight 14: Build a Network of Interdisciplinary Experts:
Connect with experts in AI, quantum computing, blockchain, and tokenisation.
Attend industry events and join online communities to expand your network and learn from others.
Consider forming partnerships with individuals and organisations that complement your skills and expertise.
Actionable Insight 15: Embrace Continuous Learning and Adaptation:
The technologies we are discussing are constantly evolving, so it is essential to stay informed and adapt to new developments.
Develop a habit of continuous learning by reading industry publications, attending webinars, and experimenting with new tools and platforms.
Be open to change and willing to pivot your strategy as needed.
By integrating these technologies, we can create a powerful ecosystem that empowers individuals to achieve their full potential. This is about more than just individual success. It’s about building a more equitable and prosperous world for all. Busting us out of siloed thinking, we need to create a synergistic system.
Health and Longevity – Leveraging Technology for Well-being
The pursuit of wealth should not come at the expense of health. Technology can play a vital role in enhancing our well-being and extending our lifespan. We can leverage AI, quantum computing, and blockchain to personalise healthcare, optimise nutrition, and track our fitness.
Actionable Insight 16: Utilise AI-Powered Health and Fitness Trackers:
Explore wearable devices and apps that use AI to monitor your vital signs, track your activity levels, and provide personalised insights into your health.
Use AI-powered nutrition apps to optimise your diet and ensure you are getting the nutrients your body needs.
Consider using AI-powered mental health apps to manage stress, improve sleep, and enhance your overall well-being.
Actionable Insight 17: Explore Personalised Medicine and Genomics:
Learn about the potential of genomics and personalised medicine to tailor healthcare treatments to your individual genetic makeup.
Investigate companies and research institutions that are developing innovative solutions in this field.
Consider participating in genetic testing to gain insights into your health risks and predispositions.
Actionable Insight 18: Leverage Blockchain for Secure Health Data Management:
Explore blockchain-based solutions for storing and sharing health data securely and efficiently.
Consider using blockchain to track the provenance of pharmaceuticals and ensure the authenticity of medical supplies.
Investigate the potential of blockchain to facilitate decentralised clinical trials and accelerate medical research.
Health is the foundation of a fulfilling life. We must prioritise our well-being and leverage technology to optimise our health and longevity. Busting us out of outdated healthcare models, we can use technology to empower our own health.
The Future of Education – Beyond Traditional Models
The traditional education system is often ill-equipped to prepare individuals for the rapidly changing world. We need to embrace new models of learning that are personalised, flexible, and accessible. We can leverage AI, blockchain, and online platforms to create a more effective and engaging learning experience.
Actionable Insight 19: Embrace Online and Blended Learning:
Consider pursuing micro-credentials and certifications that demonstrate your skills and expertise.
Utilise online communities and forums to connect with other learners and experts in your field.
Actionable Insight 20: Leverage AI for Personalised Learning:
Explore AI-powered learning platforms that adapt to your individual learning style and pace.
Use AI-powered tutoring tools to get personalised support and feedback.
Consider using AI to create personalised learning paths and recommendations.
Actionable Insight 21: Utilise Blockchain for Educational Credentials and Verification:
Explore blockchain-based solutions for issuing and verifying educational credentials.
Consider using blockchain to create a decentralised learning record that is portable and secure.
Investigate the potential of blockchain to facilitate peer-to-peer learning and knowledge sharing.
Education should be a lifelong pursuit, not a one-time event. We must embrace new models of learning that empower individuals to acquire the skills and knowledge they need to thrive in the future. Busting us out of the old school system, we need to build a new one.
Building a Global Community – Connecting and Collaborating
The future is global. We need to build a community of like-minded individuals who are passionate about leveraging technology to create a better world. We can use online platforms, social media, and virtual events to connect and collaborate with people from all over the globe.
Actionable Insight 22: Join Online Communities and Forums:
Participate in online communities and forums related to AI, quantum computing, blockchain, and tokenisation.
Network with other professionals and learn about the latest trends and developments.
Consider speaking at events to share your expertise and build your reputation.
Actionable Insight 24: Collaborate on Open-Source Projects:
Contribute to open-source projects related to AI, blockchain, and other technologies.
Collaborate with other developers and researchers to create innovative solutions.
Build your portfolio and demonstrate your skills by contributing to meaningful projects.
We are stronger together. By building a global community, we can accelerate innovation and create a more equitable and prosperous world. Busting us out of our isolated bubbles, we must build bridges.
Ethical Considerations – Building a Sustainable Future
As we embrace these powerful technologies, it is essential to consider the ethical implications. We must ensure that these technologies are used for good and that they benefit all of humanity. We need to build a sustainable future that is both prosperous and equitable.
Actionable Insight 25: Promote Ethical AI and Blockchain Development:
Support organisations and initiatives that are working to develop ethical guidelines and standards for AI and blockchain.
Consider the potential biases and unintended consequences of these technologies.
Advocate for responsible innovation and transparency.
Actionable Insight 26: Invest in Sustainable and Impactful Projects:
Support projects and initiatives that are addressing global challenges such as climate change, poverty, and inequality.
Consider investing in companies and organisations that are committed to sustainability and social responsibility.
Use your skills and expertise to contribute to projects that are making a positive impact.
Actionable Insight 27: Educate and Empower Others:
Share your knowledge and expertise with others to help them understand the potential and implications of these technologies.
Mentor and support aspiring entrepreneurs and innovators.
Advocate for policies that promote innovation and equitable access to technology.
We have a responsibility to use these technologies wisely. By prioritising ethical considerations and building a sustainable future, we can create a world that is both prosperous and just. Busting us out of short sightedness, we must consider the long term.
Conclusion: The Algorithm of Abundance – A Call to Action
The future is not something that happens to us. It is something we create. We have the tools and the knowledge to build a world of abundance, health, and happiness. It is up to us to take action and make it happen. We encourage you to embrace these technologies, build your own ecosystem of abundance, and join the global community of innovators who are shaping the future.
The algorithm of abundance is not a theoretical concept. It is a tangible reality that we can create together. Let’s get started.
Get help to protect and grow your business faster with BusinessRiskTV
How to build a resilient business growth strategy despite political and economic uncertainty
“In the turbulent theatre of modern business, where the next political decree can feel like a plot twist from a poorly written drama, one statistic stands stark: 8 out of 10 businesses fail within the first 18 months. Not because of a lack of passion, not because of poor ideas, but often, because of unmanaged risks. You, like me and countless other resilient business leaders, refuse to let external chaos dictate your destiny. We’re driven by an insatiable hunger for growth, a refusal to be sidelined by political whims. If your appetite for business expansion is undiminished, if you’re searching for a community of like-minded individuals to navigate the ever-shifting sands of commerce, then you’ve found your tribe. Welcome to the BusinessRiskTV Business Risk Management Club. This isn’t just another networking group; it’s a strategic alliance, a fortress of knowledge, and a launchpad for accelerated, resilient growth.”
Let’s face it. We’ve all seen the news. Regulations change overnight. Markets fluctuate wildly. And don’t even get me started on the global economic climate. You’re a business leader. You’re not looking for excuses, you’re looking for solutions. That’s why we built this club.
What is the BusinessRiskTV Business Risk Management Club?
It’s a curated community designed to empower you with the tools, insights, and connections needed to thrive in any environment. We understand that risk isn’t just about avoiding disaster; it’s about identifying opportunities hidden within uncertainty. It’s about turning potential threats into competitive advantages.
Strategic Insights: You’ll gain access to exclusive webinars, workshops, and reports from leading risk management experts. We’re not talking about generic advice. We’re talking about actionable strategies tailored to the real-world challenges you face.
Peer-to-Peer Learning: Connect with a network of seasoned business leaders who understand the pressures you face. Share best practices, collaborate on projects, and find mentors who can guide you through your growth journey.
Risk Mitigation Tools: We provide members with access to proprietary risk assessment tools and frameworks, enabling you to identify and mitigate potential threats before they impact your bottom line.
Growth Acceleration: Our focus is on empowering you to capitalise on emerging opportunities and accelerate your business growth, regardless of the external environment.
“You can’t control the weather, but you can build a stronger ship.” This is the core of our philosophy. We equip you to navigate any storm.
Risk Management Business Intelligence You Can Work From:
Monthly Risk Intelligence Briefings:
These briefings provide in-depth analysis of emerging risks and opportunities, covering geopolitical, economic, and technological trends.
Each briefing includes actionable recommendations and case studies to help you apply the insights to your own business.
We will break down complex information into digestible, practical takeaways.
For example, a recent briefing explored the impact of AI on cybersecurity, providing strategies for protecting your business from evolving threats.
Interactive Risk Assessment Workshops:
These workshops guide you through a structured process for identifying and assessing risks within your organisation.
You’ll learn how to develop risk mitigation plans and monitor their effectiveness.
We use real-world scenarios and interactive exercises to enhance your understanding.
“I have seen many businesses fail due to lack of planning, these workshops will provide you with the tools to plan.”
We will provide templates for risk registers and risk impact matrices.
Industry-Specific Risk Forums:
Connect with peers in your industry to discuss specific risk challenges and share best practices.
These forums provide a platform for collaborative problem-solving and knowledge sharing.
We cover a wide range of industries, including finance, technology, healthcare, and manufacturing.
We will focus on the most pressing risk that affect each industry.
Exclusive Access to Risk Management Tools:
Our members receive access to proprietary risk assessment software and templates, enabling them to streamline their risk management processes.
These tools include risk registers, risk impact matrices, and scenario planning templates.
We provide training and support to help you maximise the value of these tools.
We will provide the tools that allow you to visualise your risk.
Personalised Risk Consulting:
Members can schedule one-on-one consultations with our risk management experts to address specific challenges and develop tailored solutions.
These consultations provide personalised guidance and support to help you achieve your business goals.
We focus on delivering practical, actionable advice that you can implement immediately.
We will pair you with a risk management expert that specialises in your industry.
“Navigating Political Uncertainty” Forum:
This ongoing series focuses on providing strategies to mitigate the impact of political changes on your business.
We analyse policy shifts, regulatory changes, and geopolitical events, providing actionable insights.
Experts will provide deep insights, and we will translate that into practical advice.
“Political uncertainty is a constant, we must adapt.”
“Cybersecurity Resilience” Training:
With the increasing prevalence of cyber threats, this training programme equips you with the knowledge and skills to protect your business.
We cover topics such as data protection, threat detection, and incident response.
Hands-on exercises and real-world case studies enhance your understanding.
We will show you how to build a robust cybersecurity framework.
“Supply Chain Risk Management” Workshops:
In today’s interconnected world, supply chain disruptions can have a significant impact on your business.
These workshops provide strategies for building resilient supply chains and mitigating potential disruptions.
We cover topics such as supplier risk assessment, inventory management, and logistics optimisation.
We will provide you with a framework to analyse your supply chain.
“Financial Risk Mitigation” Seminars:
These seminars focus on providing strategies for managing financial risks, including market volatility, credit risk, and liquidity risk.
Experts will provide insights into financial modelling, risk analysis, and hedging strategies.
We will help you build a robust financial risk management framework.
“Innovation Risk Management” Programme:
Innovation is essential for growth, but it also involves risks.
This programme provides strategies for managing the risks associated with innovation, including product development, market entry, and technology adoption.
We will provide a framework for balancing innovation with risk mitigation.
Addressing You Directly:
You understand the challenges of running a business in today’s environment. You’ve seen the impact of unpredictable regulations and economic fluctuations. You’re looking for a community of like-minded leaders who share your drive and resilience. That’s exactly what you’ll find in the BusinessRiskTV Business Risk Management Club.
Viewers, you’re not alone in your pursuit of growth. You’re not alone in facing the challenges of risk management. We’re here to provide you with the tools, insights, and connections you need to succeed.
The Power of Business Risk Management Club Community:
The club is more than just a collection of resources; it’s a vibrant community of business leaders who are committed to helping each other succeed. We believe that by sharing knowledge and collaborating on solutions, we can overcome any obstacle.
A seasoned entrepreneur, said, “The greatest risk is not taking any risk at all.” But he also stressed the importance of calculated risks, informed decisions, and robust risk management strategies. That’s what we’re here to provide.
Why Join Business Risk Management Club Now?
The business landscape is changing rapidly. The risks are greater than ever. But so are the opportunities. By joining the BusinessRiskTV Business Risk Management Club, you’ll be positioned to capitalise on these opportunities and navigate the challenges with confidence.
Our Commitment to You:
We are committed to providing you with the highest quality resources and support. We are constantly updating our content and tools to ensure that you have access to the latest insights and best practices.
Join the BusinessRiskTV Business Risk Management Club Today:
Don’t let uncertainty hold you back. Join our community of resilient business leaders and accelerate your growth.
Explore our website today to learn more about the BusinessRiskTV Business Risk Management Club and to join our community.
We believe that every business has the potential to thrive, regardless of the challenges it faces. By joining our club, you’ll gain the tools, insights, and connections you need to unlock your full potential.
We look forward to welcoming you to our community.
Potential danger to personal and business savings. Discover how to protect yourself and your business savings.
The EU’s Defence Gamble – Your Savings on the Line?
“The EU’s defence spending gap is staggering. Estimates suggest a shortfall reaching hundreds of billions. This isn’t just about tanks and planes. It’s about your money. Yes, your savings. The European Union is eyeing private capital, specifically, the vast pools of private savings, to bridge this divide. It’s a bold move, and it’s fraught with potential risk. But what does it really mean to “mobilise” private savings? Does it include your bank account? The answer might shock you. This isn’t a theoretical exercise, it’s a strategic shift that could ripple through the financial landscape, impacting every consumer and business within the EU. Consider this: a single policy change could redirect billions, potentially affecting your financial security. You’re not just reading about policy; you’re reading about potential financial vulnerability. This isn’t fear-mongering; it’s a call to proactive awareness. We’ll explore the EU’s plan, dissect its potential dangers, and, most importantly, provide actionable strategies to protect your assets. Because, frankly, waiting is not an option. Let’s get into the details, and I will show you how to navigate this new financial reality.”
The EU’s Defence Funding Shift: Mobilising Private Savings and Its Implications
1. The EU’s Defence Funding Dilemma
The European Union faces a growing security challenge.Geopolitical tensions, particularly the ongoing conflict in Ukraine, have underscored the need for a stronger and more unified defence posture. However, achieving this requires substantial financial investment. Traditional sources of funding, like national budgets, are proving insufficient.This has led the EU to explore alternative financing mechanisms, including the mobilisation of private capital.
The Funding Gap: The precise size of the EU’s defence funding gap is a subject of debate, but it is undeniably significant. Estimates range from hundreds of billions to potentially trillions of euros over the next decade. This gap arises from years of underinvestment in defence, coupled with the rising costs of modern military equipment and technology.
Geopolitical Context:The war in Ukraine has dramatically altered the European security landscape. It has highlighted the vulnerability of EU member states and the need for greater military readiness. This heightened sense of urgency has accelerated the search for new funding solutions.
Strategic Autonomy: The EU’s pursuit of “strategic autonomy” – the ability to act independently in matters of security and defence – requires substantial investment. This ambition necessitates a robust defence industry and a reliable funding stream.
2. Mobilising Private Savings: What Does It Mean?
The concept of “mobilising private savings” encompasses a range of potential strategies. It is not a single, clearly defined policy. Rather, it is an umbrella term for various initiatives aimed at channeling private capital into defence-related investments.
Investment Funds and Bonds: One potential approach involves the creation of specialised investment funds or bonds that would invest in defence companies and projects. These instruments could be marketed to institutional investors, such as pension funds and insurance companies, as well as retail investors.
Tax Incentives: The EU could introduce tax incentives to encourage private investment in defence. This might include tax breaks for individuals or businesses that invest in defence-related funds or projects.
Public-Private Partnerships: The EU could foster public-private partnerships (PPPs) to finance defence projects. This would involve collaboration between government agencies and private companies, with the private sector contributing capital and expertise.
Directing Bank Savings: This is the most concerning aspect. The EU could potentially create mechanisms to direct a portion of private bank savings towards defence investments. This could involve regulatory changes that would allow or require banks to allocate a certain percentage of their assets to defence-related projects.
3. Does This Include Consumer and Business Bank Savings Accounts?
The critical question is whether “mobilising private savings” includes direct access to consumer and business bank savings accounts. While EU officials have not explicitly stated that this is their intention, the possibility cannot be ruled out.
Regulatory Changes: The EU has the power to introduce regulatory changes that could affect how banks manage their assets. This could potentially include regulations that would require banks to invest a portion of their deposits in defence-related instruments.
Financial Repression: Historically, governments have resorted to “financial repression” during times of crisis. This involves measures such as interest rate controls and capital controls, which can be used to direct private savings towards government priorities.
Indirect Mechanisms: Even without direct access to bank accounts, the EU could use indirect mechanisms to influence the flow of private savings. For example, it could introduce regulations that would make it more attractive for banks to invest in defence-related assets.
4. Why Could This Be Dangerous for Consumers and Businesses?
The mobilisation of private savings for defence funding poses several potential risks for consumers and businesses.
Loss of Liquidity: If a significant portion of private savings is tied up in long-term defence investments, consumers and businesses could face a loss of liquidity. This could make it difficult to access funds for everyday expenses or business operations.
Increased Risk: Defence investments can be risky, particularly in the current geopolitical climate. If these investments perform poorly, consumers and businesses could suffer financial losses.
Inflationary Pressures: Increased defence spending, financed by private savings, could lead to inflationary pressures. This could erode the purchasing power of consumers and increase the cost of doing business.
Erosion of Trust: If consumers and businesses feel that their savings are being used for purposes that they do not support, it could erode trust in the financial system.
Reduced Economic Growth: Tying up private capital in defence could reduce the availability of funds for other productive investments, such as infrastructure and innovation. This could hinder economic growth.
Potential for Misuse: Defence spending is often shrouded in secrecy, which creates the potential for misuse of funds. There is a risk that private savings could be used for projects that are not in the best interests of consumers and businesses.
5. What Could Consumers and Businesses Lose Potentially?
Consumers and businesses could potentially lose a variety of things, including:
Financial Security: The loss of liquidity and increased risk could jeopardise the financial security of consumers and businesses.
Purchasing Power:Inflationary pressures could erode the purchasing power of consumers and increase the cost of doing business.
Investment Opportunities: The redirection of private savings towards defence could reduce the availability of funds for other investment opportunities.
Confidence in the Financial System: Erosion of trust in the financial system could lead to a decline in investment and economic activity.
Control Over Their Assets: Consumers and businesses could lose control over how their savings are used.
6. Nine Actions Consumers and Businesses Should Take Now to Protect Their Savings:
Here are nine actionable steps consumers and businesses can take to mitigate the risks associated with the EU’s defence funding plans:
Diversify Your Assets: Don’t keep all your eggs in one basket. Diversify your investments across different asset classes, such as stocks, bonds, real estate, and commodities.
Increase Liquidity: Maintain a sufficient amount of liquid assets, such as cash or short-term investments, to cover unexpected expenses or business needs.
Monitor Your Bank Accounts: Keep a close eye on your bank accounts and be aware of any changes in regulations or policies that could affect your savings.
Explore Alternative Banking Options: Consider exploring alternative banking options, such as credit unions or online banks, that may offer greater flexibility and security.
Invest in Stable Currencies: If you are concerned about the stability of the euro, consider investing in stable currencies, such as the Swiss franc or the US dollar. Explore investing in cryptocurrencies.
Consider Physical Assets: Physical assets, such as gold or real estate, can provide a hedge against inflation and financial instability.
Seek Professional Financial Advice: Consult with a qualified financial adviser to develop a personalised financial plan that takes into account the potential risks associated with the EU’s defence funding plans.
Stay Informed: Keep up-to-date on the latest developments in EU defence policy and financial regulations.
Advocate for Transparency: Support initiatives that promote transparency and accountability in government spending and financial regulations.
7. Geographical Diversification: Where Can Savings Be Safe?
Geographical diversification can be a valuable strategy for mitigating risk. While no location is entirely immune to global financial instability, some regions may offer greater stability than others.
Switzerland:Switzerland has a long history of political and financial stability. Its strong currency, sound financial system, and neutral political stance make it an attractive destination for investors seeking safe haven assets.
Singapore:Singapore is a global financial centre with a well-regulated financial system and a stable political environment. Its strong economy and strategic location make it a compelling choice for geographical diversification.
Norway:Norway’s strong economy, abundant natural resources, and well-managed sovereign wealth fund make it a relatively safe haven for savings.
Canada:Canada’s stable political system, well-regulated financial sector, and abundant natural resources make it a secure location for assets.
United States: The US dollar remains the world’s reserve currency, and the US financial system is generally considered to be robust. However, it’s important to remember that the US is not without its own financial risks.
8. Who Is at Risk?
The potential risks associated with the EU’s defence funding plans affect a broad range of stakeholders, including:
Consumers: Individuals with bank savings accounts, investments, and pensions are all potentially at risk.
Businesses: Small and medium-sized enterprises (SMEs) and large corporations alike could be affected by reduced liquidity, increased costs, and financial instability.
Investors: Institutional investors, such as pension funds and insurance companies, as well as retail investors, could face losses on their investments.
Banks: Banks could be required to hold a larger proportion of their assets in potentially risky defence-related investments.
The Eurozone Economy: The overall stability of the eurozone economy could be jeopardised by reduced investment, inflationary pressures, and a loss of confidence.
Implementation of New Regulations: The EU could introduce new regulations or directives that would directly affect the flow of private savings towards defence. The timing of these changes would depend on the political will of member states and the EU institutions.
Escalation of Geopolitical Tensions: A further escalation of geopolitical tensions, particularly in Eastern Europe, could accelerate the need for increased defence spending and trigger the implementation of emergency measures.
Financial Crisis: A financial crisis, either within the EU or globally, could lead to a rapid redirection of private savings towards government priorities, including defence.
Slow, Gradual Changes: It is also possible that changes will be slow and gradual, with small regulatory changes leading to larger shifts over a longer period of time. It is this slow change that can make it difficult for businesses and consumers to notice the changes until it is too late.
10. The Importance of Vigilance and Proactive Action
The EU’s defence funding plans represent a significant shift in financial policy. It is crucial for consumers and businesses to remain vigilant and take proactive steps to protect their assets. This includes diversifying investments, increasing liquidity, staying informed, and advocating for transparency.
Active Participation: Citizens should actively engage in the democratic process and express their concerns to policymakers.
Financial Education:Financial literacy is essential for navigating the complexities of the modern financial system. Consumers and businesses should invest in financial education to make informed decisions.
Collective Action: Collective action, such as joining consumer advocacy groups or business associations, can amplify individual voices and influence policy decisions.
Scenario Planning: Businesses should engage in scenario planning to anticipate potential risks and develop contingency plans.
Regular Review: Financial plans should be reviewed and updated regularly to reflect changing economic and political conditions.
11. The Role of Technology
Technology can play a vital role in protecting savings and mitigating risks.
Financial Technology (FinTech):FinTech companies are developing innovative solutions that can help consumers and businesses manage their finances more effectively. This includes tools for budgeting, investing, and risk management.
Blockchain Technology:Blockchain technology can enhance transparency and security in financial transactions. It can also be used to create decentralised financial systems that are less vulnerable to government control.
Cybersecurity: Robust cybersecurity measures are essential for protecting digital assets from cyberattacks.
12. The Future of EU Defence Funding
The EU’s defence funding plans are likely to evolve over time. The precise form and impact of these plans will depend on a variety of factors, including geopolitical developments, economic conditions, and political decisions.
Long-Term Strategy: The EU needs to develop a long-term strategy for defence funding that is sustainable and transparent.
International Cooperation: International cooperation is essential for addressing global security challenges. The EU should work with its allies and partners to develop a coordinated approach to defence funding.
Ethical Considerations: The ethical implications of using private savings for defence funding should be carefully considered.
Transparency and Accountability: Transparency and accountability are crucial for ensuring that defence spending is used effectively and efficiently.
13. Conclusion: Navigating Uncertainties
The EU’s push to mobilise private savings for defence is a complex and potentially risky endeavour. While the need for increased defence spending is undeniable, the potential consequences for consumers and businesses cannot be ignored.
It is imperative that individuals and organisations take proactive steps to protect their financial security. This includes diversifying assets, increasing liquidity, staying informed, and advocating for transparency. The future of EU defence funding is uncertain, but by remaining vigilant and taking action, consumers and businesses can navigate the challenges and protect their financial well-being. The best defence against financial uncertainty is knowledge and proactive action.
Get help to protect and grow your business faster with BusinessRiskTV
How US debt refinancing in 2025 could impact global markets
Imagine standing on the edge of a financial precipice, where the stability of the global economy teeters on the decisions made today. The United States, the world’s largest economy, faces a monumental challenge: nearly $10 trillion of its government debt is set to mature in and around 2025, all carrying an average coupon rate of 2.5%. Refinancing this colossal sum at current interest rates exceeding 5% could lead to unprecedented interest payments, consuming a significant portion of the federal budget. This scenario not only threatens America’s fiscal health but also casts a long shadow over global economic stability.
In this intricate dance of economics and policy, some speculate whether a recession in 2025 and 2026 might be a strategic, albeit perilous, manoeuvre to push down interest rates and bond yields, making borrowing more affordable. The stakes are high, and the implications vast, affecting businesses, governments, and individuals worldwide.
The Critical Importance of U.S. Debt Management
The United States’ ability to manage its debt is not just a national concern; it’s a linchpin of global economic stability. U.S. Treasury securities are considered one of the safest investments, serving as a benchmark for global financial markets. They influence everything from mortgage rates to corporate borrowing costs worldwide.
However, with $9.2 trillion of U.S. debt maturing in and around 2025, accounting for 25.4% of the country’s total debt, the challenge is immense.The rapid accumulation of debt, fueled by historic levels of deficit spending, has led to interest payments ballooning to over $1 trillion per year. This scenario raises concerns about the government’s ability to meet its obligations without resorting to measures that could destabilise the economy.
The Danger to Businesses in America and Worldwide
The repercussions of this debt crisis extend far beyond government balance sheets. Businesses, both in the United States and globally, could face significant challenges:
1. Increased Borrowing Costs: As the U.S. government competes for capital to refinance its debt, interest rates could rise, leading to higher borrowing costs for businesses.
2. Reduced Consumer Spending: Higher interest rates often translate to increased costs for consumers, leading to reduced disposable income and lower demand for goods and services.
3. Currency Volatility: Concerns over U.S. fiscal stability could lead to fluctuations in the value of the dollar, affecting international trade and investment.
4. Global Economic Slowdown: Given the interconnectedness of today’s economies, a U.S. debt crisis could trigger a global economic slowdown, impacting businesses worldwide.
Nine Strategies for Business Leaders to Mitigate Risk
In light of these potential challenges, business leaders must proactively implement strategies to safeguard their organisations:
1. Diversify Funding Sources: Relying solely on traditional bank loans may become costly. Exploring alternative financing options, such as issuing bonds or equity financing, can provide more stable capital sources.
2. Strengthen Balance Sheets: Reducing debt levels and increasing cash reserves can provide a buffer against economic downturns and increased borrowing costs.
3. Hedge Against Currency Risk: For businesses operating internationally, employing hedging strategies can protect against currency fluctuations that may arise from economic instability.
4. Enhance Operational Efficiency: Streamlining operations to reduce costs can improve margins and provide greater flexibility in challenging economic environments.
5. Focus on Core Competencies: Concentrating resources on core business areas can enhance resilience and reduce exposure to volatile markets.
6. Monitor Economic Indicators: Staying informed about economic trends and government fiscal policies enables timely decision-making and strategic adjustments.
7. Engage in Scenario Planning: Developing contingency plans for various economic scenarios ensures preparedness for potential downturns or financial crises.
8. Strengthen Supplier Relationships: Collaborating closely with suppliers can secure favourable terms and ensure supply chain stability during economic fluctuations.
9. Invest in Technology: Leveraging technology to improve productivity and reduce costs can provide a competitive edge in uncertain economic times.
Conclusion
The looming U.S. debt refinancing challenge is a clarion call for businesses to reassess their strategies and fortify their operations against potential economic headwinds. By understanding the gravity of the situation and proactively implementing risk mitigation measures, business leaders can navigate the complexities ahead and ensure sustained growth and stability in an unpredictable financial landscape.
Get help to protect and grow your business faster with BusinessRiskTV
The connection between historical inaccuracies and bad risk management. How to improve you business risk management to improve your business performance with less uncertainty.
History. It’s the bedrock, right? The solid ground upon which we build our understanding of the present, and plan for the future. But what if that bedrock is riddled with cracks, fissures, and outright fabrications? What if the “facts” we cling to are merely the agreed-upon lies of a collective memory, shaped by biases, power struggles, and the ever-shifting sands of time?
History is often simply the agreed lies of what the past looks like. Rebel against the history we are creating today to ensure we have a better tomorrow. By Keith Lewis
Consider this: a staggering percentage of strategic business decisions, in fact, are based on historical analysis. But what if that history is wrong? We’re building castles on sand! In the realm of enterprise risk management, this is not just an academic musing; it’s a critical vulnerability. We believe we learn from the past. But are we really learning from reality, or are we simply reinforcing flawed narratives? I’ve seen it firsthand. We need to challenge the very notion of historical certainty. Because if we don’t, we risk repeating the same catastrophic mistakes, driven by illusions rather than genuine insight.
Part 1: The Fabricated Foundations – Six Risk Event Falsehoods
Let’s dive into some specific cases where the perceived “facts” of risk events were demonstrably false, and how these falsehoods shaped subsequent risk management strategies.
The Challenger Disaster: The O-Ring Myth.
The commonly accepted narrative surrounding the 1986 Challenger space shuttle disaster centred on the failure of the O-rings due to cold temperatures. This narrative became the cornerstone of risk management reforms at NASA. However, a deeper analysis revealed a far more complex picture. The O-rings were a contributing factor, yes. But the disaster was rooted in a culture of organisational pressure, flawed decision-making, and a systemic disregard for dissenting voices. The focus on the O-rings alone, while technically accurate, masked the deeper, more insidious risks within NASA’s management structure. Consequently, post-disaster reforms focused heavily on technical improvements, while neglecting the crucial organisational and cultural issues. This led to a false sense of security, which, in turn, contributed to the later Columbia disaster. It’s a tragedy, and it repeats.
The 2008 Financial Crisis: The “Isolated Incident” Lie.
The 2008 financial crisis was initially portrayed as an isolated incident, a perfect storm of subprime mortgages and reckless lending practices. This narrative allowed many financial institutions to avoid fundamental reforms, clinging to the belief that the crisis was an anomaly. However, the reality was far more systemic. It exposed deep-seated flaws in regulatory oversight, risk modelling, and the very culture of Wall Street. The “isolated incident” lie prevented a thorough examination of these systemic risks, leading to a patchwork of regulatory changes that failed to address the root causes. The result? A financial system still vulnerable to future shocks.
The Enron Collapse: The “Rogue Trader” Delusion.
The Enron scandal was often attributed to a few rogue traders and executives who acted independently. This narrative absolved the company’s broader culture and governance structures from responsibility. However, the reality was that Enron’s culture of aggressive accounting practices, unchecked ambition, and a complete lack of transparency permeated the entire organisation. The focus on “rogue traders” allowed many companies to believe they were immune to similar risks, as long as they kept a close eye on individual actors. This narrow view prevented a wider recognition of the systemic risks associated with corporate culture and ethical leadership.
The BP Deepwater Horizon Oil Spill: The “Technical Failure” Fallacy.
The Deepwater Horizon disaster was initially framed as a technical failure of the blowout preventer. While the blowout preventer did fail, the disaster was a culmination of systemic failures in risk management, cost-cutting measures, and a disregard for safety protocols. The “technical failure” narrative allowed BP and the industry to focus on improving equipment, while downplaying the crucial role of human error and organisational culture. This limited approach left the industry vulnerable to similar disasters, as the underlying systemic risks remained unaddressed.
The Space Shuttle Columbia Disaster: The “Foam Strike” Misinterpretation.
Initially, the foam strike on the Columbia shuttle was seen as a minor, inconsequential event. The narrative was that the foam was a known, minor risk that posed no threat to the integrity of the shuttle. This was a critical misinterpretation. The reality was that the damage caused by the foam was significant and ultimately led to the catastrophic reentry. The misinterpretation arose from a culture of normalisation of deviance. Small deviations from expected outcomes were accepted over time, until they became the new normal. This led to a severe underestimation of the true risks involved. The risk management improvements made were too little, too late.
The COVID-19 Pandemic: The “Foreign Threat” Simplification, lab-produced or natural evolution and building back better
The truth about the COVID-19 pandemic has yet to be unwrapped. Multi inquiries are ongoing. Personnel changes of key government bodies in America post recent election result may uncover more lessons to be learned from health risk management mistakes of COVID pandemic.
Part 2: The Business Risk Management Context – Challenging the Narrative
These examples illustrate a critical point: risk management strategies built on flawed historical narratives are inherently vulnerable. They create a false sense of security, blind us to systemic risks, and prevent us from learning from past mistakes.
The Problem of Confirmation Bias: We tend to seek out information that confirms our existing beliefs, even when those beliefs are flawed. In risk management, this can lead to a selective interpretation of historical data, reinforcing existing biases and preventing us from seeing the full picture.
The Danger of Simplification: Complex risk events are often reduced to simple narratives, focusing on isolated incidents or individual failures. This simplification obscures the underlying systemic risks and prevents us from developing effective mitigation strategies.
The Illusion of Control: We often believe that we have more control over events than we actually do. This illusion can lead to overconfidence in our risk management capabilities and a failure to anticipate unexpected outcomes.
The Impact of Organisational Culture: Organisational culture plays a crucial role in shaping how risks are perceived and managed. Cultures that discourage dissent, prioritise short-term gains over long-term sustainability, or normalise deviance are particularly vulnerable to risk events.
The Importance of Critical Thinking: Effective risk management requires a willingness to challenge conventional wisdom, question assumptions, and engage in critical thinking. This includes scrutinising historical narratives and seeking out alternative perspectives.
The need for accurate data: Data, when collected and analysed correctly is vital to risk management. However, when the data is wrong, or missunderstood, it can lead to terrible decsions.
Part 3: Reclaiming the Future – Nine Strategies for Improved Risk Management
Embrace Diverse Perspectives: Actively seek out and incorporate diverse perspectives into your risk assessments. This includes challenging your own biases and assumptions, and encouraging dissenting voices.
Conduct Root Cause Analysis: Move beyond surface-level explanations and conduct thorough root cause analyses of risk events. This involves digging deep to identify the underlying systemic factors that contributed to the event.
Develop Scenario Planning: Use scenario planning to explore a range of potential future outcomes, including those that challenge conventional wisdom. This can help you anticipate unexpected risks and develop contingency plans.
Promote a Culture of Transparency: Foster a culture of transparency and open communication, where employees feel safe to raise concerns and report potential risks.
Invest in Data Analytics: Leverage data analytics to identify patterns and trends that may indicate emerging risks. This includes using predictive analytics to anticipate future events.
Enhance Risk Communication: Develop clear and effective communication strategies to ensure that risk information is disseminated to all relevant stakeholders.
Implement Continuous Monitoring: Establish continuous monitoring systems to track key risk indicators and identify potential threats in real-time.
Foster a Learning Organisation: Create a culture of continuous learning, where mistakes are seen as opportunities for improvement. This includes conducting post-event reviews and sharing lessons learned.
Challenge Historical Narratives: Encourage critical examination of historical narratives and challenge assumptions about the past. This includes seeking out alternative perspectives and questioning the “facts” that are commonly accepted.
Conclusion: The Responsibility of Reinterpretation
History is not a static entity; it is a living, breathing narrative that is constantly being reinterpreted. We have a responsibility to challenge the comfortable lies of the past and to create a more accurate and nuanced understanding of our history. By doing so, we can build a more resilient, informed, and ultimately, successful future. In the realm of enterprise risk management, this means moving beyond simplistic narratives and embracing a more critical and holistic approach.
We must recognise that the stories we tell ourselves about the past shape our perceptions of the present and our expectations for the future. When those stories are flawed, so too are our decisions.
Consider the implications. If we continue to accept historical narratives without question, we risk repeating the same mistakes, driven by illusions rather than genuine insight. We become trapped in a cycle of reactive management, constantly responding to crises that could have been avoided.
But there is another path. We can choose to be active participants in the construction of our own narratives. We can choose to challenge assumptions, question conventional wisdom, and seek out alternative perspectives. We can choose to embrace the complexity of history and to learn from its lessons, even when those lessons are uncomfortable.
This requires a shift in mindset. It requires a willingness to acknowledge our own biases and limitations. It requires a commitment to continuous learning and improvement.
In practical terms, it means:
Cultivating a culture of intellectual curiosity: Encourage your teams to ask “why” and “what if.” Promote open dialogue and debate.
Investing in critical thinking training:Equip your employees with the tools and skills they need to analyse information and identify biases.
Building diverse teams: Seek out individuals with different backgrounds, perspectives, and experiences.
Implementing robust data governance: Ensure that your data is accurate, reliable, and accessible.
Establishing independent review processes: Create mechanisms for challenging assumptions and validating findings.
By taking these steps, we can move beyond the limitations of flawed historical narratives and create a more informed and resilient organisation.
Remember, the future is not predetermined. It is shaped by the choices we make today. And those choices are informed by the stories we tell ourselves about the past.
Let us choose to tell stories that are grounded in reality, that embrace complexity, and that empower us to create a better tomorrow. Let us rebel against the comfortable lies, and embrace the challenging truths. For in doing so, we not only rewrite history, we rewrite our future.
The responsibility to reinterpret, to question, and to learn, rests with each of us. The time to begin is now. Let’s build a future founded on accurate understanding, and not on the shifting sands of agreed upon falsehoods.
Get help to protect and grow your business faster with more certainty