Business risk management isn’t red tape—it’s the cheapest strategic advantage a UK SME has. This guide explains why risk management has never been more critical for SME survival, what it looks like in practice (a one-page risk register and a 30-minute monthly review), who benefits most, and when to use it in strategic, operational and project decisions. Includes 9 low-cost, high-impact tips and UK government and ONS data to back it up. Recommended by the BusinessRiskTV Business Risk Management Club.
Most UK SMEs ignore business risk management until it’s too late. Discover why it matters, what it looks like, and 9 practical tips to protect your business.
What Is Business Risk Management? A Practical Guide for Business Owners and Directors
BusinessRiskTV Business Risk Management Club recommends SME business owners and directors use business risk management philosophy and methodology to better protect and grow their business in UK. Here is the uncomfortable truth most SME owners avoid: you are already managing risk every day—you just aren’t calling it that. Every time you chase a late payment, wonder if your biggest client will renew, or hope your key engineer doesn’t quit, you are reacting to risk. The difference between surviving and thriving is whether you do it deliberately, or let it happen to you. With 5.7 million SMEs accounting for 99.9% of the UK business population and 60% of private sector employment , the collective cost of SME risk blindness is staggering. This guide is not about bureaucracy. It is about turning risk from a threat into a competitive weapon.
Why Has Business Risk Management Never Been More Critical to SME Performance, Growth and Survival in the UK?
Business risk management has never been more critical because UK SMEs now operate in a permacrisis of energy volatility, supply chain fragility, cyber extortion, and regulatory creep—where a single unmanaged shock can erase years of margin. Look at the data. In late October 2026, 77% of businesses with 10 or more employees expressed concern about energy prices, and 76% about fuel prices . Nearly two-thirds expected sourcing material costs to be impacted by supply chain concerns . This is not background noise. It is the operating environment.
The cyber threat is equally brutal. Government data shows 20% of businesses experienced a cyber crime in the last 12 months, with phishing affecting 18% of all businesses and ransomware hitting an estimated 19,000 businesses . For micro businesses, phishing is the most disruptive breach type, hitting 68% of those affected . Meanwhile, fraud incidents estimated by the Crime Survey for England and Wales reached 4.2 million in the year ending September 2025, with recorded fraud offences up 12% .
Here is the thought-provoking part: most SME owners would never dream of driving without insurance, yet they run their entire business without a risk register. As the old adage goes, “Risk comes from not knowing what you’re doing.” The SMEs that treat risk management as a luxury are the ones most likely to become a statistic.
What Does Business Risk Management Actually Look Like in Practice for a UK SME?
Business risk management in a UK SME looks like a one-page risk register, a monthly thirty-minute review, and a decision-making habit—not a forty-page policy document that nobody reads. It is identifying your top five risks, assigning a name to each, and asking one question every month: “Has this got better or worse?” ISO 31000, the international standard for risk management, defines it as a process of identifying, analysing, evaluating, treating, monitoring and communicating risk . But you do not need a consultant to do this. You need discipline.
In practice, it looks like this:
A risk register that lists your top ten risks, scored on likelihood and impact, with a named owner for each.
A cash flow stress test that asks: what happens if our biggest customer pays 30 days late, or disappears entirely?
A cyber hygiene checklist covering multi-factor authentication, phishing training, and backup protocols—because 93% of cyber crimes experienced by businesses are phishing.
A supply chain map that identifies single points of failure. The ONS found 64% of businesses with 10+ employees expected material sourcing costs to be impacted by supply chain concerns in October 2026.
A decision gate for every significant project or hire: what could go wrong, and what would we do if it did?The BusinessRiskTV Business Risk Management Club exists precisely because SMEs need a community, not a compliance manual. “You can’t control the weather, but you can build a stronger ship.”
Why Do Most SME Owners Resist Business Risk Management, and Why Are They Wrong?
Most SME owners resist business risk management because they equate it with insurance renewal paperwork and corporate box-ticking, when in reality it is the cheapest strategic advantage available to a small business. The evidence suggests a dangerous complacency. Only around 1.5% of UK SMEs apply for bank loans, reflecting a wider reluctance to engage with formal external finance and structured planning processes . If you won’t even fill in a loan application, you are almost certainly not running a risk register.
The resistance usually sounds like: “We’re too busy fighting fires to prevent them.” Or: “We know our business, we don’t need a spreadsheet to tell us what we already know.” But knowing something intuitively and managing it systematically are different things. The cyber data proves it: despite phishing being the most common cyber crime, many SMEs still do not train staff or enforce basic controls. The government’s Cyber Security Breaches Survey found that micro businesses were significantly more likely than larger firms to identify phishing as their most disruptive breach —precisely because they lack formal defences.
As Benjamin Franklin said, “An ounce of prevention is worth a pound of cure.” In SME terms, a £500 investment in phishing simulation training is cheaper than a single ransomware payment or the days of lost trading that follow a breach. Risk management is not a cost centre. It is a margin protection tool.
Who Will Benefit Most From Adopting Business Risk Management Philosophy and Practices?
The businesses that benefit most from business risk management are owner-managed SMEs with 5 to 100 employees, no dedicated risk function, and a high dependence on a small number of customers, suppliers, or key people. If you recognise yourself in that description, you are the person this is written for. The FSB reports that 5.6 million small businesses (0–49 employees) make up 99.2% of the total business population . The vast majority are owner-led, resource-constrained, and exposed.
Beyond that core group, the beneficiaries split into three categories:
Directors with personal guarantees or director loan accounts: unmanaged business risk is personal financial risk. A risk register that flags cash flow fragility is a director protection tool.
Businesses bidding for larger contracts or public sector work: procurement teams increasingly ask for evidence of risk management. A simple register signals competence and credibility.
SMEs in regulated sectors or supply chains with larger customers: the FCA’s Consumer Duty regime, for example, requires firms to evidence good outcomes and mitigate foreseeable harm. Risk management is becoming a commercial prerequisite, not a choice.The BusinessRiskTV Business Risk Management Club is built for exactly these people. “I have seen many businesses fail due to lack of planning, these workshops will provide you with the tools to plan.”
When Should Business Owners and Directors Use Business Risk Management in Strategic, Operational and Project Decision Making?
Business owners should use business risk management at three specific trigger points: before committing irreversible capital, before signing a contract that concentrates exposure, and before launching a project with a fixed deadline and no contingency. Outside these triggers, risk management should be a light-touch monthly rhythm, not a daily obsession.
Strategic decisions—acquisitions, new premises, major hires, entering new markets—demand a pre-mortem. Ask: “If this fails in twelve months, what will the most likely cause be?” The ONS shows 21% of businesses with 10+ employees were concerned about cyber attacks impacting supply chains in late 2026, up 9 percentage points year-on-year . A strategic decision to onboard a new critical supplier without a cyber assessment is a risk you can now see coming.
Operational decisions—pricing changes, credit terms, staffing levels—require a cash flow sensitivity check. If you extend payment terms to win a contract, what does that do to your working capital buffer? If you lose your second-in-command, what breaks?
Project decisions—a website rebuild, a new product line, a regulatory compliance programme—need a simple risk log with three columns: what could go wrong, how likely is it, what will we do about it. Review it at every project meeting. That is it. No software required.
As the old saying goes, “Fail to plan, plan to fail.” But the modern SME version is sharper: fail to identify the specific way you might fail, and you will almost certainly walk straight into it.
What Are the 9 Practical Tips to Adopt Business Risk Management in an SME That Has Struggled to See the Worth?
The nine practical tips to adopt business risk management in a sceptical SME are deliberately low-cost, low-time, and high-impact—designed to prove value within ninety days rather than demand a leap of faith. Each tip below is something you can start this week.
Start with a one-page risk register, not a framework. List your top ten risks. Score each 1–5 for likelihood and 1–5 for impact. Multiply them. Anything above 15 gets a named owner and a monthly review. Do not buy software. Use a spreadsheet.
Run a thirty-minute monthly risk huddle. Put it in the diary. Same time every month. Agenda: what changed, what got worse, what are we doing about it. This single habit is the difference between a living process and a dead document.
Stress-test your cash flow against a 30-day late payment from your biggest customer. If that scenario would break you, you have found your number one risk. The ONS energy and fuel concern data shows how quickly external shocks hit margins . Cash is the risk that kills fastest.
Treat cyber as a business continuity risk, not an IT problem. Enable multi-factor authentication everywhere. Run a phishing simulation. Check your backups restore properly. Government data shows phishing accounts for 93% of cyber crimes experienced by businesses . You do not need a cyber security degree to close the front door.
Map your critical dependencies. Who are the three customers, three suppliers, and three people you could least afford to lose? Write down what happens if each disappears tomorrow. Then ask what a 10% concentration reduction would look like over twelve months.
Put a risk question on every board agenda. One item: “What is the biggest risk we are currently ignoring?” This normalises the conversation and surfaces blind spots before they become crises.
Use a pre-mortem for every significant decision. Before you commit, gather the people involved and ask: “It is twelve months from now and this decision has failed. What went wrong?” The answers become your mitigation plan. This takes twenty minutes and costs nothing.
Build a simple incident response card for each top risk. If X happens, who calls who, what do we do first, where is the information? A single side of A4 per risk. Store it where you can find it when stressed. Because you will be stressed.
Measure one thing: risk actions completed. Not risks identified. Not documents written. Actions completed. This keeps the process honest and proves value. If the register grows but nothing changes, you are doing theatre, not management. The BusinessRiskTV Business Risk Management Club recommends this philosophy because it respects the two things SME owners never have enough of: time and money. “Risk management is not about avoiding risk. It is about knowing which risks are worth taking.
What Does Success Look Like for an SME That Embraces Business Risk Management?
Success looks like fewer surprises, faster recovery, and the confidence to take bigger swings because you understand the downside. It is not the elimination of risk—that is impossible and undesirable. It is the transformation of risk from a source of anxiety into a source of advantage.
You will know it is working when:
A key customer goes quiet and you already have a cash buffer plan in motion.
A phishing email lands and your team reports it instead of clicking it.
A supplier fails and you have a pre-identified alternative.
You bid for a contract you would have previously avoided because you can evidence your controls.
You sleep better, because the monsters under the bed have names and sizes.
The UK SME sector is the engine of the economy . But engines need maintenance. Business risk management is that maintenance. It is not glamorous. It is not a growth hack. It is the quiet discipline that separates the businesses that last from the ones that become a cautionary tale. The BusinessRiskTV Business Risk Management Club exists to make that discipline accessible, practical, and worth the time. Subscribe. Join the Club. Build a stronger ship.
Get help to protect and grow your business faster with BusinessRiskTV
Business Risk Management UK – Protect Grow Survive
Your business doesn’t have a growth problem. It has a risk problem you’ve been calling “bad luck.”
Three late payments. One supplier that vanished. A key client who went quiet in Q3. You called it a rough patch. It wasn’t. It was unmanaged risk — and it cost you more than you’ve admitted to yourself.
Here’s what the data says, and it isn’t comfortable:
77% of UK businesses with 10+ employees are worried about energy prices. 76% about fuel. 20% experienced a cyber crime in the last 12 months. And 93% of those cyber crimes? Phishing — the cheapest attack to defend against and the one most SMEs ignore.
You wouldn’t drive without insurance. Yet most SME owners run the entire business without a one-page risk register.
That’s not brave. That’s exposed.
What actually drives performance is what we layer on top:
A one-page risk register. Ten risks. Scored. Named owners. Reviewed monthly.
A 30-minute risk huddle in the diary. Same time every month. Non-negotiable.
A cash flow stress test: what happens if your biggest customer pays 30 days late?
A pre-mortem before every big decision: “It’s 12 months from now and this failed. Why?”
One measure that matters: risk actions completed — not documents written.None of this costs money. All of it costs discipline. That’s the trade most owners refuse to make — and it’s why the same businesses keep getting surprised by the same shocks.
The BusinessRiskTV Business Risk Management Club recommends SME owners and directors adopt risk management philosophy and methodology to better protect and grow their business in the UK.
The businesses that last aren’t the ones that avoid risk. They’re the ones that name it, size it, and plan for it before it arrives.
Want the practical version — the register template, the monthly huddle agenda, the pre-mortem script? Email editor@businessrisktv.com for more information on the Business Risk Management Club.
Save this. Share it with the director who still thinks “we know our business” is a risk strategy.
Targets decision-makers searching for the financial impact of weak risk practices
THE HIDDEN TAX OF POOR RISK MANAGEMENT
Your business is leaking money. Not in the obvious ways — like overspending or inefficiency — but in silent, insidious drains you might not even see. Poor risk management isn’t just about avoiding disasters; it’s a profit killer, a growth stifler, and, in the worst cases, an executioner of businesses that could have thrived.
Consider this: 30% of bankruptcies are due to operational failures that could have been mitigated with better risk practices (OECD). That’s not bad luck—it’s self-inflicted. And if you think your company is immune, think again.
This isn’t theoretical. Every day, businesses hemorrhage cash through:
Employee disengagement —teams that don’t see risk as their problem, costing you in errors, delays, and lost innovation.
The result? Lower profitability. Stunted growth. And, in extreme cases, extinction.
But here’s the good news: this is entirely optional and fixable.
In this e-book, we’ll expose the 12 most damaging costs of poor risk management —many of which you’re likely paying right now — and deliver 12 actionable solutions to turn risk from a liability into a competitive advantage. You’ll learn how to:
Engage every employee in risk ownership (not just compliance, but profit protection).
Stop financial bleed from preventable failures.
Turn risk-aware decision-making into a growth engine.
This isn’t another dry risk management manual. This is a survival guide for profitable, resilient business leadership.
Ready to plug the leaks? Let’s begin.
🚨 YOUR BUSINESS IS LEAKING £££ – FIND THE HOLES! 🚨
83% of UK SMEs lose £50k+ yearly from hidden risks they don’t even measure:
❌ Operational failures burning cash ❌Supply chain disasters killing margins
❌ Cyberattacks costing millions
BusinessRiskTV’s NEW eBook reveals:
✅ 12 PROVEN FIXES to stop profit leaks
✅ Real case studies from UK businesses
✅ Simple checklists to act TODAY
Chapter 1: The Hidden Costs of Poor Risk Management – How Ignoring Risk Erodes Your Profits and Threatens Survival
Introduction: The Silent Profit Killer
Every business faces risks—some obvious, others invisible. But when risk management is an afterthought, those risks don’t just linger; they multiply costs, shrink margins, and sabotage growth. This chapter exposes the real financial and operational toll of poor risk management—and why most businesses underestimate it.
—
1. The Direct Financial Costs: Where the Money Leaks
A. Unexpected Losses from Operational Failures
Example: A manufacturing firm ignores equipment maintenance, leading to a breakdown that halts production for 48 hours. The result? £250,000 in lost revenue + £50,000 in emergency repairs.
Stat: Companies with weak operational risk management see 30% higher unexpected costs (Deloitte).
B. Regulatory Fines & Legal Penalties
Case Study: A UK SME in financial services fails to comply with GDPR, resulting in a £180,000 fine —plus reputational damage.
Stat: 60% of small UK businesses aren’t fully compliant with key regulations (FSB).
Key Takeaway: Poor risk management isn’t just about avoiding disasters — it’s a tax on profitability, growth, and survival.
—
Actionable Insight: Audit one high-cost risk in your business this week (e.g., late payments, compliance gaps). What’s it really costing you?*
—
Chapter 2: The True Cost of Operational Failures – How Inefficient Risk Management Cripples Your Business
Introduction: The Domino Effect of Poor Operational Risk Controls
Operational risks don’t just cause one-off incidents—they trigger chain reactions that drain cash, demoralise teams, and erode customer trust. This chapter exposes the hidden, cascading costs of mismanaged operational risks and why most businesses only see the tip of the iceberg.
—
1. The Obvious Costs: What You Can’t Ignore
A. Downtime & Lost Production
Manufacturing Example: A single machine failure halts a production line for 8 hours → £25,000 in lost output + overtime costs to catch up.
Hospitality Example: A restaurant’s refrigeration breakdown spoils £3,000 of stock overnight — plus angry customers.
Stat: UK manufacturers lose £180 billion/year to unplanned downtime (EEF).
B. Emergency Repairs & Rush Orders
Reactive spending costs 3–5X more than planned maintenance.
Case Study: A logistics firm ignores fleet maintenance → two vans fail MOTs simultaneously → £8k in last-minute rentals + delayed deliveries.
C. Waste & Rework
Construction Example: Poor quality control leads to £50,000 of defective materials — then doubles labour costs to fix errors.
Stat: 20–30% of project budgets are wasted on rework (KPMG).
—
2. The Hidden Costs: What You’re Not Tracking (But Should Be)
A. Employee Productivity Drain
Scenario: A retail store’s outdated inventory system causes daily stock discrepancies. Staff waste 4 hours/day manually reconciling data instead of selling.
Stat: UK workers spend 15% of their time fixing preventable issues (PwC).
B. Management Distraction & Burnout
Small Business Reality: The owner spends 60% of their week putting out fires (supplier delays, IT crashes) instead of growing the business.
Psychological Cost: Chronic stress → poor decisions → more risks.
C. Customer Churn & Reputation Erosion
E-commerce Example: A fulfilment centre’s picking errors lead to 10% of orders arriving wrong → 15% of customers never return.
Stat: 70% of customers switch brands after just 2–3 bad experiences (Salesforce).
—
3. The Strategic Costs: How Operational Risks Stunt Growth
A. Lost Competitive Advantage
Case Study: A UK bakery’s unreliable oven delays a product launch by 3 months —competitors dominate supermarket shelves first.
B. Innovation Paralysis
Teams stuck in “firefighting mode” never test new ideas.
Example: A tech firm’s IT team spends 80% of time fixing outages → zero R&D progress.
C. Investor & Partner Distrust
Supply Chain Example: A fashion brand’s repeated delivery failures lead to two major retailers dropping them —£500k annual revenue gone.
—
4. The Survival Threat: When Operational Risks Become Fatal
A. Cash Flow Death Spiral
Construction Firm Case Study:
1. Poor contract risk assessment → unpaid invoices pile up
2. Equipment breakdown → project delays
3. Penalties for late delivery → bank calls in loan Result: Administration within 6 months.
B. The Carillion Effect
How ignoring operational risks (contract mismanagement, cash flow gaps) led to the UK’s biggest corporate collapse.
—
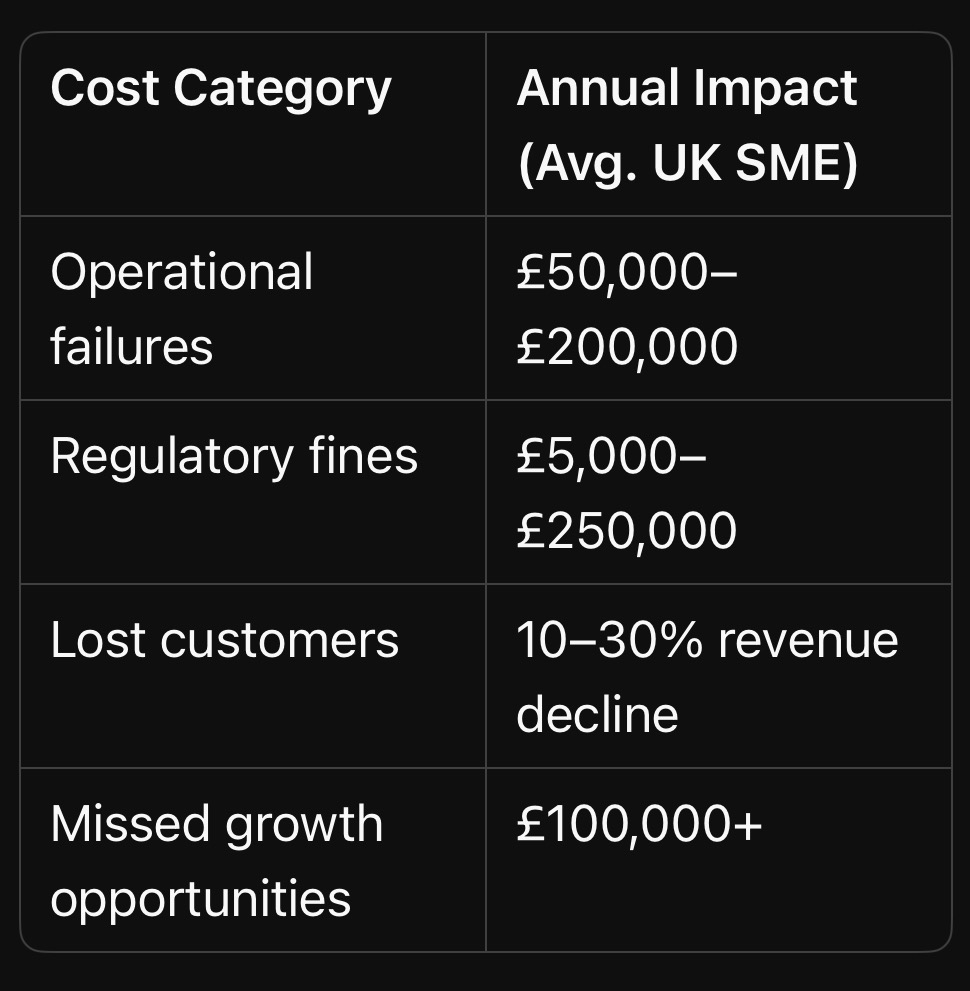
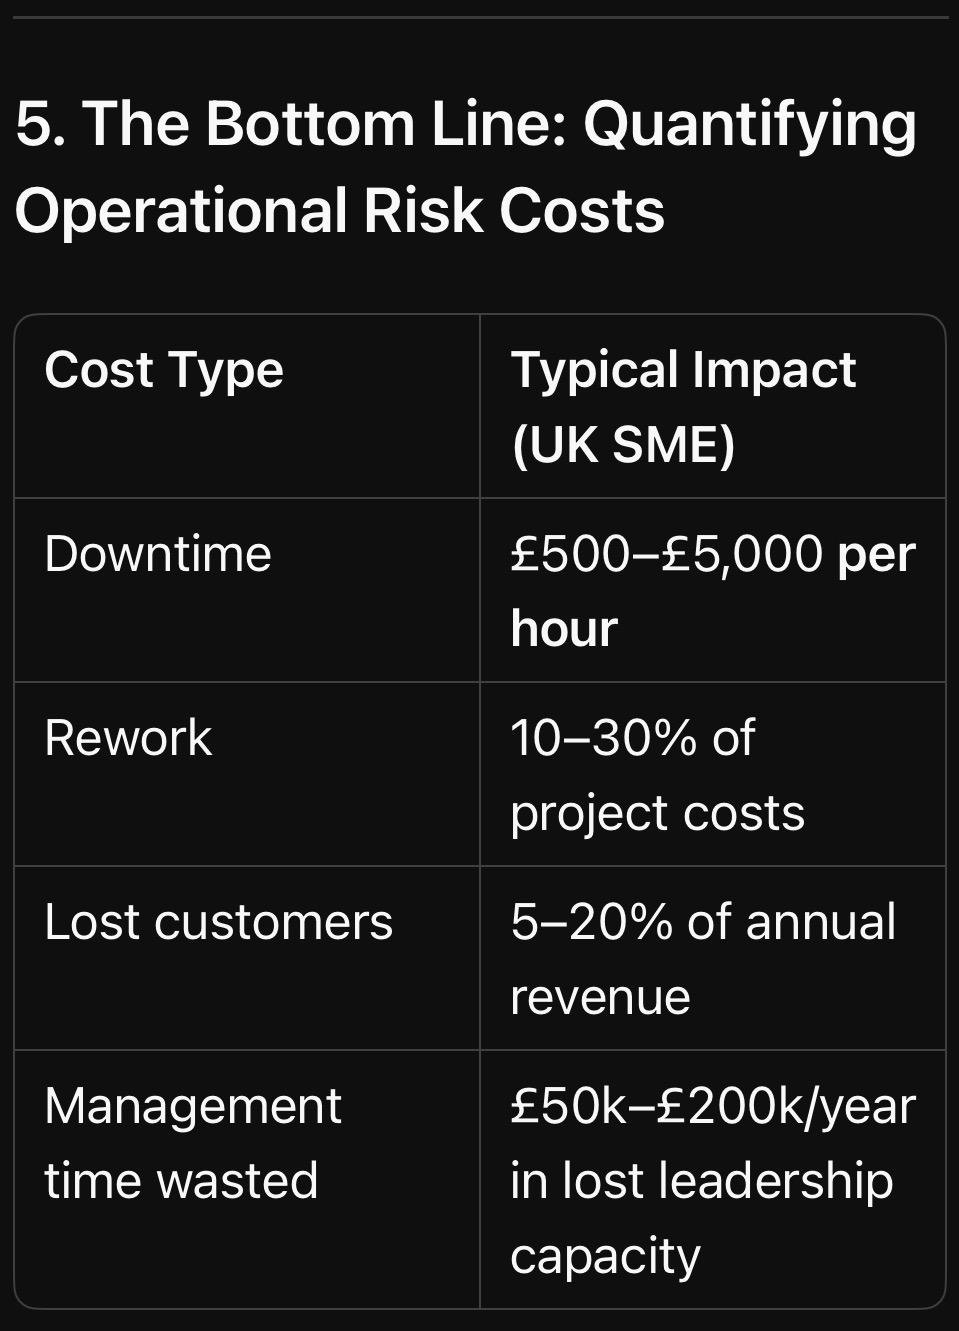
5. The Bottom Line: Quantifying Operational Risk Costs
Key Insight: Operational risks don’t just cost money—they steal time, talent, and future opportunities.
—
More From BusinessRiskTV Business Experts Hub : How to Fix It
We explore how to turn operational risk management into a profit centre, including:
The 5-minute daily habit that prevents 80% of failures
How to engage frontline teams in risk reduction (with real-world examples)
Actionable Task: Map one critical operational process (e.g., order fulfilment). Where could a single failure cost you £10k+?
—
Chapter 3: Strategic Risks – How Blind Spots in Planning Can Bankrupt Even Profitable Businesses
Introduction: The Silent Assassin of Business Growth
Strategic risks don’t announce themselves with alarms — they creep in unnoticed while leadership is distracted by day-to-day operations. By the time the damage is visible, it’s often too late to pivot. This chapter exposes how poor strategic risk management destroys market position, erodes competitive edge, and turns industry leaders into cautionary tales.
—
1. What Are Strategic Risks? (And Why They’re Different)
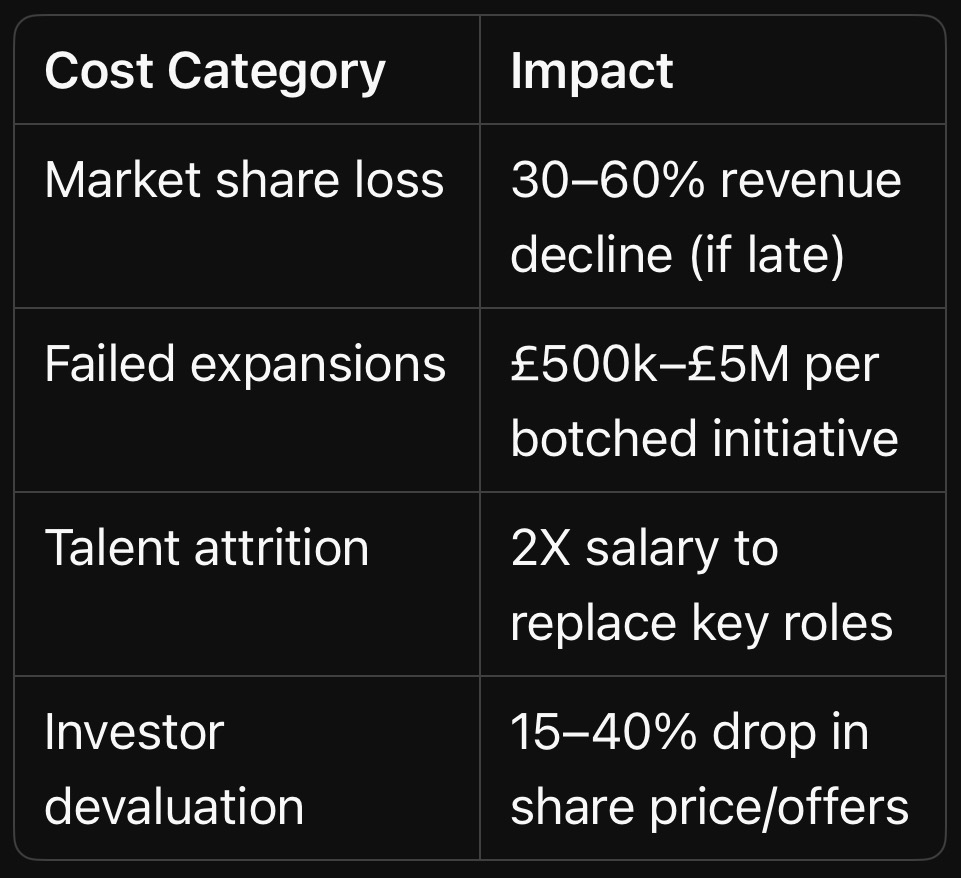
Key Takeaway: Strategic risks don’t just hurt profits — they erase entire business models.
—
More from BusinessRiskTV Business Experts Hub : How to Anticipate & Outmanoeuvre Strategic Risks
We explore practical frameworks to:
Spot industry shifts early (using weak signals)
Stress-test your strategy against disruption
Turn risks into opportunities (like Amazon’s pivot from books to cloud)
Actionable Task: List one strategic assumption your business relies on (e.g., “Customers will always prefer X”). How would you survive if it’s wrong?
—
Chapter 4: Financial Risks – How Poor Cash Flow & Debt Management Can Sink Your Business Overnight
Introduction: The Silent Killer of Healthy Businesses
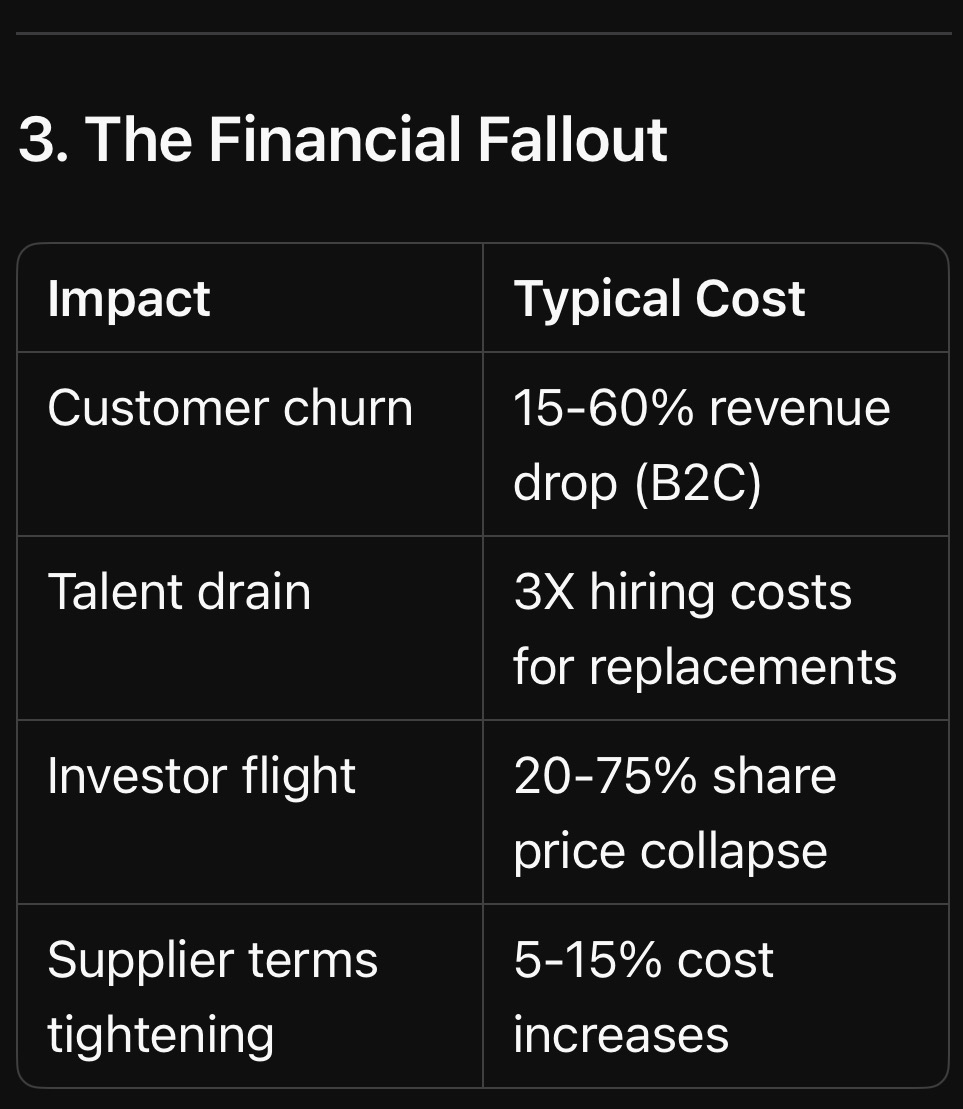
Profit doesn’t equal survival. Thousands of UK businesses post record revenues—right before going bust. Why? Because financial risk management isn’t about counting pennies — it’s about anticipating traps that strangle cash flow, trigger defaults, and collapse supply chains.
This chapter exposes the lethal financial risks hiding in plain sight — and why even profitable companies run out of money.
—
1. The Obvious (But Ignored) Financial Risks
A. Cash Flow Crises – The #1 Business Killer
Reality: 82% of UK business failures cite cash flow problems as the primary cause (UK Insolvency Service).
Example: A £5M-turnover construction firm collapses because:
– Client pays invoices 90 days late
– Supplier demands upfront payments due to past delays
– Bank rejects emergency loan Result: Liquidation despite £1.2M in “paper profits.”
B. Debt Avalanches – When Borrowing Backfires
Case Study: A fast-growing e-commerce firm takes on high-interest debt to fund inventory. Sales dip, interest compounds, and suddenly 60% of revenue services debt.
– Stat: 40% of UK SMEs struggle with unmanageable debt (Bank of England).
C. Currency & Commodity Swings
Example: A UK bakery’s flour costs jump 30% after a wheat shortage. Contracts lock in prices — margins vanish overnight.
—
2. The Hidden Financial Risks That Compound Quietly
A. Customer Concentration Risk
Scenario: A B2B software firm gets 70% of revenue from one client. When that client leaves, payroll can’t be met.
Rule of Thumb: No single client should exceed 15–20% of revenue.
B. Supplier Dependency & Price Shocks
Case Study: A car manufacturer relies on one battery supplier. When shortages hit, production stalls for 3 months → £9M loss.
C. Fraud & Financial Mismanagement
Stat: UK businesses lose £137B yearly to fraud, waste, and accounting errors (PwC).
Example: A finance director “cooks the books” — investors pull out when the truth surfaces.
—
3. The Strategic Fallout: When Financial Risks Spiral
A. Credit Downgrades & Banking Nightmares
Example: A once-stable firm misses a loan covenant — interest rates spike 5%, lines of credit freeze.
B. Investor Panic & Equity Crashes
Case Study: A tech startup’s burn rate exceeds projections — VCs demand emergency restructuring, slashing valuation by 50%.
C. Employee Exodus (When Paychecks Bounce)
Stat: 78% of employees leave within 6 months of payroll issues (CIPD).
—
4. The Ultimate Cost: Bankruptcy Dominoes
A. The “Profitable But Insolvent” Paradox
How It Happens:
1. Big contracts signed → revenue looks strong
2. Clients pay late → cash dries up
3. Suppliers demand payment → no money for salaries/tax
4. HMRC forces liquidation despite “growth.”
B. The Carillion Effect (Again)
£7B collapse triggered by:
– Aggressive accounting
– Reliance on unsustainable contracts
– No cash buffer for delays
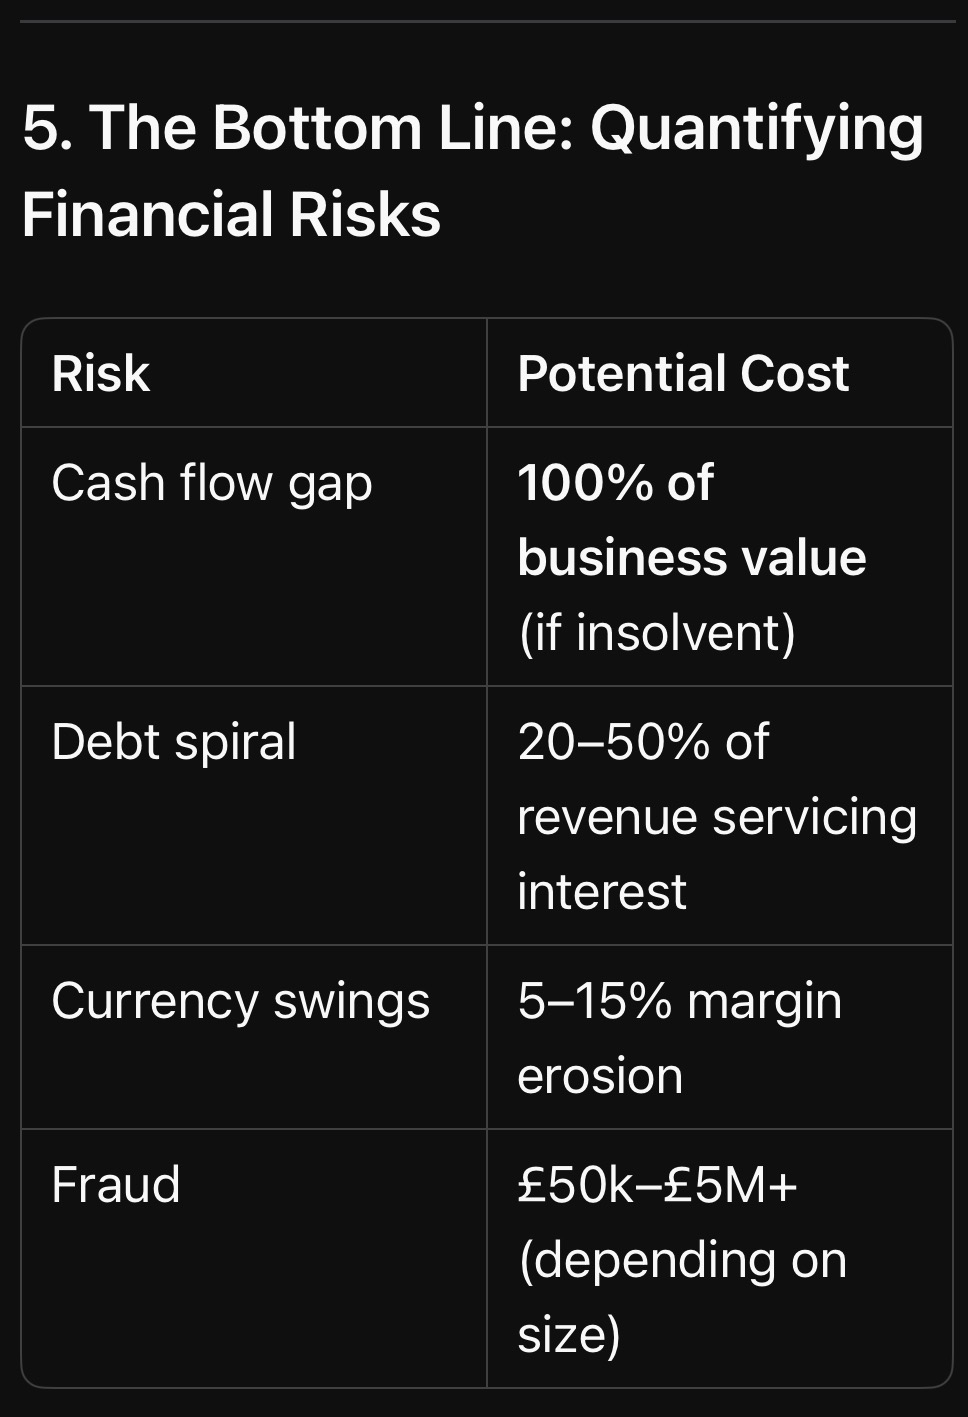
Key Insight: Financial risks don’t just reduce profits — they erase businesses in weeks.
—
More from BusinessRiskTV Business Experts Hub : How to Fix It
We explore real-world financial risk strategies, including:
The 13-week cash flow rule (used by turnaround experts)
How to renegotiate debt before it’s too late
Building a “war chest” for crises
Actionable Task: Run a “stress test” on your cash flow: What if 2 clients pay 60 days late?
—
Chapter 5: Cyber Risks – The Invisible Threat That Could Bankrupt Your Business by Breakfast
Introduction: The Digital Time Bomb Ticking in Your Business
Imagine arriving at work to find:
Your customer database on the dark web
Fraudsters draining £250,000 from your account
Ransomware locking every file until you pay Bitcoin
This isn’t a movie plot — it’s Monday morning for thousands of UK businesses. Cyber risks don’t just steal data; they extort cash, destroy reputations, and trigger regulatory hell. And here’s the worst part: Most victims never see it coming until the damage is done.
—
1. The Direct Costs: What Happens When Cybercrime Hits
A. Ransomware: The Digital Kidnapping Epidemic
2023 Reality: A UK construction firm’s blueprints, invoices, and payroll systems encrypted. Hackers demand £120,000 to unlock files.
Stat: 73% of UK businesses hit by ransomware in 2023 (NCSC).
Brutal Truth: Paying doesn’t guarantee recovery — 32% never get full data back (Sophos).
B. Data Breaches: When Your Customers Become Victims
Case Study: A mid-sized retailer’s poorly secured e-commerce platform leaks 380,000 credit cards.
£500,000 GDPR fine
£1.2M in fraud reimbursements
22% customer churn
Stat: Average UK data breach cost: £3.4 million (IBM).
C. Business Email Compromise (BEC): The Silent Heist
How It Works: A hacker impersonates your CEO, emails finance: “Urgent: Transfer £80k to new supplier.”
UK Losses: £1.3 billion stolen via BEC in 2023 (UK Finance).
—
2. The Hidden Costs That Cripple You Later
A. Reputation Freefall & Customer Exodus
After a breach:
– 58% of customers avoid breached brands (Verizon)
– Recovery Cost: 3–5X more on marketing to rebuild trust
B. Operational Paralysis
Example: A law firm’s servers go down for 72 hours post-attack. £350k in billable hours lost + client lawsuits.
C. Insurance Nightmares
Post-Claim Realities:
– Premiums triple
– Mandatory audits drain management time
– Some policies simply won’t renew
—
3. The Strategic Fallout: Long-Term Business Damage
A. Lost Contracts & Blacklisting
Government/Corporate Tenders Now Demand:
– Cyber Essentials Certification (missing? Disqualified automatically)
– Proof of incident response plans
B. Investor Flight
Startup Killer: A fintech’s pre-IPO breach scares off VCs, slashing valuation by 60%.
C. Director Liability (Yes, You Can Go to Jail)
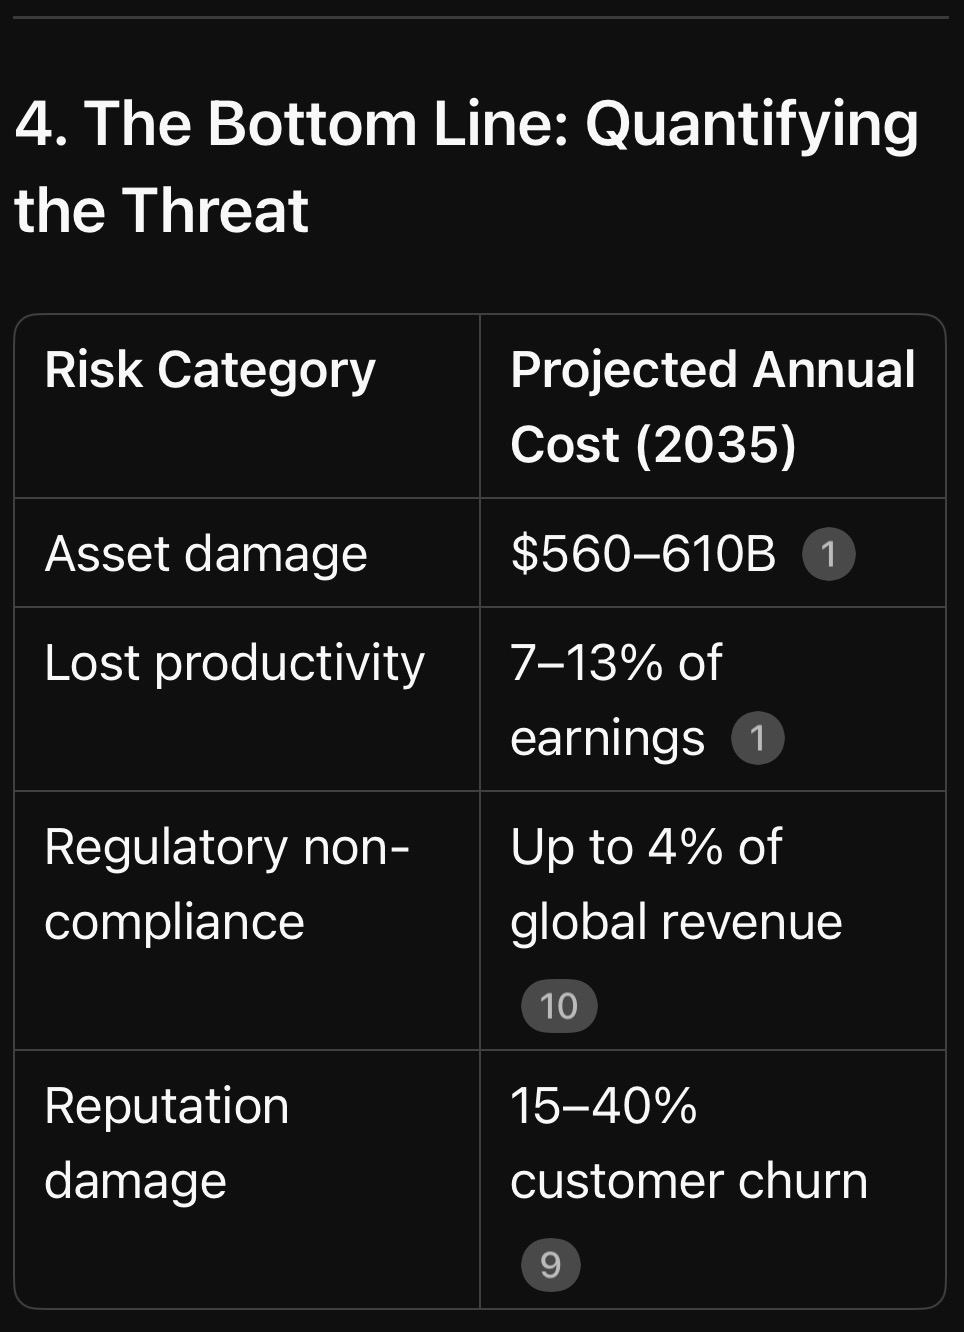
UK Law: Under GDPR & NIS Directive, negligent executives face fines up to £17.5M or 4% of global revenue — plus disqualification.
—
4. Why Cyber Risks Are Worse Than You Think
A. It’s Not Just “Big Targets”
61% of UK attacks hit SMEs (Verizon) — hackers bet they’re unprepared.
B. Remote Work = 300% More Attack Surfaces
Example: An employee’s compromised home laptop gives hackers access to your entire CRM.
C. AI-Powered Attacks Are Here
New Threat: Deepfake audio of your CFO “calling” finance to wire funds.
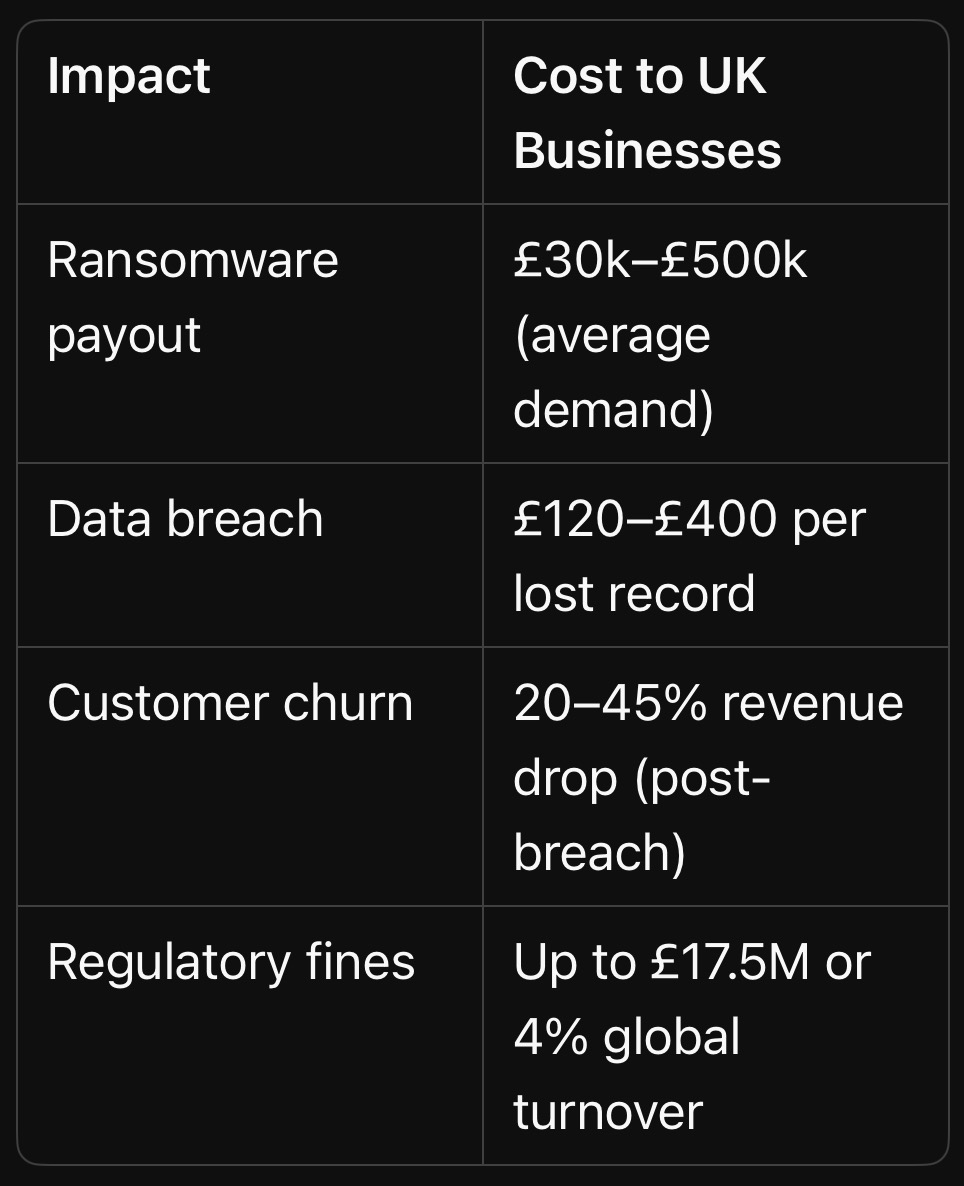
Key Insight: Cyber risks aren’t an “IT problem” — they’re an existential business threat.
—
More from BusinessRiskTV Business Experts Hub : How to Fight Back
We will explore real-world cyber defenses, including:
The 5-step SME ransomware shield (costs <£5k/year)
– How to trick hackers into avoiding you (attackers prefer easy targets)
– Turning employees into human firewalls
Actionable Task: Run this free test now: [Have I Been Pwned](https://haveibeenpwned.com/) to check if your work emails are already in hacker databases.
—
Chapter 6: Human Risks – When Your Greatest Asset Becomes Your Biggest Liability
Introduction: The Enemy Inside Your Walls
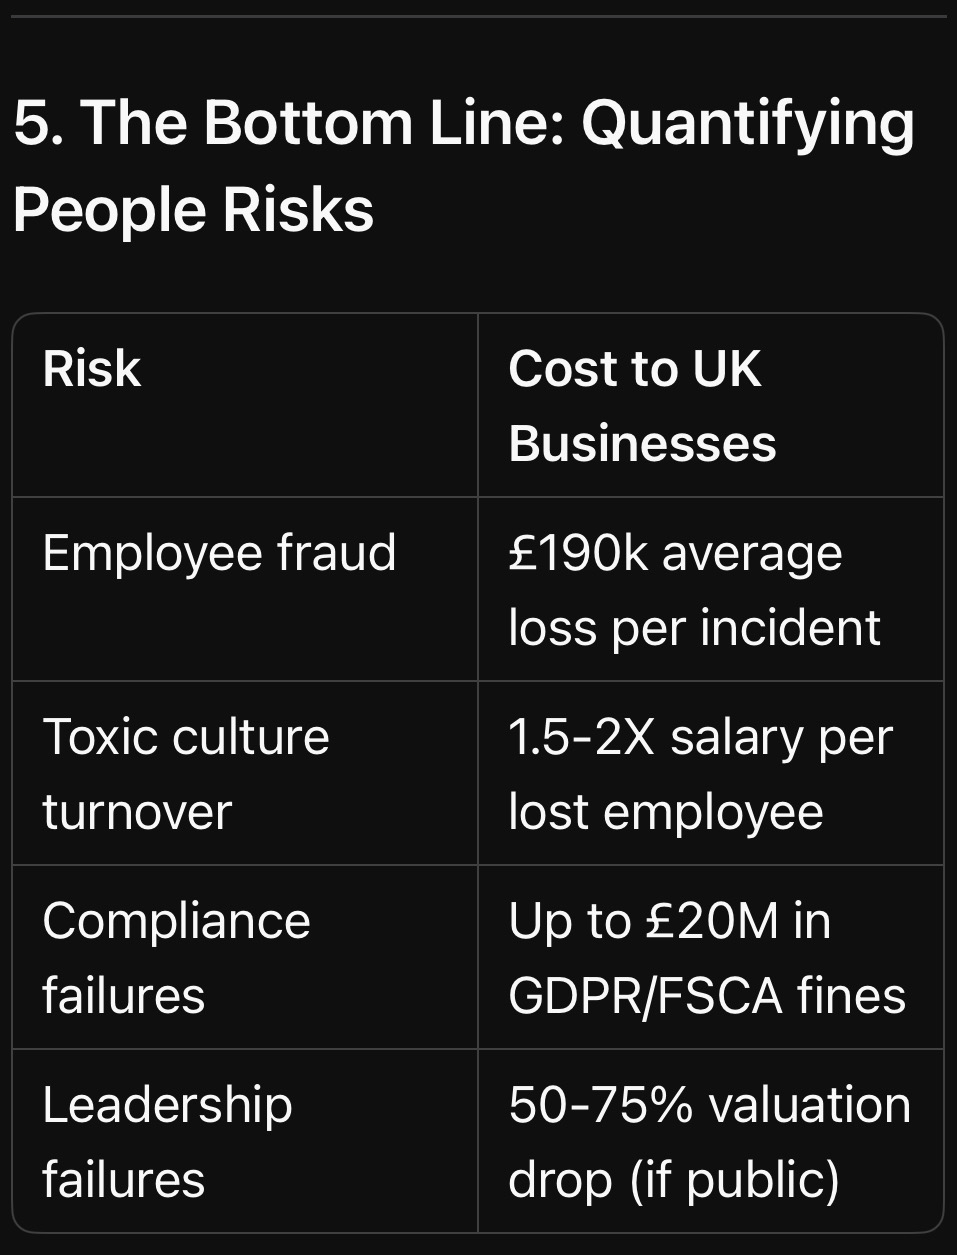
Your employees can either be your strongest defence — or your weakest link. Negligence, disengagement, and malicious actions cost UK businesses £30 billion annually (ACAS). This chapter exposes how poor people risk management leads to:
– Catastrophic errors
– Culture collapse
– Regulatory disasters
– Fraud epidemics
And why traditional HR policies fail to prevent 89% of these risks (PwC).
—
1. The Obvious (But Ignored) Human Risks
A. The High Cost of Disengagement
Example: A retail chain’s apathetic staff miss 40% of shoplifting incidents —costing £220,000/year in stolen stock.
Stat: Disengaged employees are 450% more likely to cause operational errors (Gallup).
B. Turnover Tsunamis
Case Study: A tech firm’s toxic culture drives out 7 senior engineers in 6 months — delaying a £2M product launch by 11 months.
Replacement Cost: Up to 2X annual salary per lost employee (Oxford Economics).
C. Training Gaps That Become Legal Nightmares
Reality Check: A warehouse worker badly operates a forklift, causing £80k in damages + HSE fines—because “training was just a 10-minute video.”
—
2. The Hidden (But More Dangerous) Human Risks
A. Insider Threats: When Employees Attack
Shocking Stat: 58% of data breaches involve insiders (Verizon).
Methods:
– The Malicious: IT admin sells customer data (£50k on dark web)
– The Careless: Accountant emails payroll files to personal Gmail
B. Culture Risks: How Toxicity Spreads
Example: A sales team’s “win at all costs” mentality leads to fraudulent client promises — £600k in lawsuits + FCA investigation.
C. Leadership Blind Spots
CEO Overconfidence: Ignoring team warnings about a flawed expansion → £3M write-off.
Stat: 82% of business failures trace back to poor leadership decisions (KPMG).
—
3. The Strategic Fallout: When People Risks Sink Companies
A. The Volkswagen Emissions Scandal
Root Cause: A culture where “nobody dared question” fraudulent engineering.
– Cost: €32 billion in fines/losses + permanent brand damage.
B. The Barclays CEO Scandal
How It Happened: Leadership’s obsession with “star hires” led to unchecked bullying — triggering £1M fines + investor revolt.
C. The Everyday SME Killer
Scenario: Your “trusted” bookkeeper embezzles £150k over 3 years — exposed only during a tax audit.
—
4. Why Traditional Approaches Fail
Annual compliance training?86% of employees forget it within 30 days (MIT).
“Hotline whistleblowing”?62% of staff fear retaliation (EY).
Top-down policies? Frontline teams see them as “head office nonsense.”
Key Insight: Your employees create or destroy value daily — often without realising it.
—
More from BusinessRiskTV Business Experts Hub : How to Transform Human Risk into Advantage
We explore battle-tested solutions, including:
The “Psychological Safety” hack
How to spot insider threats before they strike
Turning compliance into competitive edge
Actionable Task: Run a 5-minute “risk culture pulse check” with your team this week: “What’s one process you think could fail catastrophically?”
—
Chapter 7: Supply Chain Risks – The Fragile Web That Could Strangle Your Business Overnight
Introduction: Your Business Is Only as Strong as Its Weakest Supplier
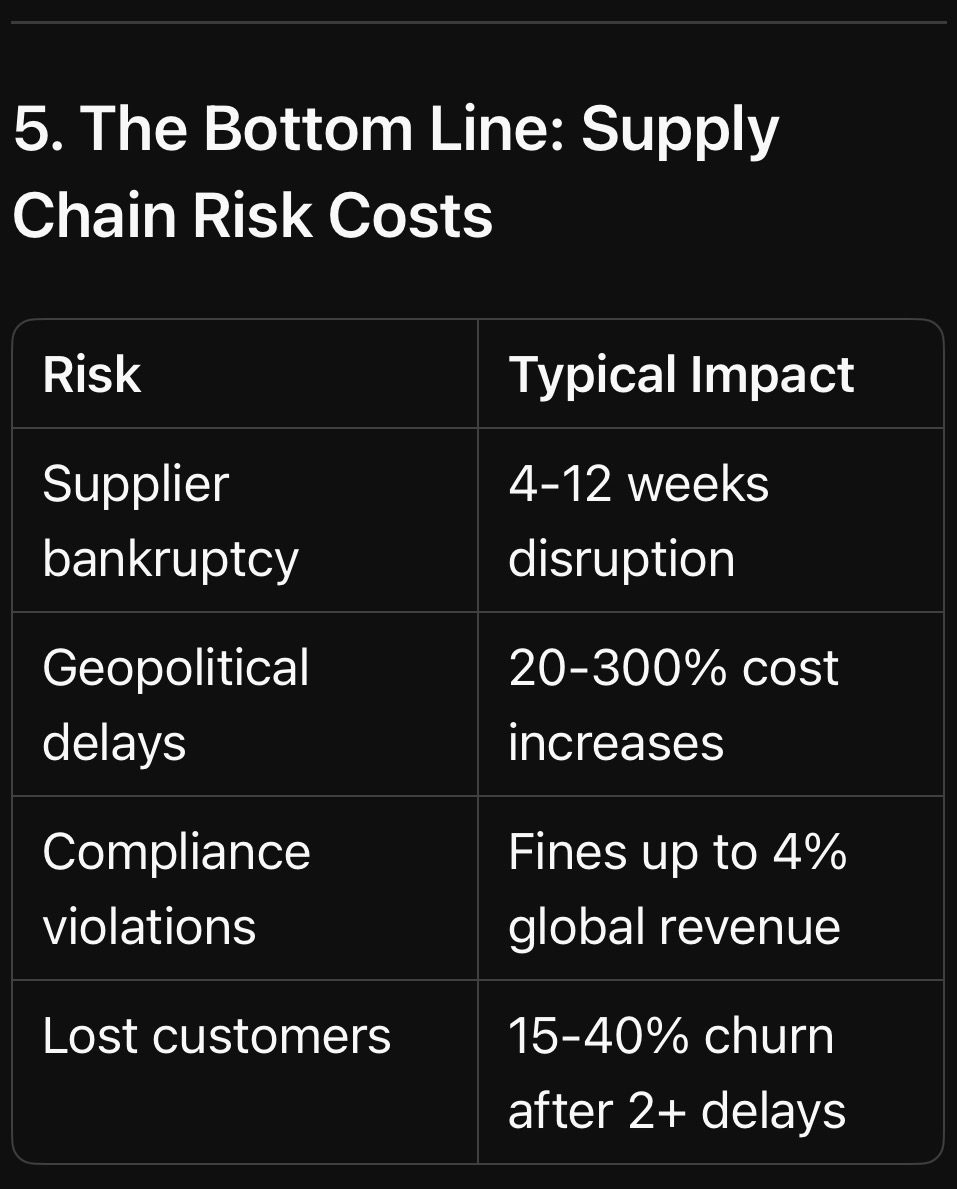
A single delayed shipment. One insolvent vendor. A geopolitical shockwave. Suddenly, your production line stops, customers revolt, and cash flow evaporates.
Key Insight: Supply chains have become the ultimate leverage point — for your competitors or your downfall.
—
More from BusinessRiskTV Business Experts Hub : How to Build an Unbreakable Supply Chain
We explore wartime-tested strategies, including:
The “3D Supplier Mapping” trick (used by Special Forces logisticians)
How to turn suppliers into partners (not adversaries)
When to nearshore/onshore without bankrupting yourself
Actionable Task: Identify one “critical” supplier you couldn’t operate without. How would you survive if they vanished tomorrow?
—
Chapter 8: Reputational Risks – When Trust Collapses Faster Than Your Share Price
Introduction: The 24-Hour Business Execution
A single tweet. One viral video. A disgruntled employee’s LinkedIn post. In today’s digital wildfire, your hard-earned reputation can evaporate before your crisis team finishes their first coffee.
The brutal reality:
87% of consumers will abandon a brand after a reputation crisis (YouGov)
It takes 4-7 years to build trust but just 4 bad days to destroy it (Edelman Trust Barometer)
65% of a company’s market value is tied to intangible assets like reputation (Ocean Tomo)
This isn’t about PR spin – it’s about preventing the preventable and surviving the unpredictable.
—
1. The Obvious Reputation Killers
A. Social Media Firestorms
Case Study: A restaurant manager’s racist comment caught on video → 300,000 angry tweets in 48 hours → permanent 40% revenue drop
Stat: Viral crises spread 20x faster than management can respond (MIT Sloan)
B. Executive Scandals
The P&G CEO Effect: A $375 billion company lost $40B in market cap in days after CEO’s inappropriate relationship surfaced
“No comment” = “We’re guilty” in public perception
Corporate-speak increases distrust by 41% (Edelman)
Legal-first responses often worsen the crisis
—
5. The Survival Playbook (Preview)
More from BusinessRiskTV Business Experts Hub we will explore modern reputation armour, including:
The “Dark Web Early Warning” system (catch crises before they explode)
Turning employees into reputation ambassadors
When to apologise vs. when to fight back
Actionable Task: Google “[Your Brand] + scandal” right now. What autocomplete suggestions appear?
—
Chapter 9: Climate Risks – The Existential Threat That’s Already Costing Your Business
Introduction: Your Business Is on the Frontlines of the Climate Crisis
Climate change isn’t a distant threat — it’s eroding profits, disrupting supply chains, and rewriting industry rules rightnow. In 2024 alone, climate disasters caused $2 trillion in global losses, with businesses absorbing the brunt through:
Operational shutdowns (e.g., factories flooded, data centres overheated
Soaring insurance premiums (up 300% in high-risk zones)
Regulatory penalties (e.g., non-compliance with carbon disclosure rules)
This chapter exposes the hidden costs of climate risks — and why most companies are dangerously unprepared.
—
1. The Two Faces of Climate Risk
A. Physical Risks: When Nature Attacks
1. Acute Disasters:
– Example: Hurricane Helene (2024) caused $225B in damages, disrupting microchip supplies by destroying a key quartz supplier .
– Stat: Severe weather events now cost businesses $560–610B yearly in asset losses .
2. Chronic Pressures:
– Heatwaves reduce worker productivity by 15–20% in sectors like construction and agriculture .
– Droughts forced a UK beverage company to halt production for 6 weeks due to water shortages .
B. Transition Risks: The Legal and Market Backlash
1. Policy Shocks:
– Carbon taxes could erase 20% of profits for high-emission firms by 2030 .
– Example: EU’s Carbon Border Tax added 10–20% costs for non-compliant imports .
2. Reputation Fallout:
– 75% of consumers boycott brands with poor sustainability records .
– Investor Flight: ESG-backlash aside, 90% of Fortune 500 firms now face shareholder climate lawsuits .
—
2. The Hidden Costs You’re Not Tracking
A. Supply Chain Domino Effects
Case Study: Floods in Thailand (2023) disrupted 40% of global hard drive production → tech firms lost $20B+
Stat: 73% of companies admit their supply chains are “highly vulnerable” to climate shocks .
B. Workforce Crises
Heat Stress: UK warehouses saw 30% more sick days during 2024’s record summer .
Talent Drain: 67% of Gen Z employees reject jobs at firms with weak climate policies .
C. Stranded Assets
Example: Oil companies wrote off $300B in reserves as “unburnable” due to net-zero policies.
Projection: 20% of commercial real estate will be uninsurable by 2030 .
Key Insight: Climate risks are profit killers — not just “ESG checkboxes.”
—
More from BusinessRiskTV Business Experts Hub : How to Fight Back
We will explore actionable climate resilience strategies, including:
The “3D Supply Chain Mapping” tactic (used by Special Forces logisticians)
How to turn carbon cuts into tax savings
AI-powered climate forecasting tools
Actionable Task: Run a 5-minute vulnerability scan: Which single climate threat (e.g., flood, heatwave) couldshut down your operations for 48 hours?
—
*Sources: World Economic Forum , Allianz , Beazley , Optera , EPA *
Chapter 10: 12 Actionable Solutions to Transform Risk into Competitive Advantage
Introduction: Risk Management Isn’t About Survival—It’s About Dominance
The most profitable companies don’t just avoid risks — they weaponise them. Toyota’s supply chain resilience made it the #1 automaker during the chip shortage. Amazon turned cybersecurity into a $35B AWS profit centre.
This chapter delivers 12 battle-tested solutions to stop losing money and start outpacing competitors.
—
Solution 1: The “Risk Ownership” Culture Hack
Problem: Employees see risk as “management’s problem.”
Fix:
– Tie 10-15% of bonuses to risk KPIs (e.g., near-miss reports, compliance audits)
– Example: A logistics firm reduced warehouse injuries by 62% after adding safety metrics to performance reviews
Action Step: This week, have each department identify one preventable risk they’ll now “own.”
—
Solution 2: The 5-Minute Daily Risk Radar
Problem: Monthly reports miss emerging threats.
Fix:
– Daily 5-minute standups on:
Top 3 operational vulnerabilities (e.g., server capacity, inventory levels)
Weak signals (e.g., supplier payment delays, social media complaints)
Case Study: A manufacturer caught a critical component shortage 3 weeks early by tracking supplier lead times daily
**Template:**
“`
[ ] Key risk #1 status
[ ] New threat detected
[ ] Mitigation action
“`
—
Solution 3: Cyber “Human Firewall” Training That Works
Problem: Boring compliance training fails.
Fix:
Monthly simulated phishing with “hacked” employees retaking interactive VR training
Result: One law firm reduced click-through rates from 28% to 3% in 6 months
Free Tool: Use CanIPhish for automated simulations
—
Solution 4: The 13-Week Cash Flow War Chest
Problem: Companies die from cash flow gaps, not lack of profit.
Fix:
1. Map all cash inflows/outflows week-by-week
2. Identify 3 survival levers (e.g., delayed payables, early collections)
3. Stress test with:
– 30% sales drop
– 60-day client payment delays
Example: A restaurant chain survived COVID by pre-negotiating 90-day rent deferrals before lockdowns
—
Solution 5: Supplier “X-Ray” Audits
Problem: 4th-tier suppliers can bankrupt you.
Fix:
– Demand blockchain-tracked materials for critical inputs
– Red Team Test: Randomly delay payments to check supplier liquidity
– Stat: Firms with mapped supply chains recover 9x faster from disruptions
—
Solution 6: AI-Powered Risk Forecasting
Toolkit:
Climate: Cervest (predict asset flooding)
Cyber: Darktrace (autonomous threat detection)
Financial: Simudyne (stress test scenarios)
ROI Example: A insurer cut claims by 22% using flood prediction AI
—
Solution 7: The “Pre-Mortem” Strategy Session
Problem: Executives ignore failure scenarios.
Fix: Before decisions:
1. Imagine the project has failed catastrophically
2. Brainstorm exactly why
3. Build safeguards
Case Study: Boeing’s 737 Max crashes could’ve been prevented by this method
—
Solution 8: Embedded Risk Officers
Innovation: Place risk champions in:
– R&D teams (kill flawed prototypes early)
– Sales (flag unrealistic client promises)
– Result: A pharma firm avoided $200M in FDA fines by catching compliance gaps during drug development
—
Solution 9: Dynamic Risk Scoring
Tool: Custom risk dashboards weighting:
– Probability (1–10)
– Impact (£)
– Velocity (how fast threat is growing)
– Example: A bank auto-prioritises risks scoring >£500k impact
—
Solution 10: The “Unthinkable” Drill
Annual Exercise: Simulate:
– CEO arrested
– HQ destroyed
– Key Result: BrewDog survived a ransomware attack because they’d practiced IT failovers quarterly
—
Solution 11: Turn Risk Into Revenue
Examples:
– Tesla sells carbon credits ($1.8B in 2023)
– Maersk’s green shipping premiums command 20% price hikes
Is M2 money supply in U.S. increasing and if so what does it mean to you?
Yes, the M2 money supply in the U.S. has increased over the last 6 months. The year-over-year increase in January 2025 was reported at 3.9%, and in February 2025 at 3.88%. This indicates that the amount of liquid money in the U.S. economy has been expanding.
Is the increase in M2 money supply significant?
The significance of the recent increase in the U.S. M2 money supply over the last six months is debatable and depends on the context and what you’re comparing it to. Here’s a breakdown of why:
Arguments for it being moderately significant:
Reversal of Contraction: This increase follows a period in 2023 and early 2024 where the M2 money supply actually contracted year-over-year. This period of contraction was the largest drop seen since the Great Depression. Therefore, the current growth represents a significant turnaround from that trend.
Year-over-Year Growth:The year-over-year growth rate in February 2025 was 3.88%. While not exceptionally high historically, it is positive and a considerable shift from the negative growth rates experienced in the previous year. This suggests a move away from monetary tightening.
Consistent Upward Trend: The month-over-month increases over the last six months indicate a sustained period of expansion in the amount of liquid money in the economy.
Potential Inflationary Pressure (with a lag): Historically, rapid increases in money supply have been linked to inflationary pressures, although the relationship isn’t always direct or immediate. Some economists believe that the recent growth could contribute to inflation in the future, although others note that the relationship is “long and variable.”
Arguments for it being less significant or within a moderate range:
Lower than Long-Term Average:The current year-over-year growth rate of 3.88% is still lower than the long-term average M2 growth rate in the U.S., which is around 6.86%. This suggests that while it’s growing, it’s not growing at an exceptionally rapid pace compared to historical norms.
Moderate Month-over-Month Increases: While positive, the month-over-month increases have been relatively moderate, generally under 0.5%. This indicates a gradual rather than a sudden surge in money supply.
Still Below Post-Pandemic Peaks: The M2 money supply reached very high levels during the COVID-19 pandemic. While the recent increase is notable, it hasn’t pushed M2 back to those peak growth rates.
Focus on Broader Economic Context: The significance of M2 growth needs to be considered alongside other economic indicators like GDP growth, inflation, unemployment, and interest rates. A moderate increase in M2 might be seen as supportive of economic growth if inflation remains under control.
The increase in the U.S. M2 money supply over the last six months is moderately significant primarily because it marks a clear end to a period of contraction and indicates a return to positive year-over-year growth. However, its significance is tempered by the fact that the growth rate is still below the historical average and the month-over-month increases have been gradual.
The global economy is a complex and interconnected system, with money supply playing a crucial role in its functioning. The amount of money in circulation, or the money supply, has a significant impact on various aspects of the economy, including inflation, interest rates, and economic growth. In this article, we will explore the benefits of a higher money supply for businesses and consumers, focusing on the effects of M2 money supply on the global economy.
What is M2 Money Supply?
M2 money supply is a broad measure of the money supply that includes all currency in circulation, checking account deposits, and most savings accounts. It is a key indicator of the overall liquidity in the economy and is closely monitored by central banks and economists.
The Benefits of a Higher M2 Money Supply
A higher M2 money supply can have several benefits for businesses and consumers. One of the primary benefits is that it can stimulate economic growth. When there is more money in circulation, people have more money to spend, which can lead to increased demand for goods and services. This increased demand can encourage businesses to invest in new equipment and hire more workers, leading to job creation and economic expansion.
Another benefit of a higher M2 money supply is that it can help to reduce unemployment. When businesses are expanding and hiring more workers, the unemployment rate tends to decline. This can lead to increased consumer confidence and spending, further stimulating the economy.
A higher M2 money supply can also help to reduce interest rates. When there is more money available in the economy, the cost of borrowing money tends to decrease. This can make it easier for businesses to invest in new projects and for consumers to make large purchases, such as homes or cars.
The Relationship Between M2 Money Supply, Cryptocurrencies, and the S&P 500
To better understand the impact of M2 money supply on the global economy, it is important to consider its relationship with other asset classes, such as cryptocurrencies and the S&P 500.
M2 Money Supply and Cryptocurrencies
Cryptocurrencies are a relatively new asset class that has gained significant popularity in recent years. They are digital or virtual currencies that use cryptography for security. Cryptocurrencies are not backed by any government or central bank, and their value is determined by supply and demand.
The relationship between M2 money supply and cryptocurrencies is complex and multifaceted. Some economists argue that a higher M2 money supply can lead to increased investment in cryptocurrencies. This is because investors may seek alternative assets to hedge against inflation, and cryptocurrencies can be seen as a safe haven asset.
However, others argue that the relationship between M2 money supply and cryptocurrencies is not as clear-cut. They point out that cryptocurrencies are still a relatively new and volatile asset class, and their value can be influenced by a variety of factors, including regulatory developments, technological advancements, and market sentiment.
M2 Money Supply and the S&P 500
The S&P 500 is a stock market index that tracks the performance of 500 of the largest companies in the United States. It is widely regarded as a benchmark for the overall health of the U.S. economy.
The relationship between M2 money supply and the S&P 500 is also complex. Historically, there has been a positive correlation between the two. This means that when M2 money supply increases, the S&P 500 tends to also increase. This is because a higher money supply can lead to increased economic growth and corporate profits, which can boost stock prices.
However, the relationship between M2 money supply and the S&P 500 is not always linear. Other factors, such as interest rates, inflation, and geopolitical events, can also influence stock prices.
Does an Increase in M2 Result in Increased Business Activity on the High Street?
The high street is a term used to refer to the main shopping streets in towns and cities. It is home to a variety of businesses, including retail stores, restaurants, and cafes.
The relationship between M2 money supply and business activity on the high street is complex and multifaceted. In theory, a higher M2 money supply should lead to increased consumer spending, which would benefit high street businesses. However, the reality is often more nuanced.
Several factors can influence the impact of M2 money supply on high street businesses. These include the overall economic climate, consumer confidence, and the availability of alternative shopping options, such as online shopping.
In addition, the specific mix of businesses on the high street can also play a role. Businesses that sell essential goods and services, such as groceries and pharmacies, may be less affected by fluctuations in M2 money supply than businesses that sell discretionary items, such as clothing and electronics.
How to Take Advantage of an Increase in M2 Money Supply to Grow Your SME Business
If you are an SME business owner, there are several things you can do to take advantage of an increase in M2 money supply.
Invest in Marketing and Advertising: When consumers have more money to spend, they are more likely to make discretionary purchases. Investing in marketing and advertising can help you reach new customers and increase sales.
Expand Your Product or Service Offerings: If you can identify new products or services that are in demand, you can expand your business and capture a larger share of the market.
Improve Your Customer Service: Providing excellent customer service can help you retain existing customers and attract new ones.
Invest in Technology: Technology can help you improve your efficiency and productivity, which can lead to increased profitability.
Offer Discounts and Promotions: Offering discounts and promotions can attract new customers and encourage existing customers to spend more.
Build Strong Relationships with Your Suppliers: Building strong relationships with your suppliers can help you secure better deals and ensure that you have the inventory you need to meet demand.
Monitor Your Cash Flow: It is important to monitor your cash flow carefully to ensure that you have the financial resources you need to grow your business.
Diversify Your Revenue Streams:Diversifying your revenue streams can help you reduce your risk and ensure that your business is more resilient to economic downturns.
By following these tips, you can take advantage of an increase in M2 money supply to grow your SME business.
The M2 money supply is a complex and important economic indicator. It can have a significant impact on businesses and consumers. By understanding the relationship between M2 money supply and other economic factors, you can make informed decisions about your business and financial planning.
What are implications for the rest of the world of U.S. increased M2 over last 6 months
The increase in the U.S. M2 money supply over the last six months has several potential implications for the rest of the world, though the exact magnitude and direction of these effects are complex and subject to ongoing debate among economists. Here are some key implications:
1. Potential for Increased Global Inflation:
Transmission of Inflation: A larger pool of U.S. dollars could, theoretically, lead to increased demand for goods and services globally. If global supply cannot keep pace with this increased demand, it could contribute to inflationary pressures in other countries. This is particularly relevant for countries with strong trade ties to the U.S. or those whose currencies are closely linked to the dollar.
Import Prices: If the increased M2 in the U.S. eventually leads to higher inflation there, it could translate to higher prices for U.S. exports, impacting import costs for other nations.
Commodity Prices: As the U.S. dollar is the dominant currency for pricing many global commodities, an increase in the dollar supply (even if not immediately inflationary in the U.S.) could, over time, contribute to higher commodity prices in local currencies worldwide.
2. Impact on Exchange Rates:
Dollar Depreciation (Potential): Generally, an increase in the supply of a currency can lead to its depreciation relative to other currencies. If the recent increase in M2 is perceived as inflationary or as a loosening of monetary policy in the long run, it could put downward pressure on the U.S. dollar’s exchange rate.
Impact on Export Competitiveness: A weaker dollar would make U.S. exports cheaper for buyers in other countries, potentially increasing U.S. export volumes and impacting the competitiveness of domestic industries in those countries. Conversely, U.S. imports would become more expensive.
Currency Fluctuations and Volatility: Significant changes in the U.S. M2 and the dollar’s value can contribute to volatility in global currency markets, creating uncertainty for businesses engaged in international trade and investment.
3. Effects on Global Financial Markets:
Capital Flows: An increase in U.S. M2 could influence global capital flows. If investors anticipate higher inflation or lower real returns in the U.S., they might seek investment opportunities in other markets, potentially leading to increased capital inflows in some countries and outflows in others.
Interest Rates: U.S. monetary policy, which can be influenced by M2 levels, has a significant impact on global interest rates. If the increase in M2 signals a more accommodative stance, it could keep U.S. interest rates lower for longer, potentially influencing borrowing costs and asset valuations globally. Conversely, if it’s seen as a precursor to future tightening to combat inflation, it could lead to expectations of higher global interest rates.
Asset Prices: Changes in U.S. liquidity and interest rates can affect asset prices worldwide, including stocks, bonds, and real estate. Increased U.S. M2 could initially support higher asset prices globally due to increased liquidity and investor sentiment, but this could be reversed if inflation concerns rise.
4. Implications for Developing Economies:
Debt Burden: Many developing countries hold debt denominated in U.S. dollars. A depreciation of the dollar could ease their debt burden in local currency terms. However, higher U.S. inflation leading to higher global interest rates could increase their debt servicing costs.
Trade Dependence: Developing economies heavily reliant on exports to the U.S. could see increased demand if the higher M2 translates to stronger U.S. consumer spending. However, they would also face higher import costs if U.S. inflation rises.
Financial Stability: Emerging markets can be particularly vulnerable to capital flow volatility caused by shifts in U.S. monetary policy and liquidity conditions.
5. Influence on Other Central Banks:
Policy Responses: Other central banks will closely monitor the U.S. M2 growth and its impact on inflation and exchange rates. They may need to adjust their own monetary policies in response to maintain price stability and manage their exchange rates. This could involve tightening or loosening monetary policy, intervening in currency markets, or adjusting capital controls.
Coordination Challenges: Divergent monetary policy responses among major central banks due to varying domestic conditions and interpretations of U.S. M2 growth could lead to increased global economic and financial instability.
Important Considerations:
Velocity of Money:The actual impact of increased M2 depends on the velocity of money – how quickly that money circulates through the economy. If the velocity remains low, the inflationary impact might be muted.
Global Economic Conditions: The effects of U.S. M2 growth will also be shaped by the overall state of the global economy, including growth rates, supply chain dynamics, and geopolitical factors.
Federal Reserve Actions: The U.S. Federal Reserve’s response to the increased M2 will be crucial. If the Fed takes steps to manage inflation expectations and potentially tighten monetary policy in the future, it could offset some of the inflationary pressures and exchange rate effects.
The recent increase in the U.S. M2 money supply has the potential to create ripple effects across the global economy, primarily through inflation, exchange rates, and financial market channels. However, the precise nature and magnitude of these implications are uncertain and will depend on a multitude of interacting factors and the responses of policymakers worldwide. Close monitoring of these developments is essential for businesses, investors, and governments globally.
M2 in U.S. is increasing. Increasing M2 is another factor that points to higher inflation in U.S. and worldwide. How central banks and commercial banks react to higher inflation is political as much as economics. Business leaders On The High Street should be reacting now to the change from 2024 where there was an enormous contraction in money supply to a lot more money sloshing around worldwide economy and this fact’s impact on the economy and their business in particular.
#FutureOfTrade: article for those interested in the evolving landscape of global trade and the strategic shifts required for success in business in the UK
The world is changing. Fast. Economic power is shifting, and the old certainties are dissolving. For decades, the UK’s economic orbit has been firmly fixed on Europe and the United States. But a new reality is emerging. The fastest-growing economies are no longer in the West. They’re in the Global South. This seismic shift presents both a challenge and a massive opportunity for UK businesses. So, the question is: should the UK double down on traditional markets, or boldly chart a new course towards the dynamic economies of the developing world? I believe the answer is clear. The future of UK prosperity lies in embracing the Global South. This article will explore why, offering 15 compelling reasons for UK business leaders to forge trade links with these emerging markets, and suggesting six concrete steps for making that strategic shift a reality.
Shifting Sands: Why UK Businesses Must Embrace the Global South
The global economy is no longer a static picture. It’s a dynamic, ever-evolving landscape. We’re witnessing a significant power shift, with economic growth increasingly concentrated in the Global South. This isn’t just a fleeting trend. It’s a fundamental realignment of the global economic order. For UK businesses, clinging to the familiar shores of Europe and North America while ignoring the burgeoning markets of Africa, Asia, and Latin America would be a grave mistake. It’s like trying to navigate the high seas with an outdated map. You might know where you’ve been, but you’ll be lost when it comes to where you need to go.
The sheer scale of this transformation is staggering. Consider this: by 2030, it’s projected that the combined GDP of emerging markets will surpass that of developed economies. That’s a massive shift in economic gravity. And while China’s growth has been a major story for the past two decades, many other dynamic economies are rapidly rising in prominence. Think of India, with its huge and youthful population. Think of the vibrant economies of Southeast Asia. Think of the potential waiting to be unlocked in Africa. These are the markets of the future, and UK businesses need to be a part of this exciting growth story.
Now, I understand the comfort of the familiar. We’ve built strong relationships with our European and American partners over decades. But in the face of such a dramatic global shift, clinging to the status quo is a recipe for decline. We need to be bold. We need to be strategic. We need to look beyond our traditional horizons and embrace the opportunities that the Global South offers.
15 Reasons UK Business Leaders Should Develop Trade Links with Countries in the Global South
Let’s dive into the specifics. Here are 15 compelling reasons why UK business leaders should be prioritising trade links with countries in the Global South:
Higher Growth Potential: As mentioned, many countries in the Global South are experiencing significantly higher economic growth rates than developed economies. This translates to greater opportunities for businesses looking to expand their markets and increase their revenue.
Untapped Markets: Many markets in the Global South are relatively untapped, offering UK businesses a first-mover advantage. This can lead to significant market share and brand recognition.
Demographic Dividend: Many developing countries have young and growing populations, creating a large pool of potential consumers and a dynamic workforce.
Diversification: Expanding into new markets helps diversify a business’s revenue streams and reduces reliance on any single region. This makes the business more resilient to economic shocks.
Access to Resources: Many countries in the Global South are rich in natural resources, providing UK businesses with access to essential raw materials and commodities.
Innovation and Technology: While sometimes overlooked, innovation is thriving in many developing economies. Partnerships with local businesses can give UK companies access to cutting-edge technologies and new ideas.
Cost Advantages: In some cases, operating costs in developing countries can be lower than in developed economies, offering businesses a competitive advantage.
New Partnerships:Building relationships with businesses in the Global South can open doors to new partnerships, joint ventures, and investment opportunities.
Global Brand Building: Expanding into new markets helps build a global brand presence and enhances a company’s reputation.
Talent Acquisition: Developing countries have a wealth of talented individuals, offering UK businesses access to a diverse and skilled workforce.
Addressing Global Challenges:Collaborating with businesses in the Global South can help address global challenges such as poverty, inequality, and climate change, creating positive social impact.
Building a Sustainable Future: Investing in sustainable development in developing countries can create long-term economic opportunities and contribute to a more equitable and prosperous world.
Geopolitical Influence: Building strong economic ties with countries in the Global South can enhance the UK’s geopolitical influence and strengthen its position on the world stage.
First-Mover Advantage: Businesses that establish trade links with developing countries early on can gain a significant competitive advantage over their rivals.
Future-Proofing Your Business: By embracing the Global South, UK businesses can future-proof their operations and position themselves for long-term success in a rapidly changing world.
6 Ways UK Business Leaders in 2025 Should Develop a Strategic Shift to More Trade with the Global South
Now, how do we make this happen? Here are six actionable steps UK business leaders can take to develop a strategic shift towards greater engagement with the Global South:
Conduct Thorough Market Research: Don’t jump in blindly. Invest in detailed market research to identify the most promising opportunities and understand the specific needs and preferences of consumers in different regions. This includes understanding cultural nuances, regulatory environments, and local business practices.
Build Local Partnerships: Don’t try to go it alone. Forge strong partnerships with local businesses that have established networks and understand the local market. These partnerships can be invaluable for navigating the complexities of doing business in developing countries.
Adapt Your Products and Services: Don’t assume that what works in the UK will work elsewhere. Be prepared to adapt your products and services to meet the specific needs and preferences of local consumers. This might involve modifying product features, packaging, or marketing messages.
Embrace Digital Technologies: Leverage digital technologies to connect with customers and partners in the Global South. E-commerce, social media, and other digital tools can be powerful enablers of trade and communication.
Invest in Cultural Sensitivity Training: Don’t underestimate the importance of cultural sensitivity. Provide your employees with training on the cultural norms and business etiquette of the countries you’re targeting. This will help build trust and foster strong relationships.
Develop a Long-Term Strategy: Don’t expect overnight success. Building strong trade links with developing countries takes time and effort. Develop a long-term strategy that outlines your goals, target markets, and approach to engagement. Be patient, persistent, and committed to building lasting relationships.
The shift towards the Global South is not just an economic imperative. It’s a strategic necessity. It’s about securing the UK’s future prosperity in a world where economic power is shifting. It’s about building new partnerships, unlocking new opportunities, and embracing the dynamism of the developing world. It’s about recognising that the future is not in the West, but in the Global South. For UK businesses that are willing to embrace this new reality, the rewards will be substantial. Those who cling to the past risk being left behind. The choice is ours. Let’s choose the future.
Get help to protect and grow your business faster more affordably
UK businesses expanding trade Global South opportunities 2025 : This targets businesses actively seeking expansion.
Strategic shift Global South trade for UK companies after Brexit
Best emerging markets Global South for UK export businesses : This focuses on export opportunities and targets businesses looking for specific market information – actionable risk management advice.
How UK SMEs can benefit from trading with developing countries : This targets small and medium-sized enterprises (SMEs).
Future of UK trade Global South partnership strategies for long-term growth : This appeals to businesses with a long-term vision and emphasises partnership strategies – collaborative approaches.
#GlobalSouthTrade
#UKEmergingMarkets
#PostBrexitTrade
#SMEGlobalGrowth
#FutureOfTrade
UK businesses expanding trade Global South opportunities 2025