Which 3 Nassim Taleb Books Should Directors Read for Tail Risk & Operational Resilience in 2026?

How do directors, project managers & strategists navigate systemic uncertainty? BusinessRiskTV reviews Taleb’s 3 books with UK ONS stats & practical tail risk steps.

BusinessRiskTV Business Risk Management Club recommends these 3 books to help the reader make better decisions on Operational Resilience & Tail Risk Strategy.

That single sentence encapsulates why the following review exists. The scale of the problem is not theoretical. The Office for National Statistics reported that 40% of UK trading businesses with 10 or more employees cited economic uncertainty as the most significant challenge impacting turnover in early April 2026—the highest proportion since the question was introduced in April 2022. Government analysis of operational disruption across UK sectors shows that while typical incidents cost between 0.2% and 4.6% of annual turnover, tail events can dominate total losses and threaten business continuity entirely. Cyber-attacks alone cost UK businesses £3.7 billion in litigation over the past year, with shareholder lawsuits accounting for nearly a third of that total. Against this backdrop, Nassim Nicholas Taleb’s Incerto trilogy—Fooled by Randomness, The Black Swan, and Antifragile—provides the conceptual infrastructure that directors, project managers, and strategists need to navigate systemic uncertainties and cognitive bias in decision-making.‌

What Makes Nassim Nicholas Taleb’s Incerto Trilogy Essential Risk & Decision-Making Literature for Operational Resilience & Tail Risk Strategy?

Taleb’s Incerto trilogy is essential risk and decision-making literature for operational resilience and tail risk strategy because it systematically dismantles the illusions that lead organisations to underestimate rare, high-impact events and overestimate their ability to predict and control complex systems. The three books form a coherent progression: Fooled by Randomness (2001) exposes how humans mistake luck for skill; The Black Swan (2007) reveals how rare, unpredictable events shape history and markets; Antifragile (2012) offers a framework for building systems that benefit from disorder.

Why This Matters for Directors, Project Managers & Strategists:

  • Directors face board-level decisions where governance failures linked to cognitive bias carry escalating legal and financial consequences. UK boards are already experiencing “quiet distress” as prolonged financial strain and delayed decisions create D&O exposure earlier in the risk cycle.
  • Project managers operate at the intersection of uncertainty and delivery, often relying on linear projections and optimistic timelines that fail catastrophically when tail events hit. Research shows that organisations with structured decision trackers score more than 20 percentage points higher on early-warning indicator tracking and bias exploration than those without.
  • Strategists build models that assume a stable future, yet the ONS Business Insights survey consistently shows economic uncertainty dominating business challenges month after month.‌
    Each book serves a distinct function in the operational resilience toolkit. Together, they constitute a complete curriculum in probabilistic thinking, tail risk awareness, and adaptive system design.

What Is the Core Argument of Fooled by Randomness, and How Does It Apply to Business Decision-Making?

The core argument of Fooled by Randomness: The Hidden Role of Chance in Life and in the Markets is that humans systematically confuse randomness with causality, attributing success to skill and failure to controllable factors, thereby creating brittle decision-making frameworks that collapse when randomness reasserts itself. Taleb demonstrates that much of what passes for expertise in finance, management, and strategy is indistinguishable from luck dressed in the language of analysis.

Why This Matters Practically:

  • Distinguish signal from noise in performance data. Taleb argues that short-term results are dominated by variance, not skill. When evaluating business unit performance or project outcomes, directors should demand longer time horizons and statistical significance testing before drawing conclusions. UK businesses reporting turnover decreases (27% in April 2026) and increases (15% in July) often attribute these swings to strategy or market conditions when random fluctuation may be the dominant driver.‌
  • Identify survivorship bias in case studies. Business literature is filled with success stories of companies that “did everything right.” Taleb’s point is that we never see the graveyard of companies that did the same things and failed due to bad luck. Strategy teams should actively seek out failure cases and control groups.
  • Resist the narrative fallacy in post-mortems. After any project, there is enormous pressure to construct a coherent story explaining outcomes. Taleb warns this narrative impulse prevents genuine learning.

Business Application:

Project managers should implement decision journals that record expectations before outcomes are known, creating a feedback loop that reveals whether success was skill or circumstance. Directors should push for probabilistic language in board papers—”we assess a 60% likelihood” rather than “we are confident”—forcing explicit recognition of uncertainty. Strategists should stress-test strategic plans against scenarios where random negative events cluster, rather than assuming they distribute evenly across time.

What Is the Central Thesis of The Black Swan, and Which Businesses Are Most Vulnerable to Its Implications?

The central thesis of The Black Swan: The Impact of the Highly Improbable is that rare, unpredictable, high-consequence events—Black Swans—dominate outcomes in complex systems, yet our psychological and institutional frameworks are systematically blind to their possibility, leaving businesses dangerously exposed to catastrophic surprise. Taleb identifies the “triplet of opacity”: the illusion of understanding, the retrospective distortion of events, and the overvaluation of factual information.

Which Businesses Are Most Vulnerable:

  • Financial services firms face existential Black Swan exposure. Bank of England research shows 82% of UK banks, insurers and asset managers now cite cyber attacks as a top-five risk to the financial system, up ten percentage points from 2024. A meaningful share of large financial institutions face a roughly 10% annual probability of losing 10% or more of annual profit to a single cyber event.
  • Supply chain-dependent manufacturers and retailers are directly exposed to geopolitical Black Swans. In April 2026, 47% of UK businesses experiencing global supply chain disruption cited the conflict in the Middle East as the reason—up 34 percentage points from February.‌
  • Energy-intensive businesses face compounding tail risks from price volatility and geopolitical disruption. 60% of UK businesses reported concern about energy prices in early May 2026, with accommodation and food service businesses reaching 86% concern.‌
  • Technology and digital businesses are exposed through cyber, regulatory, and concentration risk. The PRA’s 2026 operational resilience policy statement explicitly addresses “rising threats to operational resilience at firms and their growing reliance on externally supplied services”.‌

When to Use The Black Swan Learning Points:

Business Application:

Directors should establish dedicated tail risk committees that meet independently of standard risk reviews, focusing exclusively on low-probability, high-impact scenarios. Project managers should build “kill criteria” into major projects—pre-defined conditions under which the project is stopped—rather than assuming continuation. Strategists should model scenarios where multiple Black Swans occur simultaneously, recognising that disruptions cluster rather than distribute evenly.

What Does Antifragile Teach About Building Organisations That Improve Under Stress, and How Can This Be Implemented?

Antifragile: Things That Gain From Disorder teaches that some systems are not merely robust (resistant to shocks) or resilient (recovering after shocks), but antifragile—they actually improve, strengthen, and grow when exposed to volatility, randomness, and stressors. Taleb argues this property is the highest form of adaptation available to organisations, and it can be deliberately engineered through structural choices, incentive design, and optionality.

Key Antifragile Principles for Business:

  • Barbell strategy: Combine extreme conservatism in core operations with aggressive, small-scale experimentation in growth areas. 75% of grant-funded UK charities use formal risk tools compared to 35% of non-grant-funded organisations, suggesting structured approaches enable greater risk capacity when combined with appropriate funding.
  • Optionality over prediction: Rather than forecasting the future, build portfolios of options that benefit from multiple possible outcomes. This directly addresses the observation that economic uncertainty has been the most reported challenge affecting business turnover since October 2022.
  • Skin in the game: Decision-makers must bear the consequences of their decisions. HM Treasury’s 2026 guidance to accounting officers frames value for money as a “balanced judgement of strategic alignment, long-term resilience, and risk,” moving beyond simple cost minimisation.
  • Redundancy as investment: Duplicate systems, diversified suppliers, and cross-trained teams are not waste—they are the raw material of antifragility.

When to Apply Antifragile Learning Points:

  • During organisational design—to build structures that benefit from uncertainty rather than merely surviving it.
  • During supply chain strategy—to move from just-in-time efficiency to diversified, optionality-rich sourcing.
  • During technology investment—to prioritise systems that learn from attacks and failures rather than merely resist them.
  • During talent development—to cultivate teams comfortable with volatility and skilled at rapid adaptation.

Business Application:

Operations directors should conduct “stress tests with benefit”—scenarios where the organisation not only survives disruption but emerges stronger because competitors are weakened. For example, a manufacturer with diversified suppliers can gain market share when single-source competitors face disruption. Project managers should build rapid prototyping and learning loops into delivery schedules, treating small failures as information rather than stigma. Strategists should allocate a portion of capital to small, high-optionality bets that could pay off massively in Black Swan scenarios, while simultaneously reducing exposure to ruinous tail risks.

Which Businesses Will Benefit Most from Taleb’s Frameworks, and Where in the World Are They Likely Operating?

The businesses that will benefit most from Taleb’s frameworks are those operating in high-uncertainty, high-interconnection, and high-consequence environments—particularly in the UK, Europe, North America, and Asia-Pacific where regulatory pressure, geopolitical fragmentation, and technological disruption intersect.

Sector-by-Sector Analysis:

  • Financial services in London, New York, Singapore, and Frankfurt face the most acute combination of regulatory scrutiny, cyber exposure, and tail risk concentration. The PRA’s PS7/26 operational resilience policy, effective from 2026, requires firms to report operational incidents and material third-party arrangements with significantly reduced burden but enhanced oversight. UK financial services compliance costs now exceed £33.9 billion annually, representing roughly 13% of average operating costs.‌
  • Manufacturing and logistics across the UK, Germany, Netherlands, and key Asian hubs are directly exposed to supply chain Black Swans. The ONS reported 7% of UK businesses experiencing global supply chain disruption in April 2026, with nearly half citing Middle East conflict.‌
  • Energy and utilities in the UK, Norway, Gulf states, and Australia face compounded tail risks from price volatility, geopolitical disruption, and transition uncertainty. 28% of UK businesses cited energy prices as a reason for considering raising prices in June 2026.‌
  • Technology and digital platform businesses globally face cyber Black Swans, regulatory tail risks, and concentration risk. The Bank of England’s 2026 H1 Systemic Risk Survey found 82% of financial institutions citing cyber attacks as a top-five systemic risk.‌
  • Healthcare and pharmaceutical supply chains across Europe, North America, and Asia are exposed to pandemic Black Swans, regulatory disruption, and geopolitical supply chain risk.
  • Professional services firms advising on risk, strategy, and resilience are both beneficiaries (demand for their services grows) and exposed to reputational tail risks if they fail to apply these frameworks themselves.

Geographic Concentration:

  • United Kingdom: Highest regulatory intensity for operational resilience, with FCA/PRA rules now in “steady-state” from 2026, enhanced regulatory powers, and cost recovery provisions.
  • European Union: DORA (Digital Operational Resilience Act) in force across Europe, aligning with UK approaches but creating additional compliance complexity for cross-border firms.
  • United States: Less prescriptive regulation but higher litigation and shareholder activism risk, particularly around cyber governance failures.
  • Asia-Pacific: Rapid economic growth combined with geopolitical tension, supply chain concentration, and varying regulatory maturity creates a high-Black-Swan environment.
  • Middle East and Africa: Geopolitical disruption, energy price volatility, and infrastructure risk create compounding tail exposure.

How Should Organisations Integrate Taleb’s Key Learning Points into Decision-Making to Boost Performance and Reduce Risk Events Derailing Business Objectives?

Organisations should integrate Taleb’s key learning points by embedding probabilistic thinking, tail risk assessment, and antifragile design principles into the governance, project management, and strategy functions at the point of decision, not as an afterthought. The evidence suggests this is not optional: UK business confidence dropped to a net figure of -76 in March 2026, compared to -63 in February, according to Institute of Directors research. Fewer businesses were set up in Q1 2026 than in any comparable period on record. The organisations that survive and thrive will be those that internalise Taleb’s lessons before the next Black Swan arrives.

Board-Level Integration:

  • Establish a Tail Risk Committee reporting directly to the board, separate from the standard audit and risk committee, with a mandate to challenge assumptions of normality and identify ruin exposure.
  • Require probabilistic decision papers: every significant capital allocation or strategic decision must include explicit probability assessments, not point forecasts.
  • Implement decision journals that record expectations, rationale, and confidence levels before outcomes are known, reviewed quarterly to identify systematic biases.

Project Management Integration:

  • Build kill criteria into every major project: pre-defined conditions under which the project is terminated, removing sunk-cost bias from continuation decisions.
  • Apply barbell resource allocation: commit 80-90% of resources to high-confidence, low-variance delivery, and 10-20% to experimental, high-optionality initiatives that could benefit from disorder.
  • Conduct pre-mortems at project initiation: assume the project has failed catastrophically and work backwards to identify causes.

Strategy Integration:

  • Replace single-scenario planning with multiple scenarios including Black Swan scenarios where multiple disruptions compound.
  • Develop antifragile supply chains with diversified sourcing, redundancy, and optionality—accepting higher baseline costs as insurance against tail events.
  • Invest in optionality: maintain cash reserves, flexible contracts, and strategic options that can be exercised when volatility creates opportunity.

Operational Resilience Integration:

  • Align with regulatory requirements proactively: the PRA’s operational resilience framework requires firms to remain within impact tolerances for important business services under severe but plausible disruption scenarios.
  • Conduct regular stress tests that include cyber, geopolitical, and supply chain scenarios simultaneously, recognising that disruptions cluster.
  • Measure resilience value not just as cost avoidance but as competitive advantage: government analysis shows that increased resilience reduces both the likelihood of severe outcomes and the scale of losses when disruption occurs.‌

When to Apply These Frameworks:

  • Annually during strategy and budget cycles: full Black Swan scenario review and antifragile portfolio assessment.
  • Quarterly during board risk reviews: tail risk exposure review and decision journal analysis.
  • Monthly during project reviews: kill criteria assessment and pre-mortem updates.
  • Continuously through operational monitoring: early-warning indicators and antifragile capacity metrics.
  • Post-incident after any disruption: structured learning review applying Fooled by Randomness lessons about attribution.

Why Are These Books Particularly Relevant for Operational Resilience & Tail Risk Strategy in September 2026?

These books are particularly relevant in September 2026 because the operating environment has become precisely the kind of high-volatility, high-interconnection, high-consequence system that Taleb’s frameworks were designed to address. The ONS Business Insights survey for April 2026 showed economic uncertainty at 40% for larger businesses—the highest proportion since the question was introduced. Global supply chain disruption reached 9% in March 2026, the highest since December 2022. The PRA’s operational resilience rules are now in full effect, with “steady-state” expectations and enhanced regulatory powers to demand information, direct remediation, and recover supervisory costs. Bank of England analysis confirms that “average impacts are not representative of overall risk exposure” and that “tail events can dominate total losses and can threaten business continuity”.‌‌

Taleb’s trilogy provides the intellectual architecture to navigate this environment. Fooled by Randomness teaches the discipline of statistical scepticism. The Black Swan reveals the structural blind spots that make organisations vulnerable to rare events. Antifragile offers the design principles to build systems that improve under stress. Together, they constitute a complete risk literacy curriculum for directors, project managers, and strategists who need to make decisions when the future refuses to behave as forecast.

The value proposition is not merely defensive. Organisations that internalise these lessons will identify opportunities that competitors miss—in supply chain restructuring, in optionality-rich investment strategies, in resilient operational models that become competitive advantages when disruption hits. The question is not whether the next Black Swan will arrive, but whether your organisation will be fooled by randomness when it does.

#OperationalResilience #TailRiskStrategy

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about growing your business faster with BusinessRiskTV Business Risk Management Club

Subscribe for free business risk management ideas risk reviews and business discounts to reduce your business cost of being in business

Connect with BusinessRiskTV for free business risk management tips

Read more business risk management articles and view videos for free

Connect with BusinessRiskTV for free alerts to new business risk management articles and videos 

Most “resilient” UK businesses are just lucky. And 40% of larger UK firms just admitted economic uncertainty is beating them.

That’s not a vibe. That’s the ONS Business Insights survey, April 2026: 40% of UK trading businesses with 10+ employees cited economic uncertainty as the top challenge hitting turnover — the highest since the question began in April 2022.

So here’s the uncomfortable question: if your risk register still assumes the future looks like the last 5 years, what exactly are you protecting?

BusinessRiskTV Business Risk Management Club recommends these books to help the reader make better decisions on Operational Resilience & Tail Risk Strategy.

Keep reading — because the third book is the one that changes how you allocate capital.

There are 3 books that do more for operational resilience than most 40-page board packs:

1. Fooled by Randomness — Nassim Nicholas Taleb
It asks: how much of your “performance” is skill, and how much is luck?

If UK businesses swing from 27% reporting turnover decreases to 15% reporting increases in a matter of months, how much of that is strategy — and how much is noise?
Most post-mortems invent a story. Taleb shows you why that story is usually wrong.

2. The Black Swan — Nassim Nicholas Taleb
It asks: what rare event would wipe out the plan?

82% of UK banks, insurers and asset managers now cite cyber attacks as a top-five risk to the financial system, per Bank of England H1 2026 research.
47% of UK businesses hit by global supply chain disruption in April 2026 blamed the Middle East conflict — up 34 percentage points from February.
Cyber-attacks cost UK businesses £3.7bn in litigation over the past year.
That’s not a tail risk. That’s a board-level blind spot.

Wait — here’s the counterintuitive part.

3. Antifragile — Nassim Nicholas Taleb
It asks: what gets stronger when stressed?
Not “robust.” Not “resilient.” Antifragile.

The PRA’s 2026 operational resilience policy puts firms in “steady-state” with enhanced powers to demand information, direct remediation and recover supervisory costs.
UK financial services compliance costs now exceed £33.9bn a year — roughly 13% of average operating costs.
If you’re spending that much on defence, Taleb’s barbell strategy is the difference between surviving volatility and profiting from it.

Here’s the 3-question test most teams never run:

  1. What would actually ruin us — not just hurt quarterly earnings?
  2. What looks like skill but is statistically indistinguishable from luck?
  3. What part of the business gets stronger when suppliers fail, cyber hits, or energy spikes?

If you can’t answer those three with specific numbers and named owners, you don’t have a tail risk strategy. You have a hope strategy!

Directors, project managers and strategists: this is why these books matter now. Not in theory. In capital allocation, kill criteria, supplier diversification, decision journals and pre-mortems.

Email editor@businessrisktv.com with the subject line TALEB 3 and tell me which of the three books your board needs to read first.

Featured Books

Incerto Series 1-3 Books Collection Set by Nassim Nicholas Taleb (Fooled by Randomness, The Black Swan & Antifragile)

As an Amazon Associate I earn from qualifying purchases.

Which 3 Nassim Taleb Books Should Directors Read for Tail Risk & Operational Resilience in 2026?
Bank of England Repo Record: A Red Flag for the UK Economy? | Business Risk TV

The Bank of England’s recent record £87.15 billion repo allotment, a tool used to provide liquidity to banks as the central bank reduces its bond holdings, could signal underlying stress in the UK banking sector. This growing reliance on the central bank for funds raises a red flag for the financial stability and economic safety of the UK. Discover what this means for the wider economy and learn six crucial risk management strategies every business leader should implement now to protect and grow their enterprise more resiliently in an uncertain economic climate.

Bank of England Allots Record £87.15 Billion in Repo Operation: What It Means for UK Business Risk

The Bank of England’s Record Repo Allotment: A Warning for UK Business? 🚨

The Bank of England recently allotted a record £87.15 billion in a short-term repo operation, a move that provides a substantial injection of liquidity into the UK’s banking system. While this may seem like a routine technical adjustment by the central bank, the increasing reliance on these operations could be a significant red flag for the safety of the UK’s financial system and wider economy.


What Is a Repo Operation and Why Is This a Red Flag?

A repo (repurchase agreement) is essentially a short-term loan. The Bank of England lends money to commercial banks and in return, the banks provide high-quality assets (like government bonds) as collateral. The Bank’s increasing use of this tool is directly linked to its Quantitative Tightening (QT) programme, which involves selling off the government bonds it bought during the era of Quantitative Easing (QE). The purpose of these repo operations is to prevent a potential liquidity squeeze in the financial system as the central bank reduces its balance sheet.

The record allotment is a red flag for a few key reasons:

  • Growing Illiquidity: The fact that banks are demanding a record amount of funds from the central bank suggests they may be struggling to find liquidity elsewhere in the market. This could indicate underlying stress in the banking sector and a reluctance among banks to lend to each other.
  • Systemic Risk: This reliance on the Bank of England for funding could be a sign of increased systemic risk. If a major bank were to face a sudden liquidity crisis, the central bank would be its lender of last resort. The increasing size of these operations shows the potential scale of that reliance.
  • Uncertainty and Instability: A record-breaking allotment, particularly one that exceeds a recent record, creates a narrative of growing instability. This can erode confidence in the banking system and the wider economy, making businesses and investors more hesitant to spend and invest. This uncertainty trickles down to businesses and consumers, affecting everything from investment decisions to household spending.

6 Risk Management Measures for Businesses

In an environment of economic uncertainty, business leaders must be proactive to protect their organisations. Here are six essential risk management measures to enhance resilience:

  1. Strengthen Cash Flow and Liquidity: Cash is king, especially in a downturn. Focus on optimising your working capital by accelerating accounts receivable, negotiating longer payment terms with suppliers, and maintaining a healthy cash reserve. Create detailed cash flow forecasts to anticipate potential shortfalls and manage expenses.
  2. Diversify Revenue Streams and Supply Chains: Over-reliance on a single product, service, customer, or supplier is a major vulnerability. Actively seek new markets, customer segments, and partnerships. For your supply chain, identify alternative vendors and consider strategies like near-shoring or holding a small buffer of critical inventory to mitigate potential disruptions.
  3. Conduct Scenario Planning and Stress Testing: Don’t wait for a crisis to hit. Create multiple worst-case, best-case, and most-likely scenarios for your business. For each scenario, outline the potential impact on revenue, costs, and profit. This will help you identify weak points and develop contingency plans in advance.
  4. Manage Debt and Capital Expenditure Wisely: During uncertain times, it is crucial to avoid taking on excessive debt. Evaluate all major capital expenditure projects. Postpone or cancel non-essential investments that don’t directly contribute to immediate revenue or operational efficiency.
  5. Review and Optimise Operational Costs: Take a hard look at all business expenses. Eliminate unnecessary costs without sacrificing the quality of your product or service. This could involve renegotiating contracts, leveraging technology for greater efficiency, or consolidating services. The goal is to create a leaner, more resilient cost structure.
  6. Prioritise Customer and Employee Retention: In a tough economic climate, your most valuable assets are your loyal customers and skilled employees. Focus on providing exceptional customer service to retain your existing client base. For employees, transparent communication and a supportive work environment can boost morale and productivity, reducing the risk of losing key talent.

#UKBusinessRisk #BoE #RepoOperation #BusinessRiskTV #RiskManagement

Get help to protect and grow your business resiliently with BusinessRiskTV

Find out more about business protection and growth in UK

Subscribe for free business risk management ideas reviews and cost reduction tips

Connect with us for free business risk management tips

Why the Bank of England’s Record Repo Allotment Is a Red Flag

The Bank of England’s record-breaking repo allotment is a significant red flag because it points to potential underlying stress and growing liquidity issues within the UK banking system. While repo operations are a standard tool for central banks to manage monetary policy, the increasing size of these allotments, especially in the context of the central bank’s quantitative tightening (QT) programme, reveals a deeper problem.

  • Growing Illiquidity and Inter-bank Distrust: The primary role of a central bank’s repo operation is to provide liquidity. A record amount being requested by commercial banks suggests they are struggling to secure the funds they need from each other. In a healthy banking system, banks would lend to one another in the inter-bank market. The fact that they are turning to the Bank of England in such high volumes could indicate a breakdown of trust between financial institutions, which is a classic symptom of a stressed system.
  • Systemic Risk: The increasing reliance on the central bank for funding raises concerns about systemic risk. Systemic risk is the risk of a collapse of an entire financial system due to the failure of one or more institutions. If a significant portion of the banking sector is dependent on the Bank of England for liquidity, a sudden shock or disruption could have a cascading effect across the entire system. This over-reliance makes the financial system less resilient and more vulnerable to unforeseen events.
  • Uncertainty and Economic Instability: A record repo allotment creates a sense of uncertainty and instability in the market. The public and investors may interpret this as a signal that the banking system is not as robust as it appears. This loss of confidence can have a tangible impact on the wider economy. It can lead to a tightening of lending standards, making it harder for businesses and households to access credit, and it can also deter investment, ultimately slowing down economic growth. The large allotment, therefore, isn’t just a technical exercise; it’s a barometer of growing financial vulnerability in the UK.

Read more free business risk management articles and view videos

Connect with us for free business risk management analysis alerts

6 Essential Business Risk Management Measures for UK Business Leaders

In today’s complex and uncertain economic environment, proactive business risk management is no longer an option—it’s a necessity. UK business leaders must move beyond a reactive approach and build genuine resilience into the core of their operations. Here are six essential measures to take action on now.

1. Strengthen Cash Flow and Liquidity

Cash is the lifeblood of any business. In times of economic instability, a strong cash position can be the difference between survival and failure.

  • Optimise working capital: Focus on accelerating accounts receivable by offering incentives for early payment or enforcing stricter payment terms. At the same time, negotiate more favourable payment terms with your suppliers to extend your accounts payable.
  • Create robust cash flow forecasts: Use financial modelling and scenario planning to predict potential cash shortfalls. This will help you anticipate problems and give you time to secure financing or make cost adjustments before a crisis hits.
  • Maintain a cash reserve: Aim to build a buffer of cash sufficient to cover at least three to six months of operating expenses. This reserve acts as a critical safety net against unexpected disruptions.

2. Diversify Revenue Streams and Supply Chains

Over-reliance on a single customer, product, or supplier is a major vulnerability. Diversification builds a more robust and flexible business model.

3. Conduct Scenario Planning and Stress Testing

Don’t wait for a crisis to expose your weaknesses. Proactive scenario planning allows you to test your business model against a range of potential threats.

4. Manage Debt and Capital Expenditure Wisely

High levels of debt can become a significant burden in a tightening credit environment.

  • Limit new borrowing: Be cautious about taking on new debt, particularly for non-essential projects. Evaluate every borrowing decision based on its potential return on investment and its impact on your balance sheet.
  • Re-evaluate capital projects: Postpone or cancel major capital expenditures that are not critical for business operations or do not have a clear and immediate path to profitability. Prioritize investments that enhance operational efficiency and resilience.

5. Review and OPTIMISE Operational Costs

A lean and efficient cost structure improves profitability and allows you to better weather economic storms.

6. Build a Strong Risk Culture

Risk management is not just the responsibility of a single department; it should be a shared mindset across the entire organisation.

Bank Of England Repo Red Flag UK Economy Business Risk Management

How poor risk management increases business costs and reduces profits

Targets decision-makers searching for the financial impact of weak risk practices

THE HIDDEN TAX OF POOR RISK MANAGEMENT

Your business is leaking money. Not in the obvious ways — like overspending or inefficiency — but in silent, insidious drains you might not even see. Poor risk management isn’t just about avoiding disasters; it’s a profit killer, a growth stifler, and, in the worst cases, an executioner of businesses that could have thrived.

Enterprise Risk Management Magazine articles for business growth and business protection for a community of professionals on BusinessRiskTV Business Risk Management Club
Your business is leaking £££ Find The Hidden Holes

Consider this: 30% of bankruptcies are due to operational failures that could have been mitigated with better risk practices (OECD). That’s not bad luck—it’s self-inflicted. And if you think your company is immune, think again.

  • This isn’t theoretical. Every day, businesses hemorrhage cash through:
  • Uncontrolled operational risks —process failures, supply chain disruptions, compliance fines.
  • Strategic blind spots —missed opportunities, reputational damage, eroded customer trust.
  • Employee disengagement —teams that don’t see risk as their problem, costing you in errors, delays, and lost innovation.

The result? Lower profitability. Stunted growth. And, in extreme cases, extinction.

But here’s the good news: this is entirely optional and fixable.

In this e-book, we’ll expose the 12 most damaging costs of poor risk management —many of which you’re likely paying right now — and deliver 12 actionable solutions to turn risk from a liability into a competitive advantage. You’ll learn how to:

  • Engage every employee in risk ownership (not just compliance, but profit protection).
  • Stop financial bleed from preventable failures.
  • Turn risk-aware decision-making into a growth engine.

This isn’t another dry risk management manual. This is a survival guide for profitable, resilient business leadership.

Ready to plug the leaks? Let’s begin.


🚨 YOUR BUSINESS IS LEAKING £££ – FIND THE HOLES! 🚨

83% of UK SMEs lose £50k+ yearly from hidden risks they don’t even measure:
❌ Operational failures burning cash
❌ Supply chain disasters killing margins
❌ Cyberattacks costing millions

BusinessRiskTV’s NEW eBook reveals:
✅ 12 PROVEN FIXES to stop profit leaks
✅ Real case studies from UK businesses
✅ Simple checklists to act TODAY

🔥 Stop the bleed—before it’s too late!

#BusinessRisk #ProfitProtection #SMEs #RiskManagement

—

Chapter 1: The Hidden Costs of Poor Risk Management – How Ignoring Risk Erodes Your Profits and Threatens Survival

Introduction: The Silent Profit Killer
Every business faces risks—some obvious, others invisible. But when risk management is an afterthought, those risks don’t just linger; they multiply costs, shrink margins, and sabotage growth. This chapter exposes the real financial and operational toll of poor risk management—and why most businesses underestimate it.

—

1. The Direct Financial Costs: Where the Money Leaks

A. Unexpected Losses from Operational Failures

  • Example: A manufacturing firm ignores equipment maintenance, leading to a breakdown that halts production for 48 hours. The result? £250,000 in lost revenue + £50,000 in emergency repairs.
  • Stat: Companies with weak operational risk management see 30% higher unexpected costs (Deloitte).

B. Regulatory Fines & Legal Penalties

  • Case Study: A UK SME in financial services fails to comply with GDPR, resulting in a £180,000 fine —plus reputational damage.
  • Stat: 60% of small UK businesses aren’t fully compliant with key regulations (FSB).

C. Insurance Premiums & Uncovered Losses

  • Poor risk controls = higher premiums (or worse, insurers refusing coverage).
  • Example: A restaurant without proper fire safety measures faces doubled insurance costs after a minor kitchen fire.

—

2. The Indirect Costs: What You’re Not Measuring (But Should Be)

A. Lost Productivity & Employee Burnout

  • Scenario: A retail chain’s poor inventory risk management leads to constant stock shortages. Staff waste 15 hours/week handling complaints and manual fixes.
  • Stat: Disengaged employees cost UK businesses £340 billion annually (Gallup).

B. Reputation Damage & Customer Attrition

  • Case Study: A data breach at a UK e-commerce firm loses 20% of its customers within 6 months — recovery costs: £500k+ in marketing.
  • Stat: 88% of consumers hesitate to buy after a security incident (PwC).

C. Missed Opportunities & Stunted Growth

  • Example: A tech startup avoids expanding to Europe due to fear of unmanaged risks — competitors seize the market, costing £2M+ in lost revenue.

—

3. The Survival Threat: When Poor Risk Management Becomes Existential

A. Cash Flow Crises

  • Small risks compound: A construction firm’s unpaid invoices (credit risk) + a delayed project (operational risk) = insolvency within 90 days.
  • Stat: 82% of UK business failures cite cash flow issues (Insolvency Service).

B. Investor & Lender Distrust

  • Scenario: A startup’s repeated risk failures scare off venture capital – funding round collapses.
  • Stat: 70% of investors demand robust risk frameworks before backing a business (EY).

C. The Final Cost: Business Collapse

  • Real-Life Example: £7B collapse was rooted in systemic risk blindness —ignoring contract risks, debt, and supply chain failures.

—

4. Why Businesses Underestimate Risk (Until It’s Too Late)

  • “It won’t happen to us” bias
  • Firefighting culture (reacting to risks, not preventing them)
  • Misaligned incentives (short-term profits > long-term resilience)

—

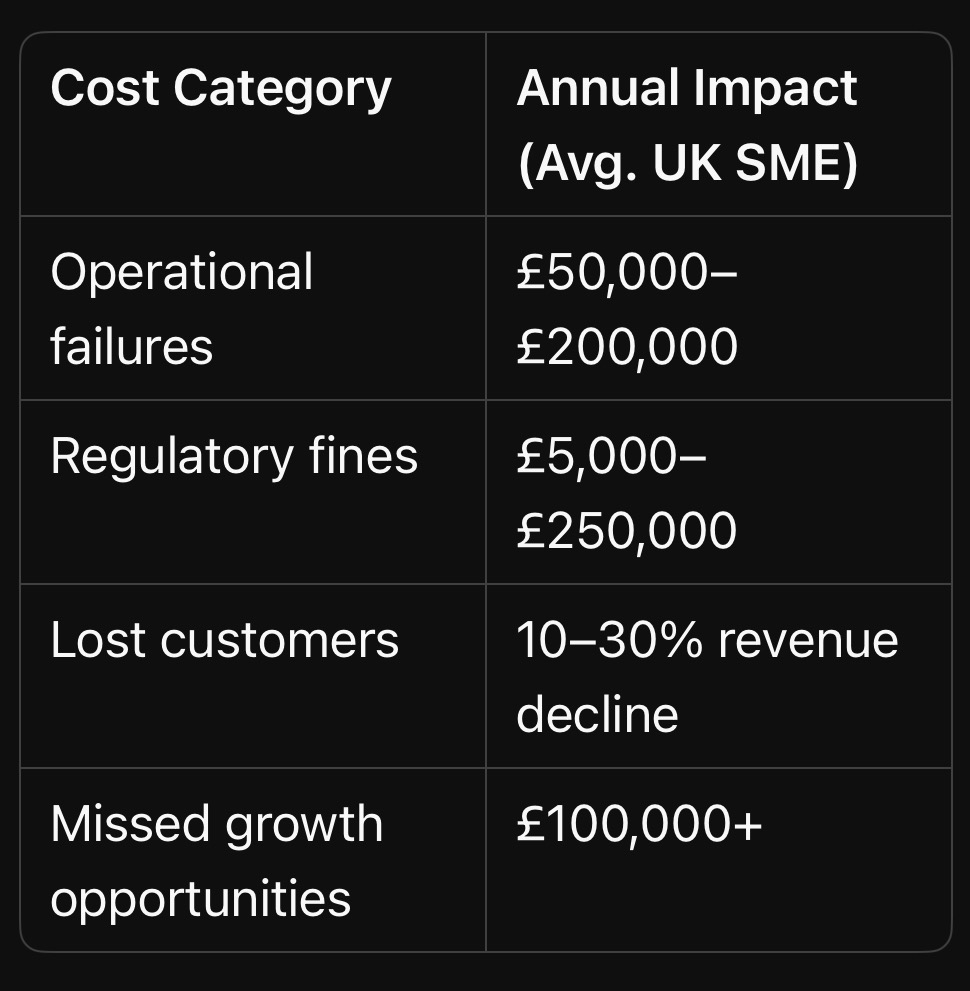
5. The Bottom Line: What Poor Risk Management Really Costs You

Enterprise Risk Management Magazine articles on business growth and business protection
The Bottom Line: What Poor Risk Management Really Costs You


Key Takeaway: Poor risk management isn’t just about avoiding disasters — it’s a tax on profitability, growth, and survival.

—

Actionable Insight: Audit one high-cost risk in your business this week (e.g., late payments, compliance gaps). What’s it really costing you?*

—

Chapter 2: The True Cost of Operational Failures – How Inefficient Risk Management Cripples Your Business

Introduction: The Domino Effect of Poor Operational Risk Controls

Operational risks don’t just cause one-off incidents—they trigger chain reactions that drain cash, demoralise teams, and erode customer trust. This chapter exposes the hidden, cascading costs of mismanaged operational risks and why most businesses only see the tip of the iceberg.

—

1. The Obvious Costs: What You Can’t Ignore

A. Downtime & Lost Production

  • Manufacturing Example: A single machine failure halts a production line for 8 hours → £25,000 in lost output + overtime costs to catch up.
  • Hospitality Example: A restaurant’s refrigeration breakdown spoils £3,000 of stock overnight — plus angry customers.
  • Stat: UK manufacturers lose £180 billion/year to unplanned downtime (EEF).

B. Emergency Repairs & Rush Orders

  • Reactive spending costs 3–5X more than planned maintenance.
  • Case Study: A logistics firm ignores fleet maintenance → two vans fail MOTs simultaneously → £8k in last-minute rentals + delayed deliveries.

C. Waste & Rework

  • Construction Example: Poor quality control leads to £50,000 of defective materials — then doubles labour costs to fix errors.
  • Stat: 20–30% of project budgets are wasted on rework (KPMG).

—

2. The Hidden Costs: What You’re Not Tracking (But Should Be)

A. Employee Productivity Drain

  • Scenario: A retail store’s outdated inventory system causes daily stock discrepancies. Staff waste 4 hours/day manually reconciling data instead of selling.
  • Stat: UK workers spend 15% of their time fixing preventable issues (PwC).

B. Management Distraction & Burnout

  • Small Business Reality: The owner spends 60% of their week putting out fires (supplier delays, IT crashes) instead of growing the business.
  • Psychological Cost: Chronic stress → poor decisions → more risks.

C. Customer Churn & Reputation Erosion

  • E-commerce Example: A fulfilment centre’s picking errors lead to 10% of orders arriving wrong → 15% of customers never return.
  • Stat: 70% of customers switch brands after just 2–3 bad experiences (Salesforce).

—

3. The Strategic Costs: How Operational Risks Stunt Growth

A. Lost Competitive Advantage

  • Case Study: A UK bakery’s unreliable oven delays a product launch by 3 months —competitors dominate supermarket shelves first.

B. Innovation Paralysis

  • Teams stuck in “firefighting mode” never test new ideas.
  • Example: A tech firm’s IT team spends 80% of time fixing outages → zero R&D progress.

C. Investor & Partner Distrust

  • Supply Chain Example: A fashion brand’s repeated delivery failures lead to two major retailers dropping them —£500k annual revenue gone.

—

4. The Survival Threat: When Operational Risks Become Fatal

A. Cash Flow Death Spiral

  • Construction Firm Case Study:
    1. Poor contract risk assessment → unpaid invoices pile up
    2. Equipment breakdown → project delays
    3. Penalties for late delivery → bank calls in loan
    Result: Administration within 6 months.

B. The Carillion Effect

  • How ignoring operational risks (contract mismanagement, cash flow gaps) led to the UK’s biggest corporate collapse.

—

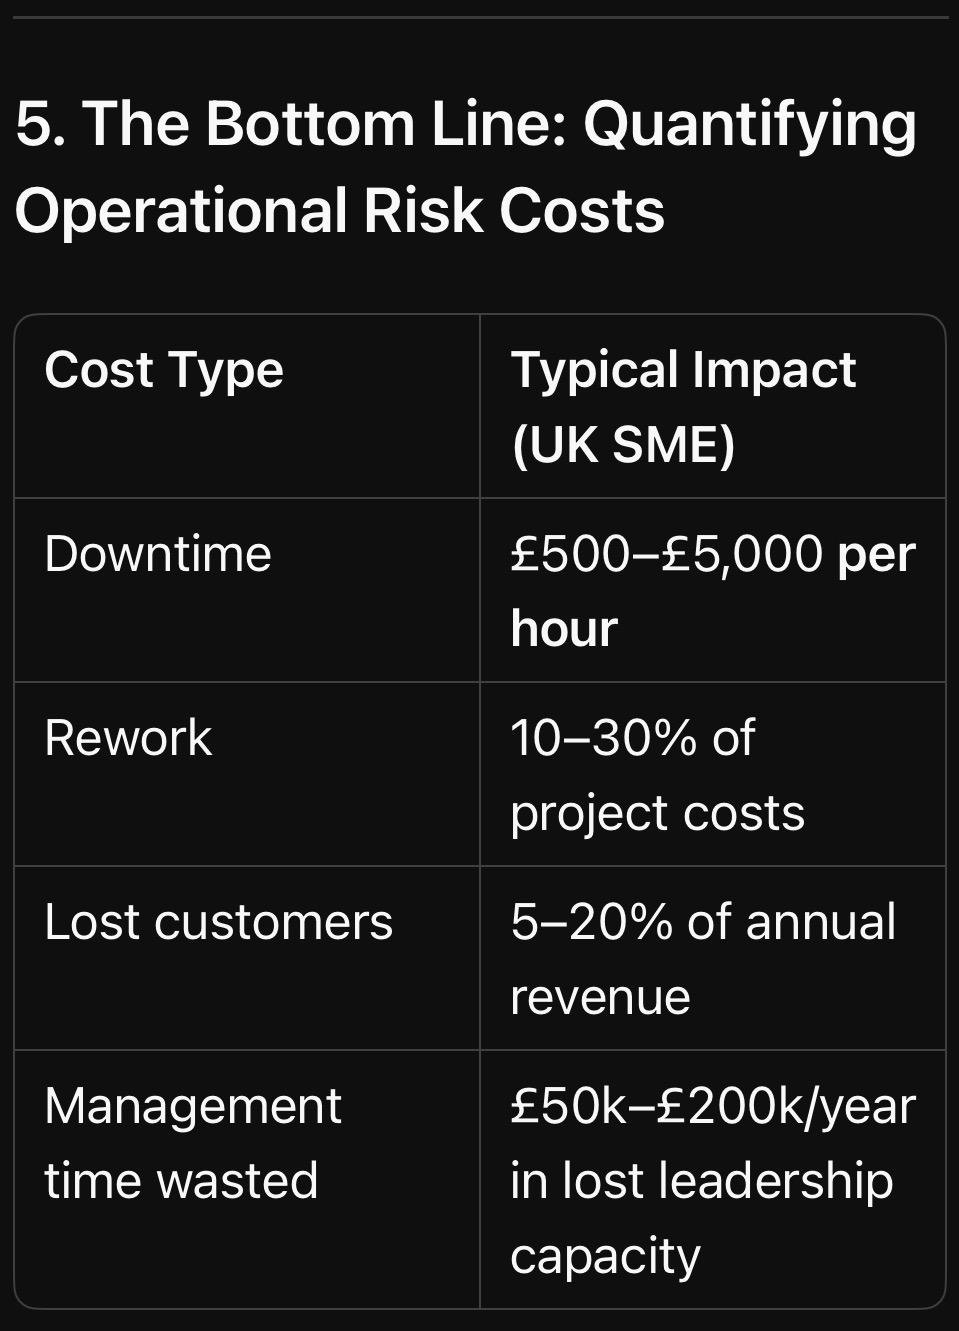
5. The Bottom Line: Quantifying Operational Risk Costs

Enterprise Risk Management Magazine articles for business growth and business protection for an online community of professionals interested in risk management strategies
The Bottom Line: Quantifying Operational Risk Costs

Key Insight: Operational risks don’t just cost money—they steal time, talent, and future opportunities.

—

More From BusinessRiskTV Business Experts Hub : How to Fix It
We explore how to turn operational risk management into a profit centre, including:

  • The 5-minute daily habit that prevents 80% of failures
  • How to engage frontline teams in risk reduction (with real-world examples)

Actionable Task: Map one critical operational process (e.g., order fulfilment). Where could a single failure cost you £10k+?

—

Chapter 3: Strategic Risks – How Blind Spots in Planning Can Bankrupt Even Profitable Businesses

Introduction: The Silent Assassin of Business Growth

Strategic risks don’t announce themselves with alarms — they creep in unnoticed while leadership is distracted by day-to-day operations. By the time the damage is visible, it’s often too late to pivot. This chapter exposes how poor strategic risk management destroys market position, erodes competitive edge, and turns industry leaders into cautionary tales.

—

1. What Are Strategic Risks? (And Why They’re Different)

Strategic risks stem from:

  • Poor market foresight (e.g., Blockbuster ignoring streaming)
  • Flawed business models (e.g., Toys “R” Us failing to adapt to e-commerce)
  • Disruptive competitors (e.g., Uber vs. traditional taxis)
  • Regulatory shifts (e.g., GDPR crushing non-compliant firms)

Key Difference: Unlike operational risks (which drain cash), strategic risks threaten your entire reason for existing.

—

2. The Direct Costs of Strategic Missteps

A. Missed Market Shifts = Lost Revenue

  • Case Study: Kodak invented the digital camera but feared cannibalising film sales. By the time it pivoted, competitors dominated. Result: Bankruptcy.
  • Stat: 52% of Fortune 500 companies since 2000 have disappeared due to strategic failures (Accenture).

B. Failed Expansions & Wasted R&D

  • Example: A UK retailer expands into Europe without assessing local demand. £2M in setup costs → stores close within 18 months.
  • Stat: 70% of corporate transformations fail (McKinsey), often due to poor risk assessment.

C. Reputation Collapse from Strategic Blunders

  • BP’s Deepwater Horizon wasn’t just an operational accident—it was a strategic failure in risk culture, costing $65B+.

—

3. The Hidden Costs: Invisible Erosion of Value

A. Investor Flight & Lower Valuations

  • Scenario: A tech firm’s CEO dismisses AI as a “fad.” Investors shift funds to AI-driven rivals. Share price drops 40% in a year.
  • Stat: Companies with weak strategic risk management trade at 15–20% lower valuations (Harvard Business Review).

B. Talent Drain & Leadership Crises

  • Top talent leaves stagnant companies.
  • Example: A traditional bank loses its best fintech minds to startups after refusing to innovate.

C. Supplier & Partner Defections

  • Case Study: A car manufacturer’s slow EV transition leads key suppliers to prioritise Tesla. Suddenly, parts cost 20% more.

—

4. The Ultimate Cost: Business Obsolescence

A. The “Blockbuster Effect”

  • Not just “bad luck” — a failure to scenario-plan for streaming.
  • Lesson: If your strategy doesn’t include “What if we’re wrong?“, you’re gambling.

B. The UK High Street Bloodbath

  • Maplin, BHS, Debenhams: All had revenue—but no strategy for digital/experiential shifts.

C. The Startups That Scale Into Failure

  • WeWork’s $47B Meltdown: A business model risk (long-term leases vs. short-term rentals) disguised as growth.

—

5. Why Businesses Miss Strategic Risks

  • “Success blindness” (past performance ≠ future proof)
  • Overconfidence in data (ignoring weak signals)
  • Boardrooms detached from market realities

—

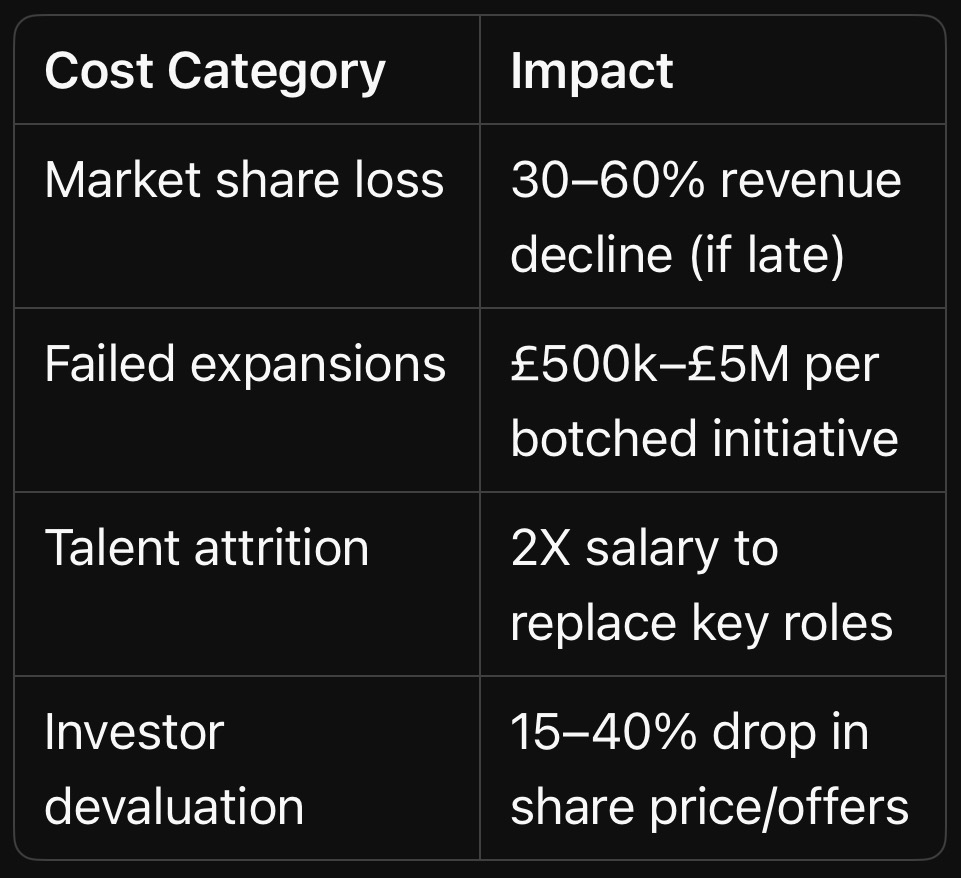
6. The Bottom Line: What Strategic Risks Cost You

Enterprise Risk Management Magazine articles for business growth and business protection for a community of professionals
The Bottom Line: What Strategic Risks Cost You

Key Takeaway: Strategic risks don’t just hurt profits — they erase entire business models.

—

More from BusinessRiskTV Business Experts Hub : How to Anticipate & Outmanoeuvre Strategic Risks
We explore practical frameworks to:

  • Spot industry shifts early (using weak signals)
  • Stress-test your strategy against disruption
  • Turn risks into opportunities (like Amazon’s pivot from books to cloud)

Actionable Task: List one strategic assumption your business relies on (e.g., “Customers will always prefer X”). How would you survive if it’s wrong?

—

Chapter 4: Financial Risks – How Poor Cash Flow & Debt Management Can Sink Your Business Overnight

Introduction: The Silent Killer of Healthy Businesses

Profit doesn’t equal survival. Thousands of UK businesses post record revenues—right before going bust. Why? Because financial risk management isn’t about counting pennies — it’s about anticipating traps that strangle cash flow, trigger defaults, and collapse supply chains.

This chapter exposes the lethal financial risks hiding in plain sight — and why even profitable companies run out of money.

—

1. The Obvious (But Ignored) Financial Risks

A. Cash Flow Crises – The #1 Business Killer

  • Reality: 82% of UK business failures cite cash flow problems as the primary cause (UK Insolvency Service).
  • Example: A £5M-turnover construction firm collapses because:
    – Client pays invoices 90 days late
    – Supplier demands upfront payments due to past delays
    – Bank rejects emergency loan
    Result: Liquidation despite £1.2M in “paper profits.”

B. Debt Avalanches – When Borrowing Backfires

  • Case Study: A fast-growing e-commerce firm takes on high-interest debt to fund inventory. Sales dip, interest compounds, and suddenly 60% of revenue services debt.
    – Stat: 40% of UK SMEs struggle with unmanageable debt (Bank of England).

C. Currency & Commodity Swings

  • Example: A UK bakery’s flour costs jump 30% after a wheat shortage. Contracts lock in prices — margins vanish overnight.

—

2. The Hidden Financial Risks That Compound Quietly

A. Customer Concentration Risk

  • Scenario: A B2B software firm gets 70% of revenue from one client. When that client leaves, payroll can’t be met.
  • Rule of Thumb: No single client should exceed 15–20% of revenue.

B. Supplier Dependency & Price Shocks

  • Case Study: A car manufacturer relies on one battery supplier. When shortages hit, production stalls for 3 months → £9M loss.

C. Fraud & Financial Mismanagement

  • Stat: UK businesses lose £137B yearly to fraud, waste, and accounting errors (PwC).
  • Example: A finance director “cooks the books” — investors pull out when the truth surfaces.

—

3. The Strategic Fallout: When Financial Risks Spiral

A. Credit Downgrades & Banking Nightmares

  • Example: A once-stable firm misses a loan covenant — interest rates spike 5%, lines of credit freeze.

B. Investor Panic & Equity Crashes

  • Case Study: A tech startup’s burn rate exceeds projections — VCs demand emergency restructuring, slashing valuation by 50%.

C. Employee Exodus (When Paychecks Bounce)

  • Stat: 78% of employees leave within 6 months of payroll issues (CIPD).

—

4. The Ultimate Cost: Bankruptcy Dominoes

A. The “Profitable But Insolvent” Paradox

How It Happens:
1. Big contracts signed → revenue looks strong
2. Clients pay late → cash dries up
3. Suppliers demand payment → no money for salaries/tax
4. HMRC forces liquidation despite “growth.”

B. The Carillion Effect (Again)

  • £7B collapse triggered by:
    – Aggressive accounting
    – Reliance on unsustainable contracts
    – No cash buffer for delays

—

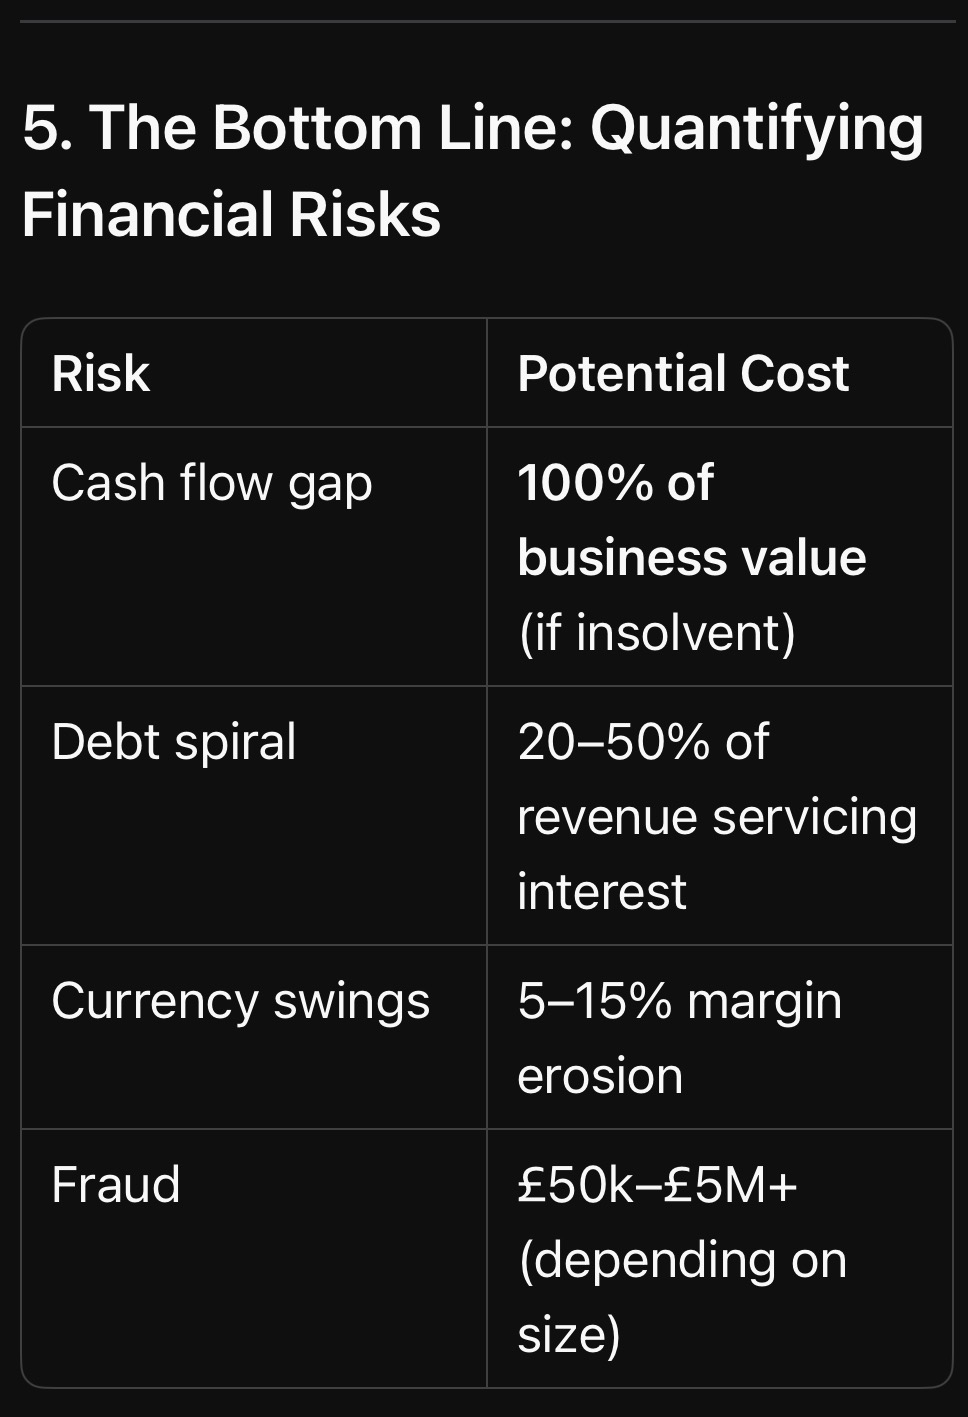
5. The Bottom Line: Quantifying Financial Risks

Enterprise Risk Management Magazine for business growth and business protection for online community of professionals on Business Risk Management Club
The Bottom Line: Quantifying Financial Risks

Key Insight: Financial risks don’t just reduce profits — they erase businesses in weeks.

—

More from BusinessRiskTV Business Experts Hub : How to Fix It
We explore real-world financial risk strategies, including:

  • The 13-week cash flow rule (used by turnaround experts)
  • How to renegotiate debt before it’s too late
  • Building a “war chest” for crises

Actionable Task: Run a “stress test” on your cash flow: What if 2 clients pay 60 days late?

—

Chapter 5: Cyber Risks – The Invisible Threat That Could Bankrupt Your Business by Breakfast

Introduction: The Digital Time Bomb Ticking in Your Business

Imagine arriving at work to find:

  • Your customer database on the dark web
  • Fraudsters draining £250,000 from your account
  • Ransomware locking every file until you pay Bitcoin

This isn’t a movie plot — it’s Monday morning for thousands of UK businesses. Cyber risks don’t just steal data; they extort cash, destroy reputations, and trigger regulatory hell. And here’s the worst part: Most victims never see it coming until the damage is done.

—

1. The Direct Costs: What Happens When Cybercrime Hits

A. Ransomware: The Digital Kidnapping Epidemic

  • 2023 Reality: A UK construction firm’s blueprints, invoices, and payroll systems encrypted. Hackers demand £120,000 to unlock files.
  • Stat: 73% of UK businesses hit by ransomware in 2023 (NCSC).
  • Brutal Truth: Paying doesn’t guarantee recovery — 32% never get full data back (Sophos).

B. Data Breaches: When Your Customers Become Victims

  • Case Study: A mid-sized retailer’s poorly secured e-commerce platform leaks 380,000 credit cards.
  • £500,000 GDPR fine
  • £1.2M in fraud reimbursements
  • 22% customer churn
  • Stat: Average UK data breach cost: £3.4 million (IBM).

C. Business Email Compromise (BEC): The Silent Heist

  • How It Works: A hacker impersonates your CEO, emails finance: “Urgent: Transfer £80k to new supplier.”
  • UK Losses: £1.3 billion stolen via BEC in 2023 (UK Finance).

—

2. The Hidden Costs That Cripple You Later

A. Reputation Freefall & Customer Exodus

  • After a breach:
    – 58% of customers avoid breached brands (Verizon)
    – Recovery Cost: 3–5X more on marketing to rebuild trust

B. Operational Paralysis

  • Example: A law firm’s servers go down for 72 hours post-attack. £350k in billable hours lost + client lawsuits.

C. Insurance Nightmares

  • Post-Claim Realities:
    – Premiums triple
    – Mandatory audits drain management time
    – Some policies simply won’t renew

—

3. The Strategic Fallout: Long-Term Business Damage

A. Lost Contracts & Blacklisting

  • Government/Corporate Tenders Now Demand:
    – Cyber Essentials Certification (missing? Disqualified automatically)
    – Proof of incident response plans

B. Investor Flight

  • Startup Killer: A fintech’s pre-IPO breach scares off VCs, slashing valuation by 60%.

C. Director Liability (Yes, You Can Go to Jail)

  • UK Law: Under GDPR & NIS Directive, negligent executives face fines up to £17.5M or 4% of global revenue — plus disqualification.

—

4. Why Cyber Risks Are Worse Than You Think

A. It’s Not Just “Big Targets”

  • 61% of UK attacks hit SMEs (Verizon) — hackers bet they’re unprepared.

B. Remote Work = 300% More Attack Surfaces

  • Example: An employee’s compromised home laptop gives hackers access to your entire CRM.

C. AI-Powered Attacks Are Here

  • New Threat: Deepfake audio of your CFO “calling” finance to wire funds.

—

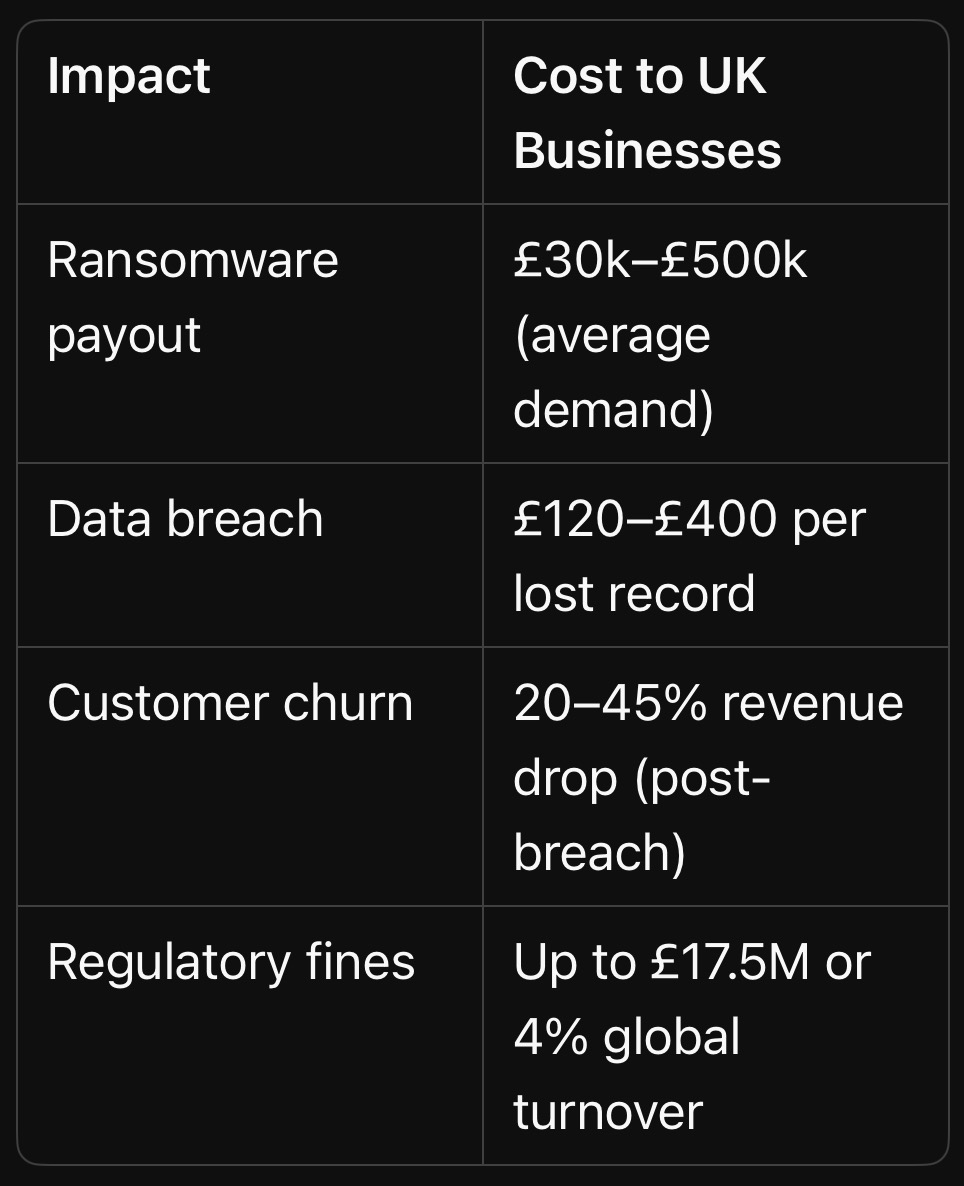
5. The Bottom Line: Cyber Risk Costs

Enterprise Risk Management Magazine articles on business growth and business protection for online community of professionals interested in risk management strategies
The Bottom Line: Cyber Risk Costs

Key Insight: Cyber risks aren’t an “IT problem” — they’re an existential business threat.

—

More from BusinessRiskTV Business Experts Hub : How to Fight Back
We will explore real-world cyber defenses, including:

  • The 5-step SME ransomware shield (costs <£5k/year)
    – How to trick hackers into avoiding you (attackers prefer easy targets)
    – Turning employees into human firewalls

Actionable Task: Run this free test now: [Have I Been Pwned](https://haveibeenpwned.com/) to check if your work emails are already in hacker databases.

—

Chapter 6: Human Risks – When Your Greatest Asset Becomes Your Biggest Liability

Introduction: The Enemy Inside Your Walls

Your employees can either be your strongest defence — or your weakest link. Negligence, disengagement, and malicious actions cost UK businesses £30 billion annually (ACAS). This chapter exposes how poor people risk management leads to:
– Catastrophic errors
– Culture collapse
– Regulatory disasters
– Fraud epidemics

And why traditional HR policies fail to prevent 89% of these risks (PwC).

—

1. The Obvious (But Ignored) Human Risks

A. The High Cost of Disengagement

  • Example: A retail chain’s apathetic staff miss 40% of shoplifting incidents —costing £220,000/year in stolen stock.
  • Stat: Disengaged employees are 450% more likely to cause operational errors (Gallup).

B. Turnover Tsunamis

  • Case Study: A tech firm’s toxic culture drives out 7 senior engineers in 6 months — delaying a £2M product launch by 11 months.
  • Replacement Cost: Up to 2X annual salary per lost employee (Oxford Economics).

C. Training Gaps That Become Legal Nightmares

  • Reality Check: A warehouse worker badly operates a forklift, causing £80k in damages + HSE fines—because “training was just a 10-minute video.”

—

2. The Hidden (But More Dangerous) Human Risks

A. Insider Threats: When Employees Attack

  • Shocking Stat: 58% of data breaches involve insiders (Verizon).
  • Methods:
    – The Malicious: IT admin sells customer data (£50k on dark web)
    – The Careless: Accountant emails payroll files to personal Gmail

B. Culture Risks: How Toxicity Spreads

  • Example: A sales team’s “win at all costs” mentality leads to fraudulent client promises — £600k in lawsuits + FCA investigation.

C. Leadership Blind Spots

  • CEO Overconfidence: Ignoring team warnings about a flawed expansion → £3M write-off.
  • Stat: 82% of business failures trace back to poor leadership decisions (KPMG).

—

3. The Strategic Fallout: When People Risks Sink Companies

A. The Volkswagen Emissions Scandal

  • Root Cause: A culture where “nobody dared question” fraudulent engineering.
    – Cost: €32 billion in fines/losses + permanent brand damage.

B. The Barclays CEO Scandal

  • How It Happened: Leadership’s obsession with “star hires” led to unchecked bullying — triggering £1M fines + investor revolt.

C. The Everyday SME Killer

  • Scenario: Your “trusted” bookkeeper embezzles £150k over 3 years — exposed only during a tax audit.

—

4. Why Traditional Approaches Fail

  • Annual compliance training? 86% of employees forget it within 30 days (MIT).
  • “Hotline whistleblowing”? 62% of staff fear retaliation (EY).
  • Top-down policies? Frontline teams see them as “head office nonsense.”

—

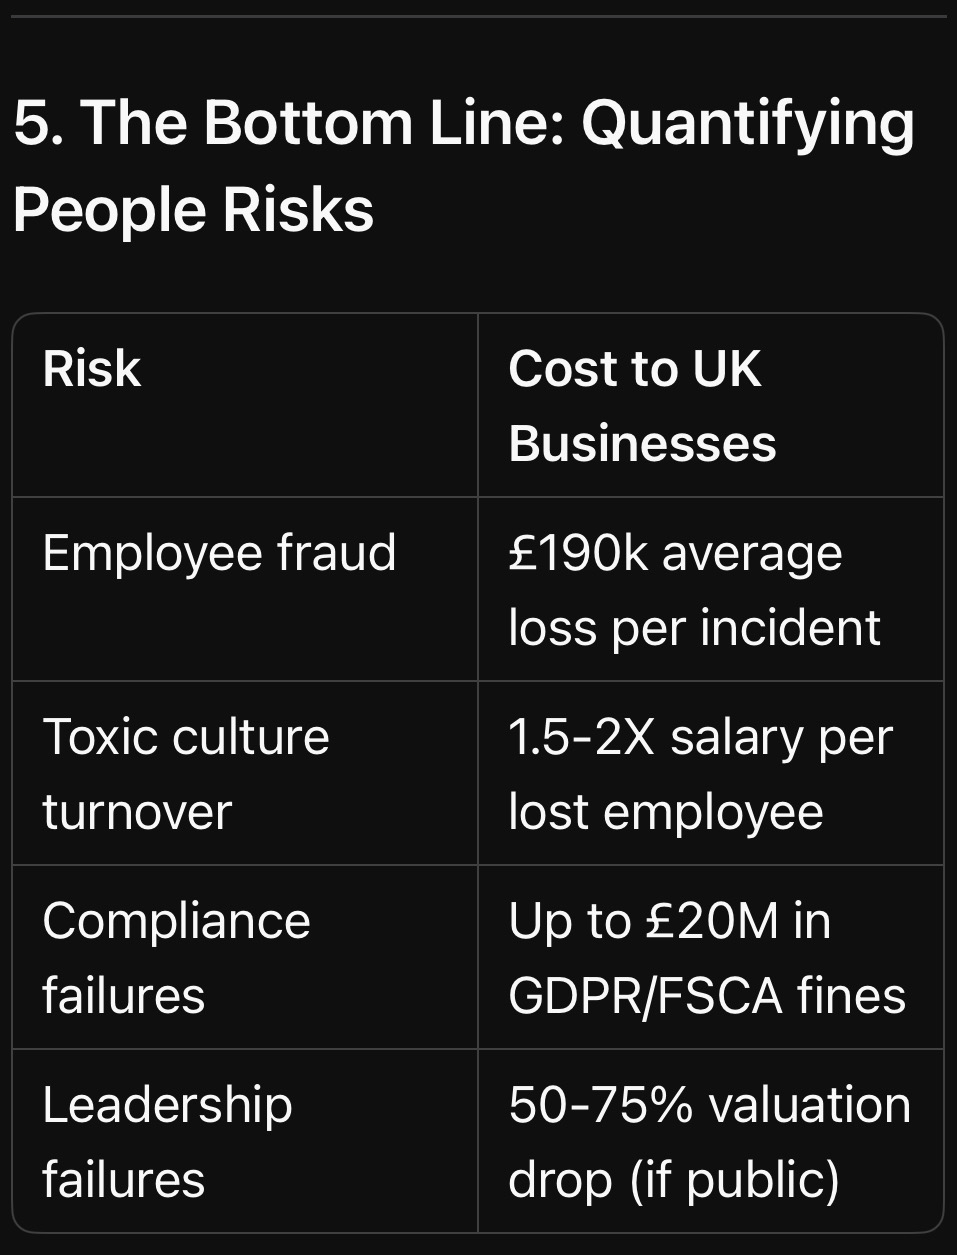
5. The Bottom Line: Quantifying People Risks

Enterprise Risk Management Magazine articles on business growth and business protection for online community of professionals interested in risk management strategies
The Bottom Line: Quantifying People Risks

Key Insight: Your employees create or destroy value daily — often without realising it.

—

More from BusinessRiskTV Business Experts Hub : How to Transform Human Risk into Advantage
We explore battle-tested solutions, including:

  • The “Psychological Safety” hack
  • How to spot insider threats before they strike
  • Turning compliance into competitive edge

Actionable Task: Run a 5-minute “risk culture pulse check” with your team this week: “What’s one process you think could fail catastrophically?”

—

Chapter 7: Supply Chain Risks – The Fragile Web That Could Strangle Your Business Overnight

Introduction: Your Business Is Only as Strong as Its Weakest Supplier

A single delayed shipment. One insolvent vendor. A geopolitical shockwave. Suddenly, your production line stops, customers revolt, and cash flow evaporates.

Supply chain risks aren’t hypothetical—they’re profit-killing realities:

  • 43% of UK companies faced severe supply disruptions in 2023 (CIPS)
  • 1 in 5 SMEs nearly collapsed due to supplier failures (FSB)
  • The average disruption costs £225k (Lloyd’s of London)

This chapter exposes how vulnerable your supply chain really is — and why “just-in-time” has become “just-too-late” for thousands of businesses.

—

1. The Visible Supply Chain Killers

A. Supplier Collapses – The Domino Effect

  • 2023 Reality: A key automotive parts supplier goes bankrupt → 3 UK car plants idle for 6 weeks → £180M in lost production.
  • Stat: 58% of businesses have no backup for critical suppliers (Deloitte).

B. Logistics Breakdowns

  • Red Sea Crisis Fallout: Shipping costs spike 400%, delays stretch to 8 weeks → retailers miss entire seasonal sales windows.
  • Brexit Hangover: 27% of UK manufacturers still face customs delays (Make UK).

C. Price Volatility & Extortion

  • Example: A bakery’s flour supplier doubles prices overnight due to war in Ukraine — contracts force them to absorb the cost.

—

2. The Hidden (But More Dangerous) Supply Chain Risks

A. Single-Point Failures

  • Case Study: A pharma company relies on one Indian API supplier — FDA bans the factory → 2-year drug shortage.

B. Quality Failures That Slip Through

  • Costly Reality: A construction firm’s “cheaper” Chinese steel fails safety tests → £1.2M in rework + penalty clauses.

C. Forced Labour & Compliance Bombshells

  • US/Uyghur Forced Labor Act: Companies unknowingly using Xinjiang cotton face seized shipments + 20% tariffs.

—

3. The Strategic Fallout When Chains Break

A. Customer Mass Exodus

  • Example: An electronics retailer’s Christmas stock arrives January 5th → 35% return rate + brand hashtag trends in anger.

B. Cash Flow Cardiac Arrest

How It Happens:

  • Prepay for inventory → delays eat working capital
  • Miss delivery deadlines → penalty payments
  • Banks freeze credit lines

C. The Reputation Reckoning

  • Boohoo’s Leicester Scandal: £1B market cap wiped out after slave labour exposé.

—

4. Why Traditional “Solutions” Fail

  • Dual Sourcing? Most secondary suppliers use the same raw material sources.
  • Bigger Inventories? Eats cash flow + risks obsolescence.
  • Longer Contracts? Locks you into outdated pricing.

—

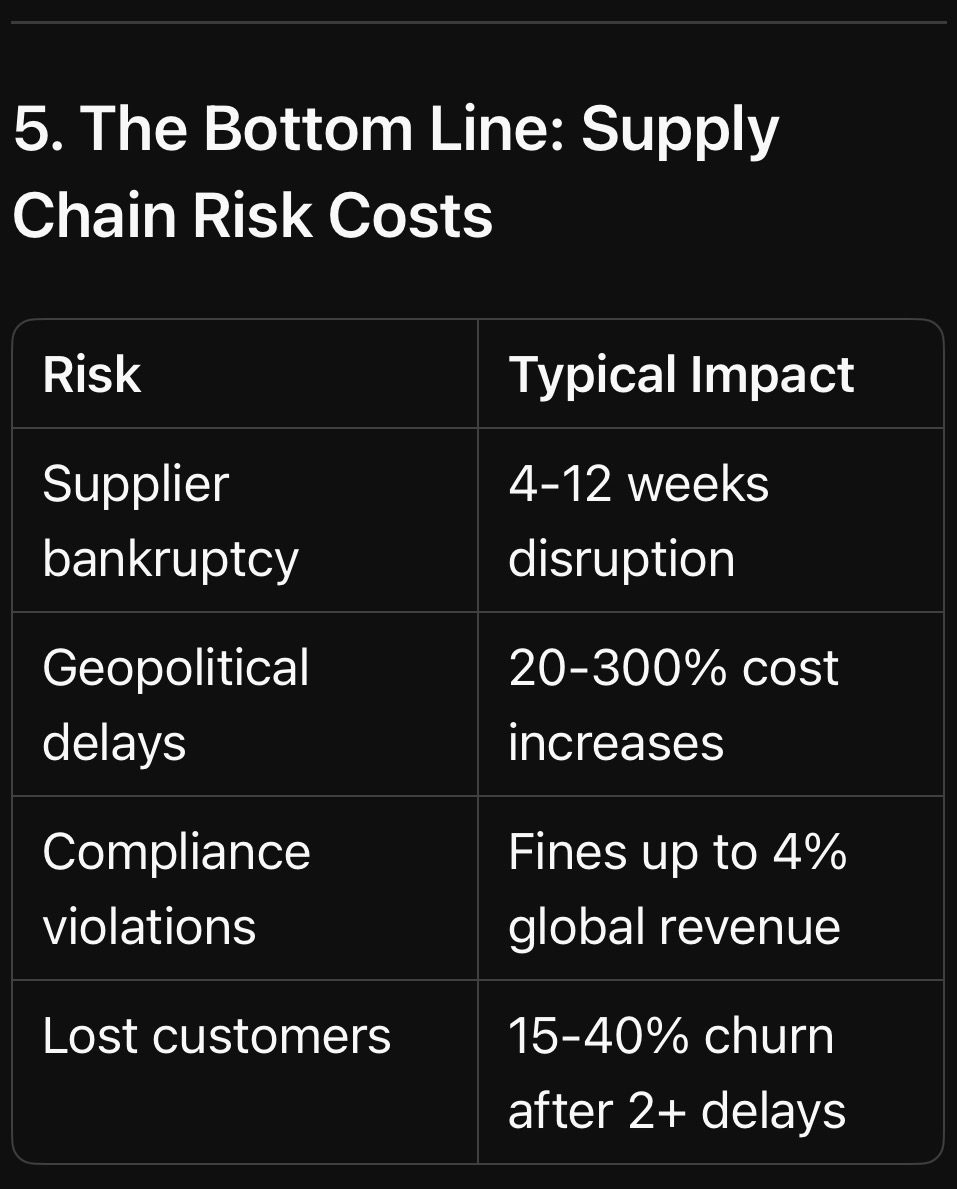
5. The Bottom Line: Supply Chain Risk Costs

Enterprise Risk Management Magazine articles for business growth and business protection for online community of professionals interested in risk management strategies
The Bottom Line: Supply Chain Risk Costs

Key Insight: Supply chains have become the ultimate leverage point — for your competitors or your downfall.

—

More from BusinessRiskTV Business Experts Hub : How to Build an Unbreakable Supply Chain
We explore wartime-tested strategies, including:

  • The “3D Supplier Mapping” trick (used by Special Forces logisticians)
  • How to turn suppliers into partners (not adversaries)
  • When to nearshore/onshore without bankrupting yourself

Actionable Task: Identify one “critical” supplier you couldn’t operate without. How would you survive if they vanished tomorrow?

—

Chapter 8: Reputational Risks – When Trust Collapses Faster Than Your Share Price

Introduction: The 24-Hour Business Execution

A single tweet. One viral video. A disgruntled employee’s LinkedIn post. In today’s digital wildfire, your hard-earned reputation can evaporate before your crisis team finishes their first coffee.

The brutal reality:

  • 87% of consumers will abandon a brand after a reputation crisis (YouGov)
  • It takes 4-7 years to build trust but just 4 bad days to destroy it (Edelman Trust Barometer)
  • 65% of a company’s market value is tied to intangible assets like reputation (Ocean Tomo)

This isn’t about PR spin – it’s about preventing the preventable and surviving the unpredictable.

—

1. The Obvious Reputation Killers

A. Social Media Firestorms

  • Case Study: A restaurant manager’s racist comment caught on video → 300,000 angry tweets in 48 hours → permanent 40% revenue drop
  • Stat: Viral crises spread 20x faster than management can respond (MIT Sloan)

B. Executive Scandals

  • The P&G CEO Effect: A $375 billion company lost $40B in market cap in days after CEO’s inappropriate relationship surfaced

C. Product Failures Gone Viral

  • Samsung Note 7 Disaster: Exploding phones cost $17B + 3-year brand recovery

—

2. The Hidden Reputation Risks

A. “Slow Burn” Erosion

  • Example: A bank’s 1,200 small complaints/month on Trustpilot → unnoticed 2% annual customer attrition → £200M revenue gone in 5 years

B. Guilt by Association

  • Reality: Your 3rd-tier supplier’s child labour scandal becomes YOUR front-page crisis

C. Algorithmic Assassination

  • Google’s Autocomplete Effect: “YourBrand + lawsuit/scam/fraud” suggestions deter 63% of potential customers (Moz)

—

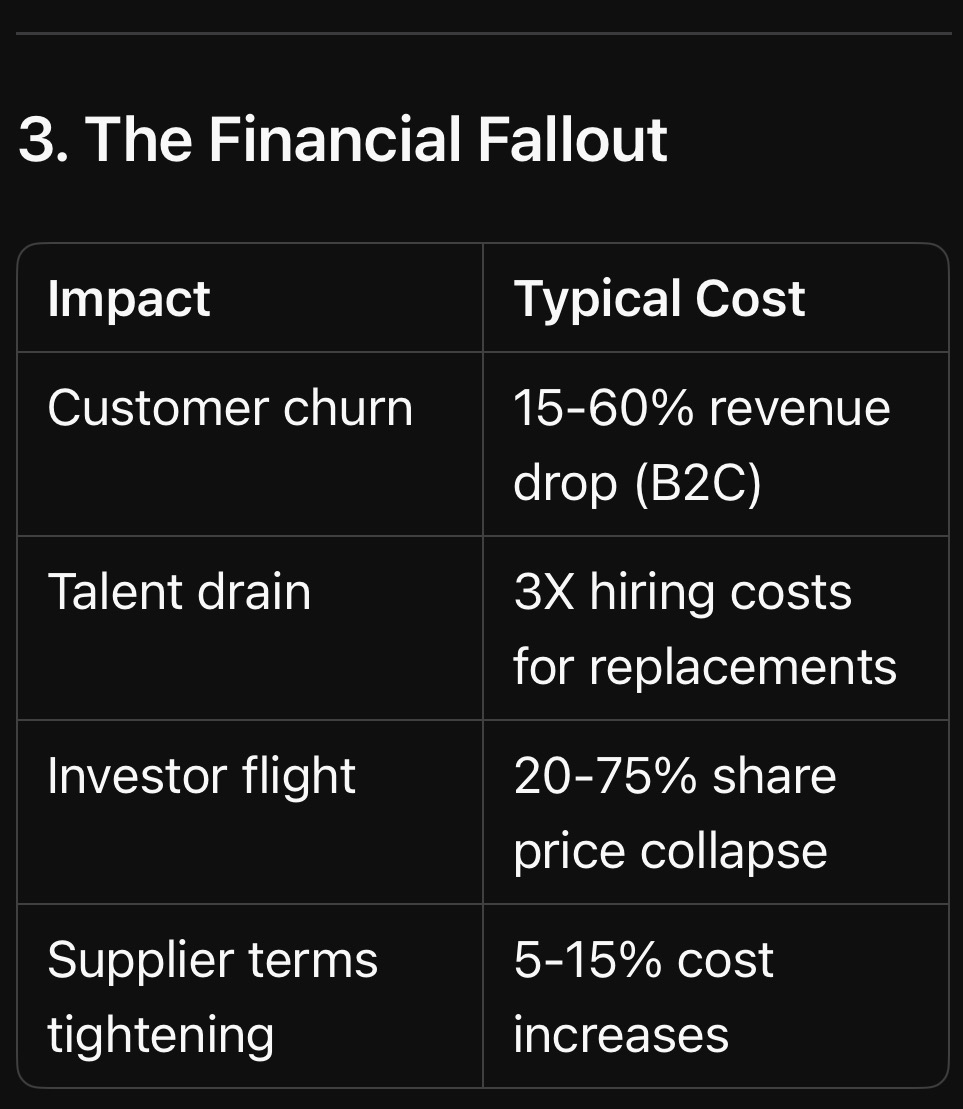
3. The Financial Fallout

Enterprise Risk Management Magazine articles on business growth and business protection for online community of professionals interested in risk management strategies
The Financial Fallout From Reputational Risk

The Domino Effect:
1. Crisis hits → 2. Customers leave → 3. Talent flees → 4. Investors panic → 5. Suppliers demand cash upfront

—

4. Why Traditional PR Fails

  • “No comment” = “We’re guilty” in public perception
  • Corporate-speak increases distrust by 41% (Edelman)
  • Legal-first responses often worsen the crisis

—

5. The Survival Playbook (Preview)

More from BusinessRiskTV Business Experts Hub we will explore modern reputation armour, including:

  • The “Dark Web Early Warning” system (catch crises before they explode)
  • Turning employees into reputation ambassadors
  • When to apologise vs. when to fight back

Actionable Task: Google “[Your Brand] + scandal” right now. What autocomplete suggestions appear?

—

Chapter 9: Climate Risks – The Existential Threat That’s Already Costing Your Business

Introduction: Your Business Is on the Frontlines of the Climate Crisis

Climate change isn’t a distant threat — it’s eroding profits, disrupting supply chains, and rewriting industry rules right now. In 2024 alone, climate disasters caused $2 trillion in global losses, with businesses absorbing the brunt through:

  • Operational shutdowns (e.g., factories flooded, data centres overheated
  • Soaring insurance premiums (up 300% in high-risk zones)
  • Regulatory penalties (e.g., non-compliance with carbon disclosure rules)

This chapter exposes the hidden costs of climate risks — and why most companies are dangerously unprepared.

—

1. The Two Faces of Climate Risk

A. Physical Risks: When Nature Attacks

1. Acute Disasters:
– Example: Hurricane Helene (2024) caused $225B in damages, disrupting microchip supplies by destroying a key quartz supplier .
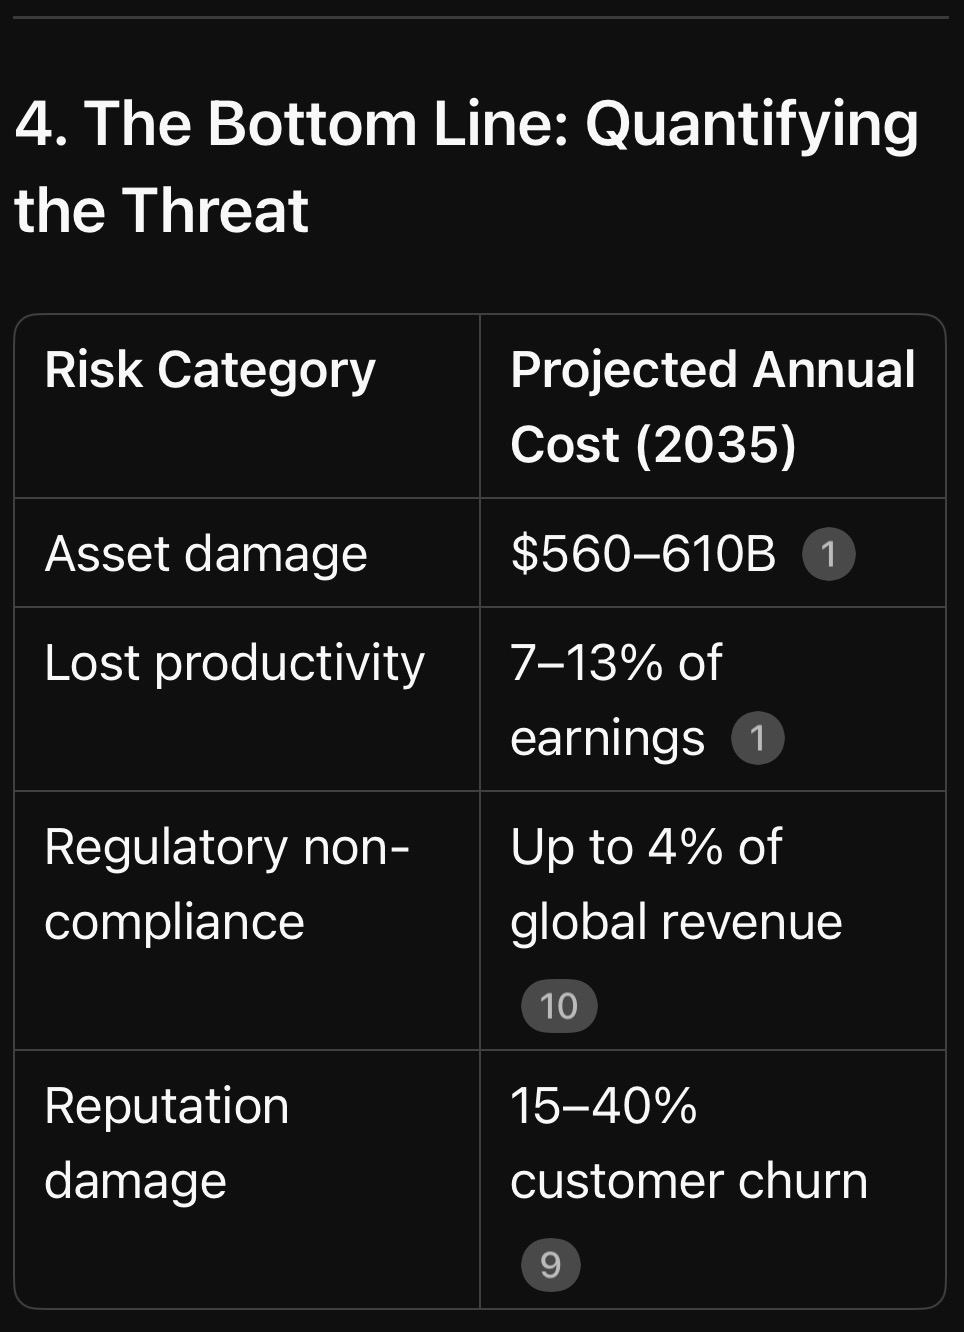
– Stat: Severe weather events now cost businesses $560–610B yearly in asset losses .

2. Chronic Pressures:
– Heatwaves reduce worker productivity by 15–20% in sectors like construction and agriculture .
– Droughts forced a UK beverage company to halt production for 6 weeks due to water shortages .

B. Transition Risks: The Legal and Market Backlash

1. Policy Shocks:
– Carbon taxes could erase 20% of profits for high-emission firms by 2030 .
– Example: EU’s Carbon Border Tax added 10–20% costs for non-compliant imports .

2. Reputation Fallout:
– 75% of consumers boycott brands with poor sustainability records .
– Investor Flight: ESG-backlash aside, 90% of Fortune 500 firms now face shareholder climate lawsuits .

—

2. The Hidden Costs You’re Not Tracking

A. Supply Chain Domino Effects

  • Case Study: Floods in Thailand (2023) disrupted 40% of global hard drive production → tech firms lost $20B+
  • Stat: 73% of companies admit their supply chains are “highly vulnerable” to climate shocks .

B. Workforce Crises

  • Heat Stress: UK warehouses saw 30% more sick days during 2024’s record summer .
  • Talent Drain: 67% of Gen Z employees reject jobs at firms with weak climate policies .

C. Stranded Assets

  • Example: Oil companies wrote off $300B in reserves as “unburnable” due to net-zero policies.
  • Projection: 20% of commercial real estate will be uninsurable by 2030 .

—

3. Why Businesses Underestimate Climate Risks

  • “It Won’t Happen Here” Bias: 80% of SMEs lack climate contingency plans .
  • Short-Termism: Only 20% of executives prioritise climate risks over quarterly targets.
  • Data Gaps: Most firms rely on “best guess” estimates for emissions and vulnerabilities .

—

4. The Bottom Line: Quantifying the Threat

Enterprise Risk Management Magazine articles on business growth and business protection for online community of professionals interested in risk management strategies
The Bottom Line: Quantifying the Threat from Climate Risk

Key Insight: Climate risks are profit killers — not just “ESG checkboxes.”

—

More from BusinessRiskTV Business Experts Hub : How to Fight Back
We will explore actionable climate resilience strategies, including:

  • The “3D Supply Chain Mapping” tactic (used by Special Forces logisticians)
  • How to turn carbon cuts into tax savings
  • AI-powered climate forecasting tools

Actionable Task: Run a 5-minute vulnerability scan: Which single climate threat (e.g., flood, heatwave) could shut down your operations for 48 hours?

—

*Sources: World Economic Forum , Allianz , Beazley , Optera , EPA *

Chapter 10: 12 Actionable Solutions to Transform Risk into Competitive Advantage

Introduction: Risk Management Isn’t About Survival—It’s About Dominance

The most profitable companies don’t just avoid risks — they weaponise them. Toyota’s supply chain resilience made it the #1 automaker during the chip shortage. Amazon turned cybersecurity into a $35B AWS profit centre.

This chapter delivers 12 battle-tested solutions to stop losing money and start outpacing competitors.

—

Solution 1: The “Risk Ownership” Culture Hack

  • Problem: Employees see risk as “management’s problem.”
  • Fix:
    – Tie 10-15% of bonuses to risk KPIs (e.g., near-miss reports, compliance audits)
    – Example: A logistics firm reduced warehouse injuries by 62% after adding safety metrics to performance reviews

Action Step: This week, have each department identify one preventable risk they’ll now “own.”

—

Solution 2: The 5-Minute Daily Risk Radar

  • Problem: Monthly reports miss emerging threats.
  • Fix:
    – Daily 5-minute standups on:
  • Top 3 operational vulnerabilities (e.g., server capacity, inventory levels)
  • Weak signals (e.g., supplier payment delays, social media complaints)
  • Case Study: A manufacturer caught a critical component shortage 3 weeks early by tracking supplier lead times daily

**Template:**
“`
[ ] Key risk #1 status
[ ] New threat detected
[ ] Mitigation action
“`

—

Solution 3: Cyber “Human Firewall” Training That Works

  • Problem: Boring compliance training fails.
  • Fix:
  • Monthly simulated phishing with “hacked” employees retaking interactive VR training

Result: One law firm reduced click-through rates from 28% to 3% in 6 months

Free Tool: Use CanIPhish for automated simulations

—

Solution 4: The 13-Week Cash Flow War Chest

  • Problem: Companies die from cash flow gaps, not lack of profit.
  • Fix:
    1. Map all cash inflows/outflows week-by-week
    2. Identify 3 survival levers (e.g., delayed payables, early collections)
    3. Stress test with:
    – 30% sales drop
    – 60-day client payment delays

Example: A restaurant chain survived COVID by pre-negotiating 90-day rent deferrals before lockdowns

—

Solution 5: Supplier “X-Ray” Audits

  • Problem: 4th-tier suppliers can bankrupt you.
  • Fix:
    – Demand blockchain-tracked materials for critical inputs
    – Red Team Test: Randomly delay payments to check supplier liquidity
    – Stat: Firms with mapped supply chains recover 9x faster from disruptions

—

Solution 6: AI-Powered Risk Forecasting

Toolkit:

  • Climate: Cervest (predict asset flooding)
  • Cyber: Darktrace (autonomous threat detection)
  • Financial: Simudyne (stress test scenarios)

ROI Example: A insurer cut claims by 22% using flood prediction AI

—

Solution 7: The “Pre-Mortem” Strategy Session

  • Problem: Executives ignore failure scenarios.
  • Fix: Before decisions:
    1. Imagine the project has failed catastrophically
    2. Brainstorm exactly why
    3. Build safeguards

Case Study: Boeing’s 737 Max crashes could’ve been prevented by this method

—

Solution 8: Embedded Risk Officers

Innovation: Place risk champions in:
– R&D teams (kill flawed prototypes early)
– Sales (flag unrealistic client promises)
– Result: A pharma firm avoided $200M in FDA fines by catching compliance gaps during drug development

—

Solution 9: Dynamic Risk Scoring

Tool: Custom risk dashboards weighting:
– Probability (1–10)
– Impact (£)
– Velocity (how fast threat is growing)
– Example: A bank auto-prioritises risks scoring >£500k impact

—

Solution 10: The “Unthinkable” Drill

Annual Exercise: Simulate:
– CEO arrested
– HQ destroyed
– Key Result: BrewDog survived a ransomware attack because they’d practiced IT failovers quarterly

—

Solution 11: Turn Risk Into Revenue

Examples:
– Tesla sells carbon credits ($1.8B in 2023)
– Maersk’s green shipping premiums command 20% price hikes

—

Solution 12: The Risk Transparency Report

Innovation: Publicly share:
– Top 5 near-misses
– Lessons learned
– Outcome: Unilever’s radical transparency boosted investor trust post-crisis

—

Final Action: Your 30-Day Risk Revolution

1. Pick 3 solutions to implement now
2. Assign owners/deadlines
3. Report results in next quarter’s board pack

Remember: Risk mastery isn’t about fear — it’s about freedom to outmaneuver competitors.

—
Need help prioritising solutions for your industry? Reply with your sector for tailored advice

Get help to protect and grow your business faster with BusinessRiskTV

Find out more about Business Risk Management Club

BusinessRiskTV Business Risk Management Club Membership

Subscribe for free business risk management tips risk reviews and cost reduction ideas

Connect with us for free risk alerts and risk management newsletters 

Contact BusinessRiskTV

Read more business risk management articles and view videos for free

Connect with us for free risk management articles and video releases

Enterprise Risk Management Magazine BusinessRiskTV ERM Magazine

Read more risk management strategies articles and view videos :

1. “How poor risk management increases business costs and reduces profits”

2. “Operational risk failures that hurt profitability and how to fix them”

3. “Why businesses fail due to unmanaged risks and how to survive”

4. “Employee engagement strategies for better risk management in business”

5. “Hidden costs of ignoring risk management in small and medium enterprises”

Relevant hashtags :

1. #UKBusinessRisk

2. #ProfitProtection

3. #SMEsAtRisk

4. #BusinessSurvivalGuide

5. #LeadershipRisk

How poor risk management increases business costs and reduces profits